Bahrain finance guides
Fixed deposits in Bahrain: compare rates, terms and early withdrawal
By Gaurav Agarwal · Sources checked 6 October 2026
Compare written quotes for the same amount, currency and term, including payment dates, all charges, early-exit value and renewal instructions. Confirm deposit-protection eligibility and aggregate eligible balances held at the same legal bank.
A fixed deposit in Bahrain should be compared using the currency, amount, term, payment schedule and cost of withdrawing early. Ask each bank for a written quote on the same date, including the amount you would receive at maturity. A posted annual rate is a starting point, not a personal offer or the return earned over a shorter deposit term.
Checked 6 October 2026. The examples below come from official bank product pages, deposit terms and published tariffs. They are a terms comparison, not a ranking of the highest rates. The linked ila rate table still carries a May 2026 effective date, so confirm the rate available when you book. This guide focuses on conventional fixed deposits; Islamic investment contracts and everyday savings accounts need their own product terms.
Which currency, amount and term does the quote assume?
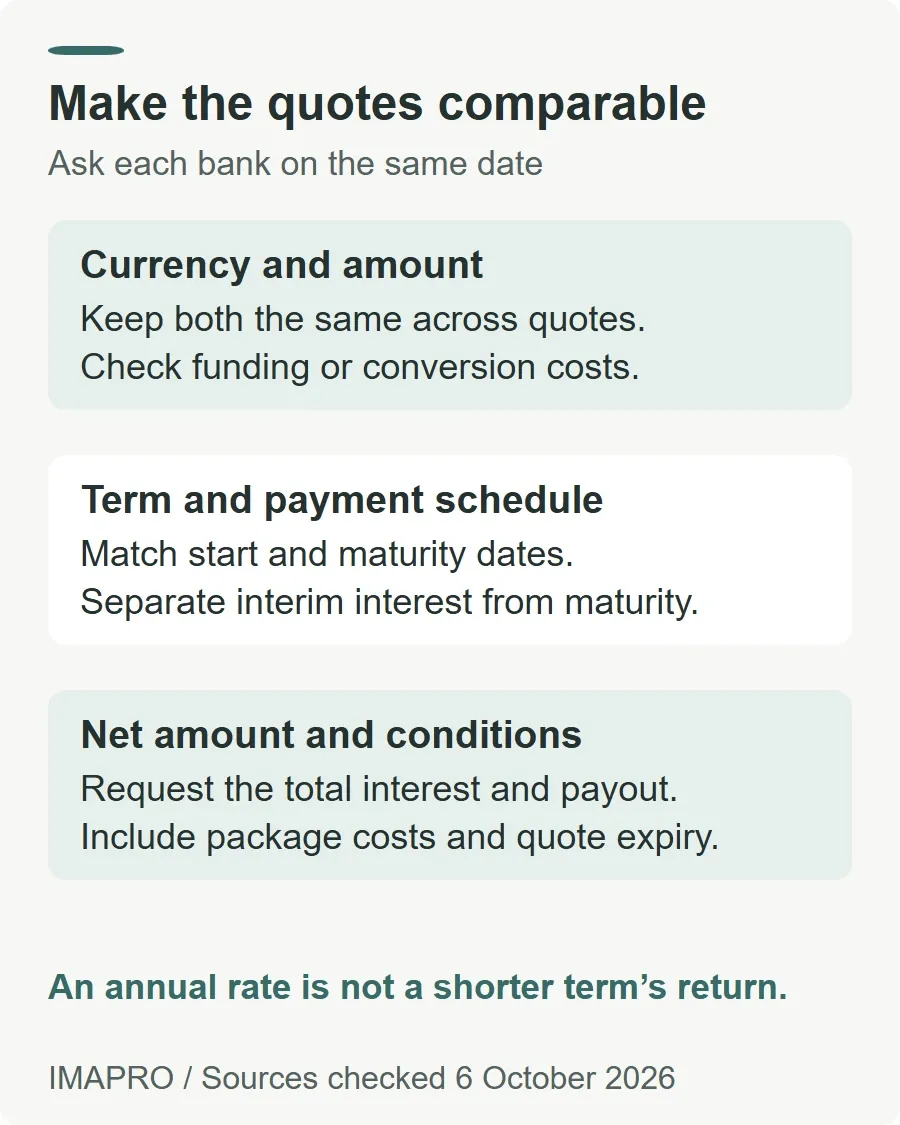
Set these three details before comparing banks. Changing any one of them can change the offer. Also record whether the quote requires a particular account package, because the package cost belongs in the comparison.
| Official product example | Published terms checked | What to confirm before booking |
|---|---|---|
| BBK Fixed Deposit Account | Minimum BHD 3,000 or foreign-currency equivalent; BHD and major foreign currencies; terms from one month to one year. | The rate for your exact amount and currency, maturity payment and early-break treatment. |
| ila Fixed Deposit | The FAQ lists minimums of BHD 500 or USD 1,500 and terms from one month to one year. The product page separates Classic and Premium rate tables. | The app's current offer, account-package cost and whether you selected monthly interest or payment at maturity. |
| NBB Fixed Deposit | The linked contract places the agreed amount, period, rate and selected payment arrangement in the application form. | The completed application and applicable schedule of charges. The contract alone is not a current rate quote. |
Sources: BBK product details, ila fixed-deposit FAQs, ila product and dated rate tables and NBB deposit terms.
Do not assume a foreign-currency deposit produces a better result just because its quoted rate is higher. Ask how funding and repayment conversions would be priced. NBB's repayment clause, for example, applies the bank's prevailing exchange rate and relevant charges when an accepted instruction requires payment in another currency. Compare the final amount in the currency you will actually need.
For account opening, obtain the bank's current document checklist. BBK's published requirements include identification and, for relevant non-Bahraini applicants, residence documentation. If your ID needs attention first, use the Bahrain CPR guide.
Is the return fixed and how is it paid?
A fixed rate and a payment frequency are different contract terms. BBK's official deposit guide describes interest fixed for the booked term and credited at maturity. NBB's linked contract describes monthly, quarterly or semiannual intervals when offered by the bank and selected in the application. Confirm which arrangement your particular offer uses.
There is also a useful detail in ila's public information: its FAQ describes maturity payment, while its product table separately shows one-year options for monthly interest and interest at maturity. Do not rely on the general FAQ alone when choosing that product. Save the payment schedule displayed in your booking confirmation.
Ask for the interest amount in dinars or dollars, as well as the annual percentage. A three-month term does not earn an entire year's quoted percentage. The bank should state its calculation basis, relevant dates and any deductions. If interest is paid out during the term, do not count it again as part of the maturity payment or assume it automatically compounds.
What happens on early withdrawal?
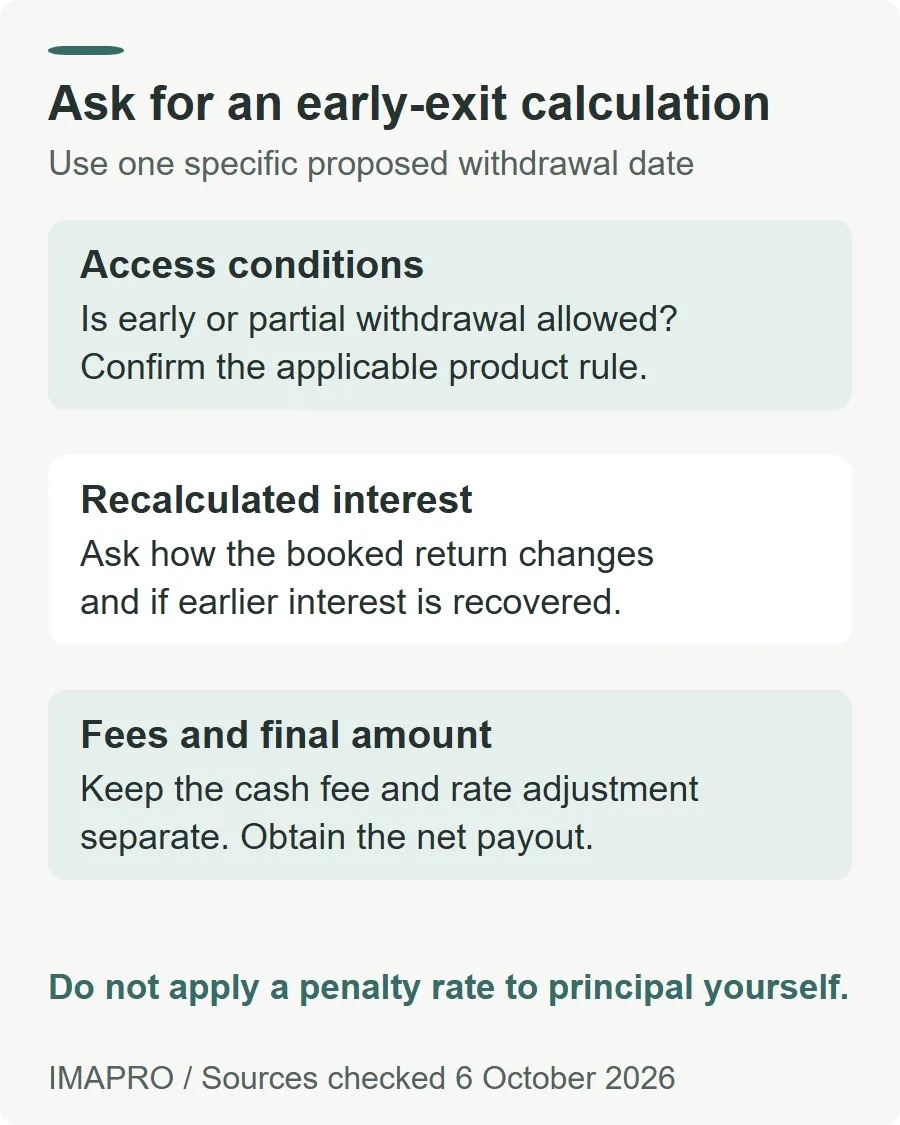
Get an early-exit illustration before committing money that you may need. Ask for the net amount returned on a specific earlier date, with the revised interest and every fee shown separately. Also check whether partial withdrawal is available; ila's current FAQ says it is not.
ila fee example: the linked tariff effective 10 May 2026, checked on 6 October, lists an early-withdrawal fee of BHD 11.000 for BHD deposits or USD 16.50 for USD deposits, including VAT. Both account tiers also show a 0.50% penalty rate. This is a separate rate adjustment, not simply a flat cash fee.
The ila FAQ explains that early-exit interest is recalculated using the completed term and relevant rate at booking, with a penalty deduction. It provides different treatment before the shortest term has been completed. The app shows interest and fees before confirmation. Check that preview against the current tariff rather than applying the penalty to your principal yourself.
NBB contract example: clause 5 allows charges under the tariff and permits the bank to withhold accrued interest, lower the agreed rate to zero or another lower rate, and recover interest previously paid from the deposit. Monthly interest already received therefore does not establish what you will keep if you break the deposit.
Keep the original booking confirmation alongside any early-withdrawal calculation. If the figures differ from what you expected, ask the bank to identify the contract clause and tariff item before proceeding.
Does the deposit renew automatically?
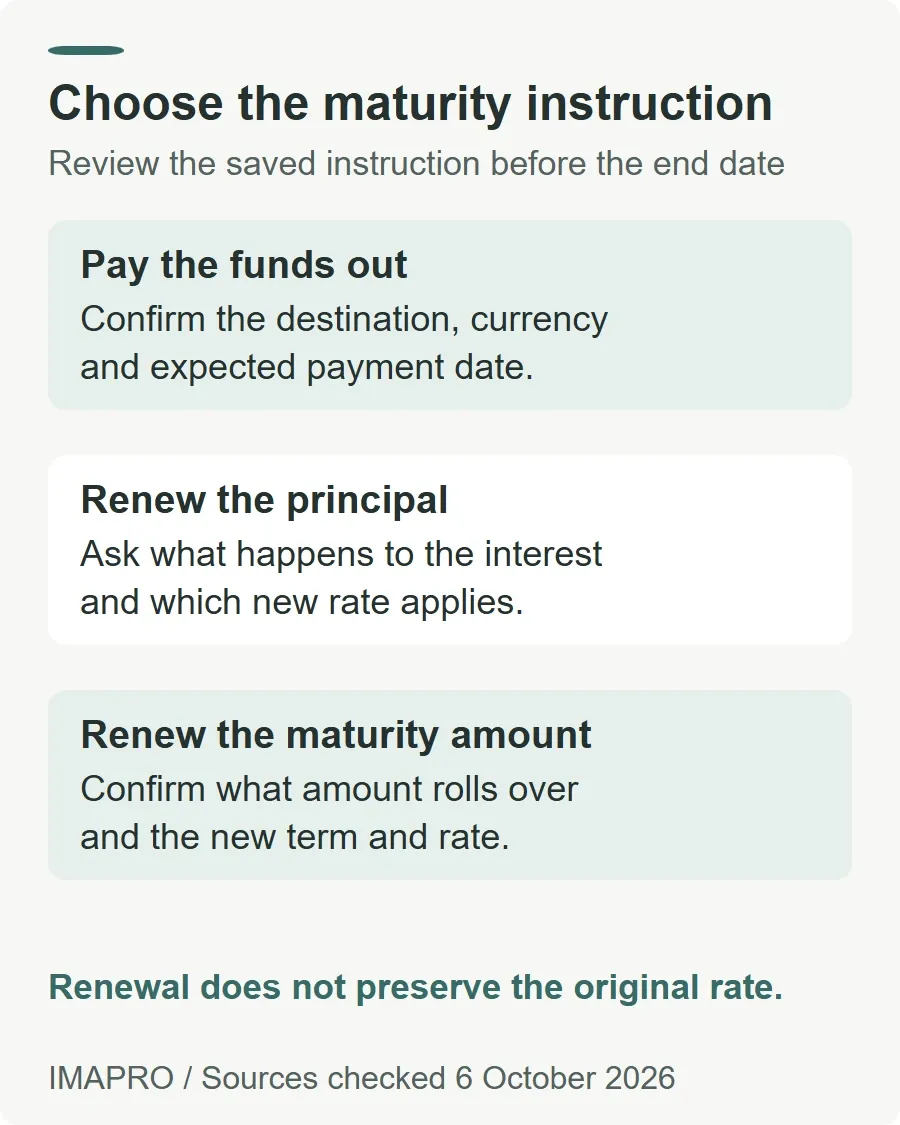
Record your maturity instruction when booking, then review it before the end date. Specify whether you want the money paid out, the principal renewed, or the principal and interest renewed. Do not assume the original rate survives a renewal.
The ila renewal FAQ says automatic renewal uses the rate applicable on the renewal date. Its setting can be changed before maturity and continues until switched off. The available renewal choices are the original deposit amount or the maturity amount.
NBB's clauses 2 and 3 also use the prevailing rate for renewal. Without instructions, the bank may renew for a similar term, but is not obliged to. If maturity falls outside a business day, its terms move maturity to the next business day. Confirm your own bank's timing rather than assuming all products follow that rule.
Which protection rules apply to the exact product?
The CBB's conventional-bank protection rules, CP-2.1 and CP-2.2, cover eligible accounts held by eligible individuals at Bahrain offices of licensed conventional retail banks. Resident and non-resident individuals can qualify. Coverage is subject to exclusions; it is not a promise that every product sold by a bank is protected.
The ceiling is BHD 20,000 across an eligible depositor's eligible accounts at the defaulting bank, regardless of the number of deposits or currencies. Opening several deposits at that bank does not multiply the ceiling. Foreign currencies are converted under the rule's prescribed default-date basis. The Board can set off debts and deduct relevant payout expenses.
Joint accounts have specific treatment and must not be assumed to receive a separate full limit for each named holder. Ask the bank to identify the legal institution holding the deposit and confirm eligibility for the exact account and ownership structure. The CBB consumer overview explains that the scheme has separate conventional and Islamic funds. An investment label or advertised return alone does not establish coverage.
How do you compare written quotes on the same date?
Use one comparison sheet with a row for each bank. Leave a field marked “not confirmed” until the bank answers it; a missing charge is not a zero charge.
- Placement: legal bank name, product, currency, amount, start date and maturity date.
- Return: annual rate, calculation basis, payment dates and total interest amount.
- Costs: account-package charges, funding or conversion costs and withdrawal tariff.
- Access: partial-withdrawal availability and an early-exit calculation for the same date.
- Maturity: payout destination, renewal setting, renewal-rate basis and instruction deadline.
- Protection: account eligibility and how balances at the same legal bank are aggregated.
- Quote validity: when the offer expires and what must happen to secure it.
Save the accepted quote, product terms, tariff and confirmation together. They let you check the actual maturity or withdrawal payment against the agreement, even if a public webpage later changes. More practical account and payment topics are in the Bahrain finance guides.
General information only. This article is not personal financial, investment or legal advice and does not recommend a bank or deposit. Confirm current terms, eligibility and protection with the provider before placing funds.