Official sources checked
Family Health Insurance in Bahrain: Dependants and Cover Checks
By Gaurav Agarwal · Sources checked 6 October 2026
Compare family cover member by member. Confirm who is enrolled, each effective date, the exact network, annual and family limits, copays, chronic-condition terms, maternity and child benefits, approvals and renewal rules. Employer cover for one worker does not by itself prove that every dependant is active.
Jump to a section
01Start with the legal duty and actual enrolment
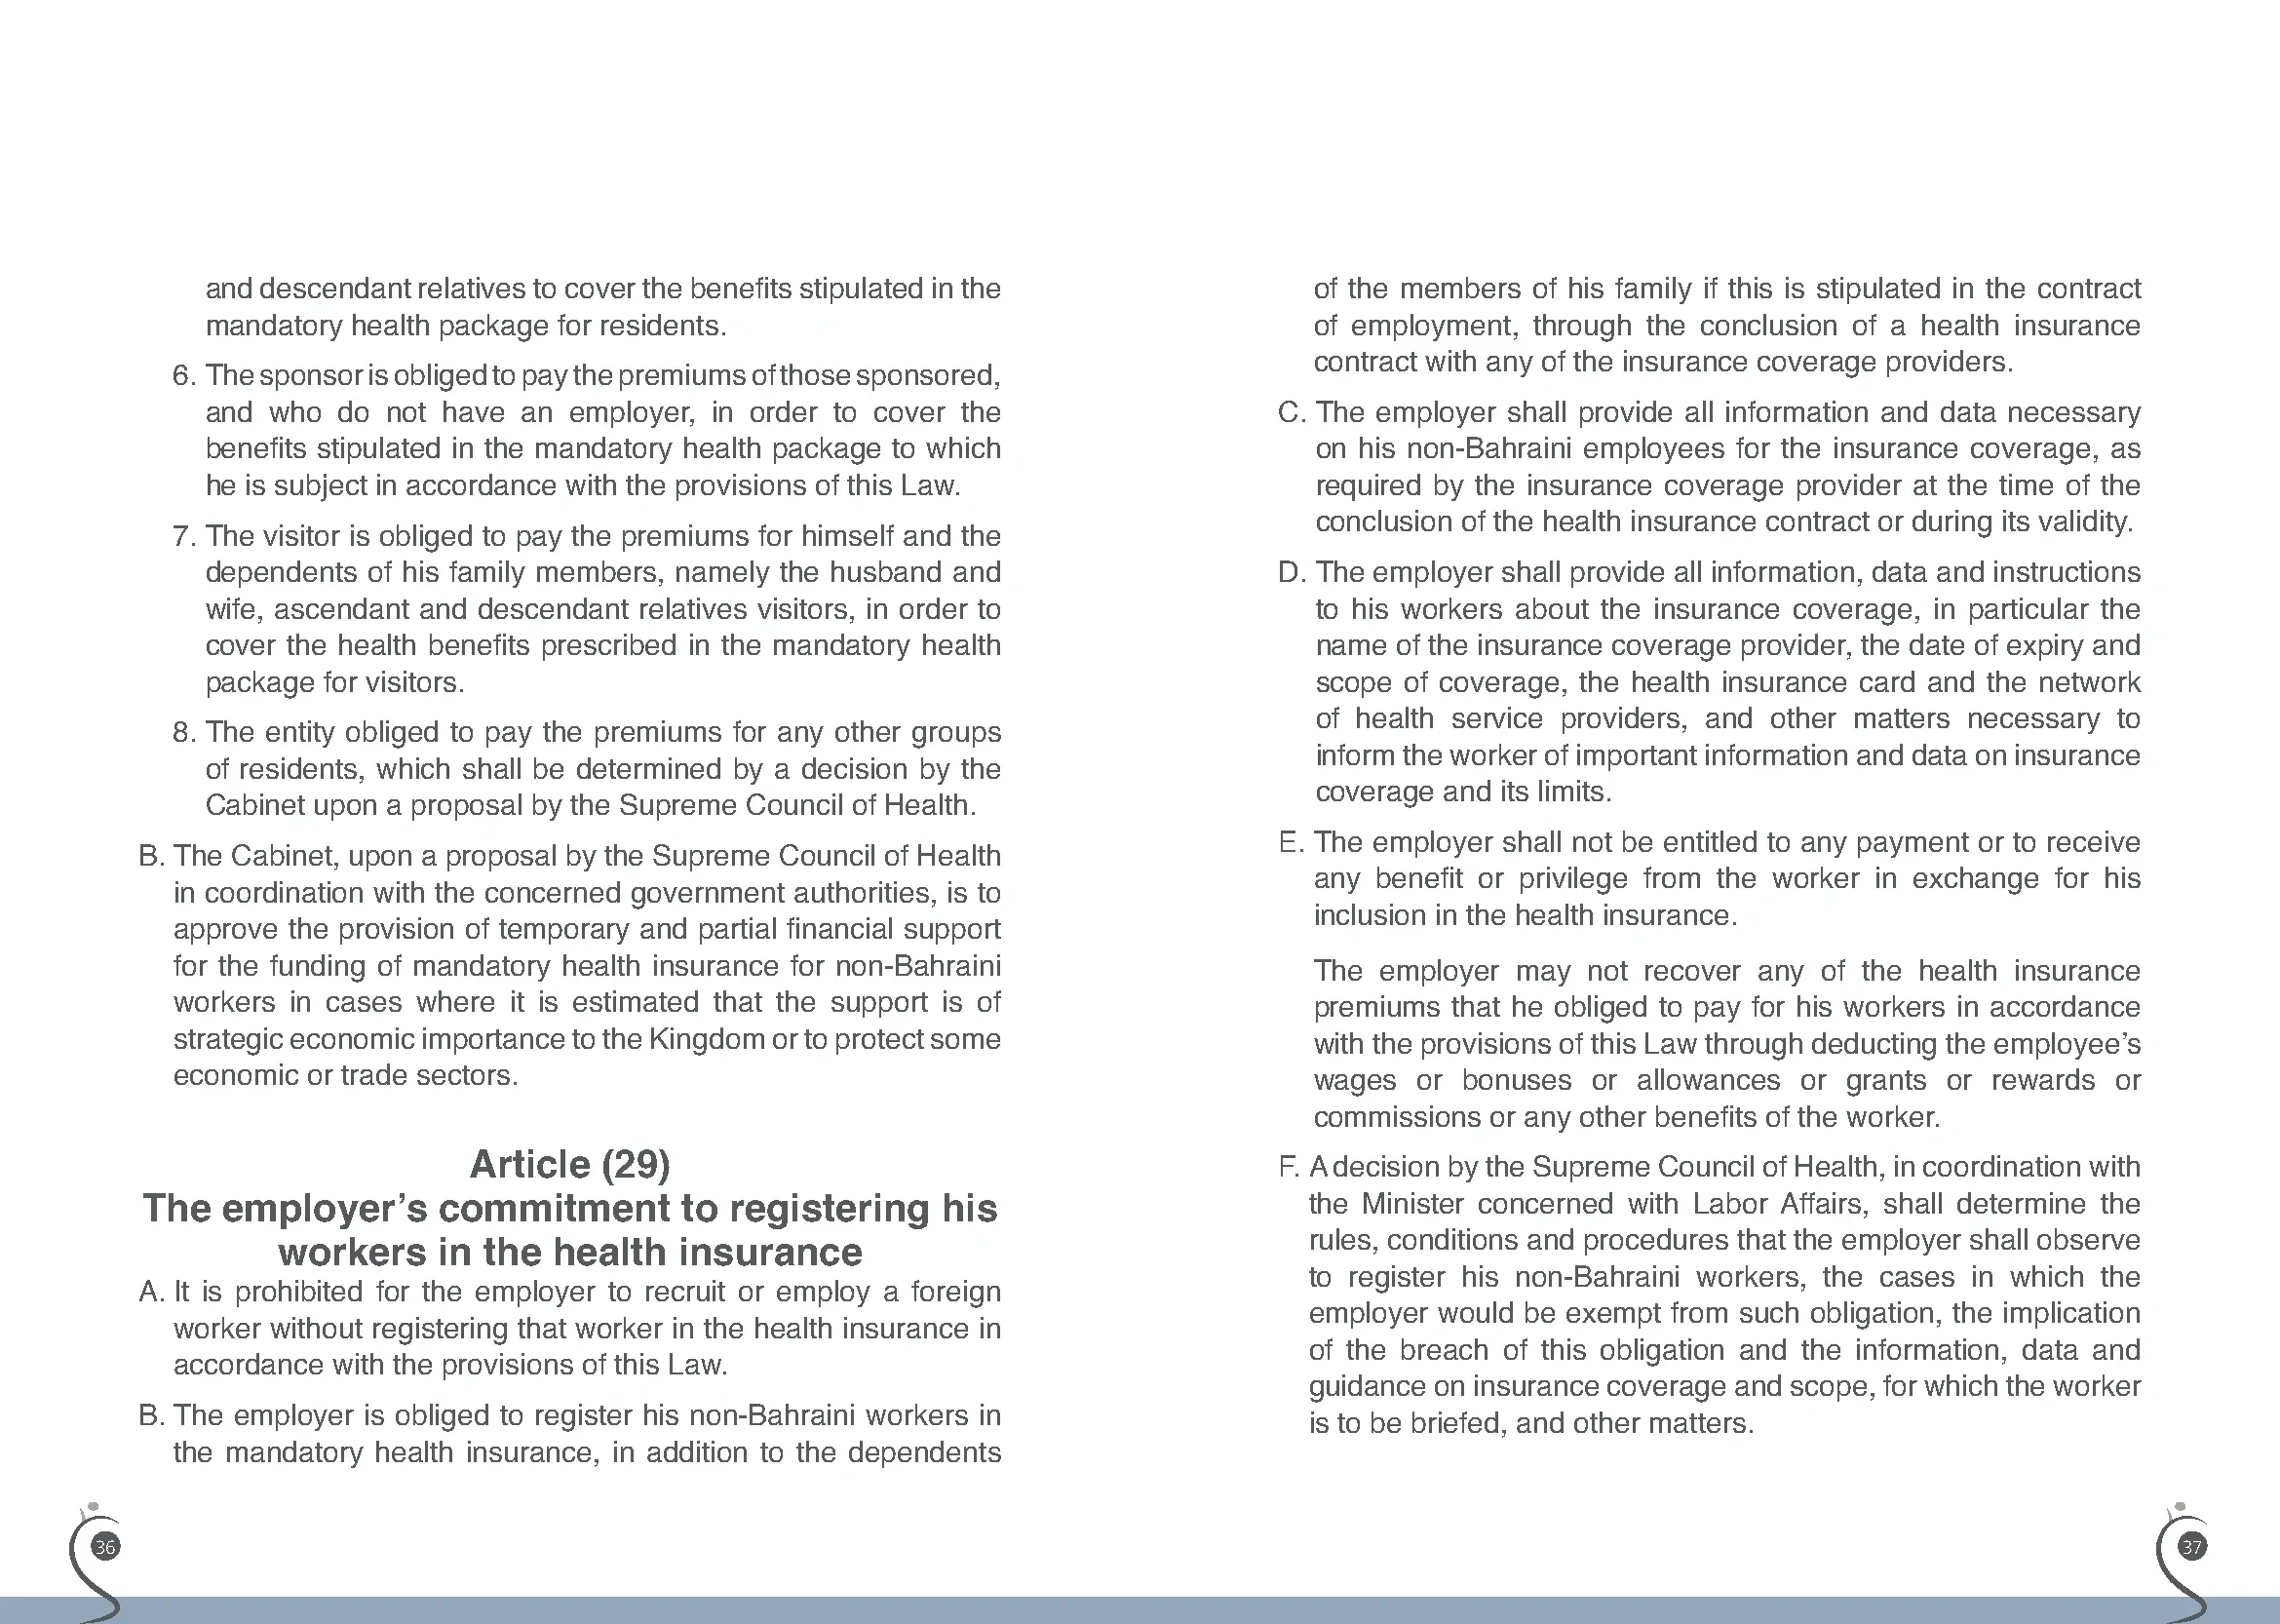
Article 29 of Bahrain's Health Insurance Law addresses contributions for non-Bahraini workers and their dependants. Read the official provision and current information on Sehati. Then verify the actual policy and member record for each adult and child.
Search the legal insurer in the CBB Licensing Directory. Record the plan, administrator, network and effective date. A parent's active card is not evidence that a spouse or child has been added.
For a spouse or child’s immigration application, use the dependent-visa insurance checklist separately from the treatment-benefit comparison.
Use the Sehati law and enrolment guide to separate the legal framework from each person’s policy record.
02A family comparison worksheet
| Row | What to compare |
|---|---|
| Members | Name, age, relationship, effective date and member number. |
| Network | Paediatrician, GP, specialists, hospital, pharmacy and laboratory. |
| Limits | Per-person annual limit, family aggregate and benefit sublimits. |
| Cost sharing | Copay and deductible for visits, medicines, tests and admissions. |
| Children | Vaccines, well-child care, dental, optical and developmental services. |
| Parents | Chronic care, medicines, maternity and mental-health benefits. |
| Geography | Bahrain, GCC and travel or emergency treatment. |
| Renewal | Age limits, premium changes, job changes and continuation. |
03Price the family's likely use
Add the total premium or payroll contribution to expected copays, deductibles, excluded medicines and out-of-network costs. Test realistic events: routine paediatric visits, a specialist consultation, regular medicine, diagnostic imaging and an inpatient admission.
- Request quotes for the same family members and dates.
- Hold the network, annual limit and geography constant.
- Use the same deductible and copay structure.
- Disclose medical history accurately for every member.
- Ask for maternity and newborn terms when relevant.
- Obtain the benefit table, network, schedule and wording.
- Record the quote date and validity.
A lower family premium can be poor value if routine providers are outside the network or separate sublimits are too low for expected care.
The medical-insurance cost comparison helps combine premiums with realistic copays and excluded spending.
04Job change, newborns and claim problems
When employment or sponsorship changes, ask for the exact cover end date and continuation options in writing. For a newborn, check the notification and enrolment deadline before delivery. Do not assume automatic cover continues indefinitely.
For planned treatment, verify network and preauthorisation. Keep approvals, medical reports, itemised invoices, receipts, prescriptions and submitted claim records. If a claim is refused, request the reason and policy clause. Use the insurer complaint process, then the CBB complaint form where appropriate.
05Questions about family health insurance
Are dependants automatically covered by an employer plan?
No assumption is safe. Check the law, current implementation, employer records and the issued enrolment for each dependant.
Does a family policy have one shared limit?
It may use per-member limits, a family aggregate or both. Read the schedule and benefit table.
Can different family members use different networks?
That depends on the plan design. Record the exact network shown for each member.
What happens when a child is born?
Check automatic cover, notification, enrolment, premium and congenital-condition terms before delivery.