Bahrain health insurance
Health Insurance in Bahrain: Expat Rules, Sehati and Plan Comparison
By Gaurav Agarwal · Reviewed 6 October 2026
Bahrain's Health Insurance Law puts the premium for a non-Bahraini employee's mandatory resident package on the employer. Article 29 requires registration and information about the provider, expiry, scope, card and network, and bars recovery of the required premium from the worker's pay. Check dependants separately, then verify the policy's network, co-pay and approval rules before treatment.
01Health insurance, Sehati and the expat medical test are different
| Term | What it is | What it does not prove |
|---|---|---|
| Health or medical insurance | A contract that pays eligible treatment costs through direct billing or reimbursement, subject to its benefits, network, limits and exclusions. | A card alone does not prove that every hospital, medicine or condition is covered. |
| Sehati social health insurance | Bahrain's national health-insurance framework under Law No. 23 of 2018, with citizen, resident and visitor packages and phased implementation. | The name does not replace your current insurer card, benefit table or approval route. |
| Sehati app and portal services | Government digital health services for appointments, medical records and other services. The official portal also presents packages and claims functions. | An appointment or medical record in the app is not the same as a private insurance authorisation. |
| Expatriate medical fitness test | A compulsory public-health examination connected to a work permit, conducted through authorised facilities and the MOH or LMRA process. | Passing the fitness examination does not mean the employee has health-insurance cover. |
Sources: MOH Health Insurance Law, official Sehati portal, MOH Sehati app description, and MOH expatriate check-up guidance.
This distinction prevents two common problems: an employee assumes a completed medical test created insurance, or a patient assumes that a clinic visible in a health directory must be covered by their policy. Use the official process for each job.
Use the expat medical-fitness result guide for the separate examination process; a fitness result is not a health-insurance policy.
02What Bahrain's mandatory health-insurance law says
Law No. 23 of 2018 issuing the Health Insurance Law applies to citizens, residents and visitors, subject to listed exclusions. Article 26 places those groups within the mandatory system. Article 27 provides for coverage through the Health Insurance Fund or authorised insurance companies. Article 28 assigns premium responsibilities, and Article 29 sets the employer's duties for non-Bahraini workers.
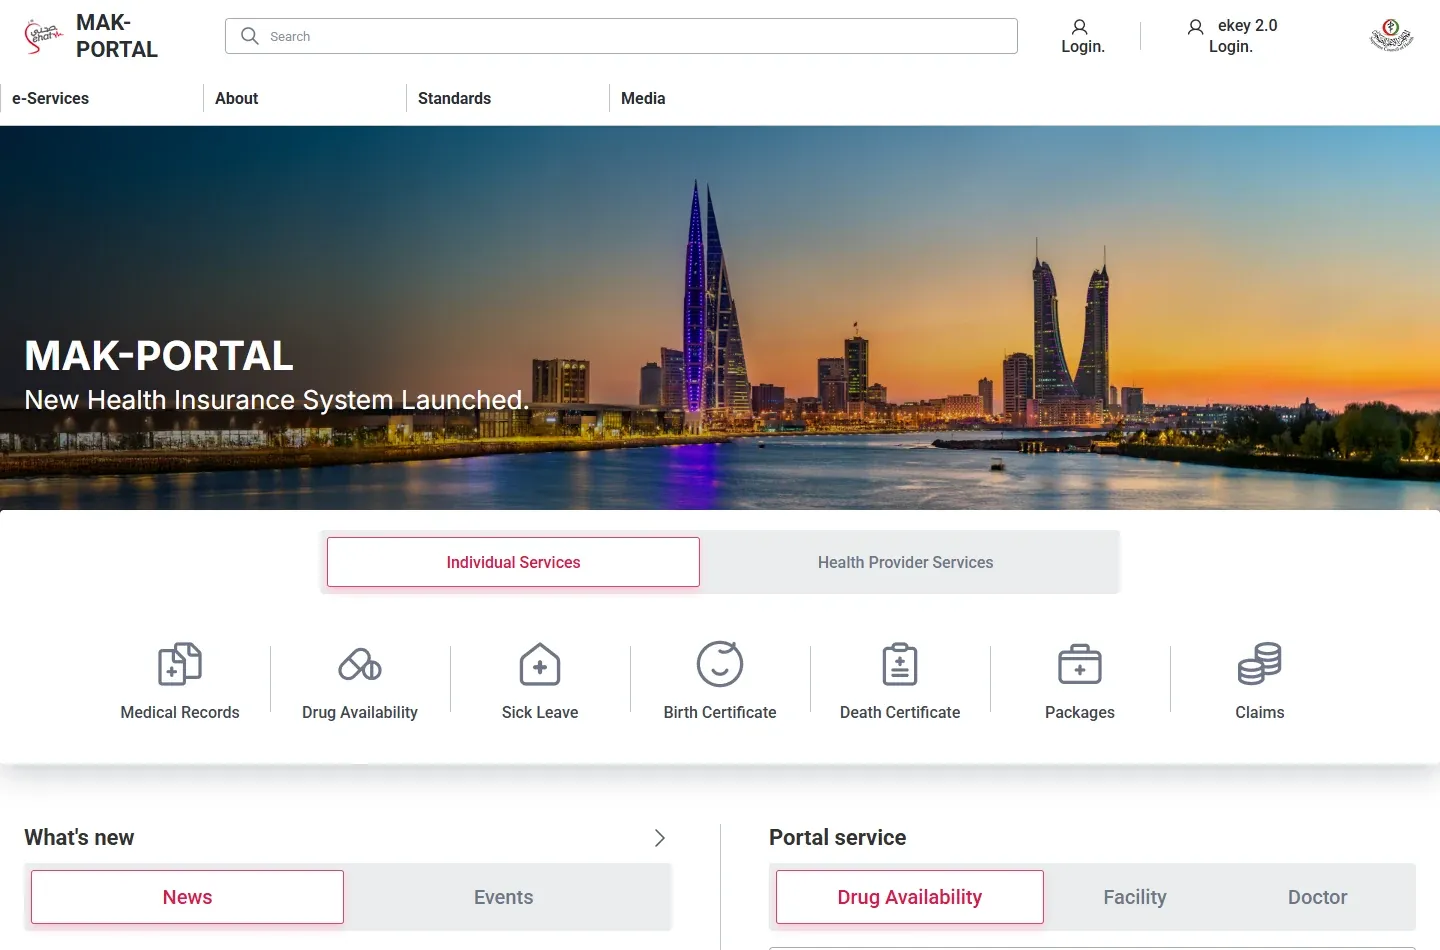
The law also says application occurs in phases by Cabinet decision. That matters when reading older announcements or assuming that every feature has the same rollout date. The current official Sehati portal states that the new health-insurance system has launched. Articles 28 and 29 remain the direct official source for the employer's premium and registration duties.
03Employer duties for an expatriate employee
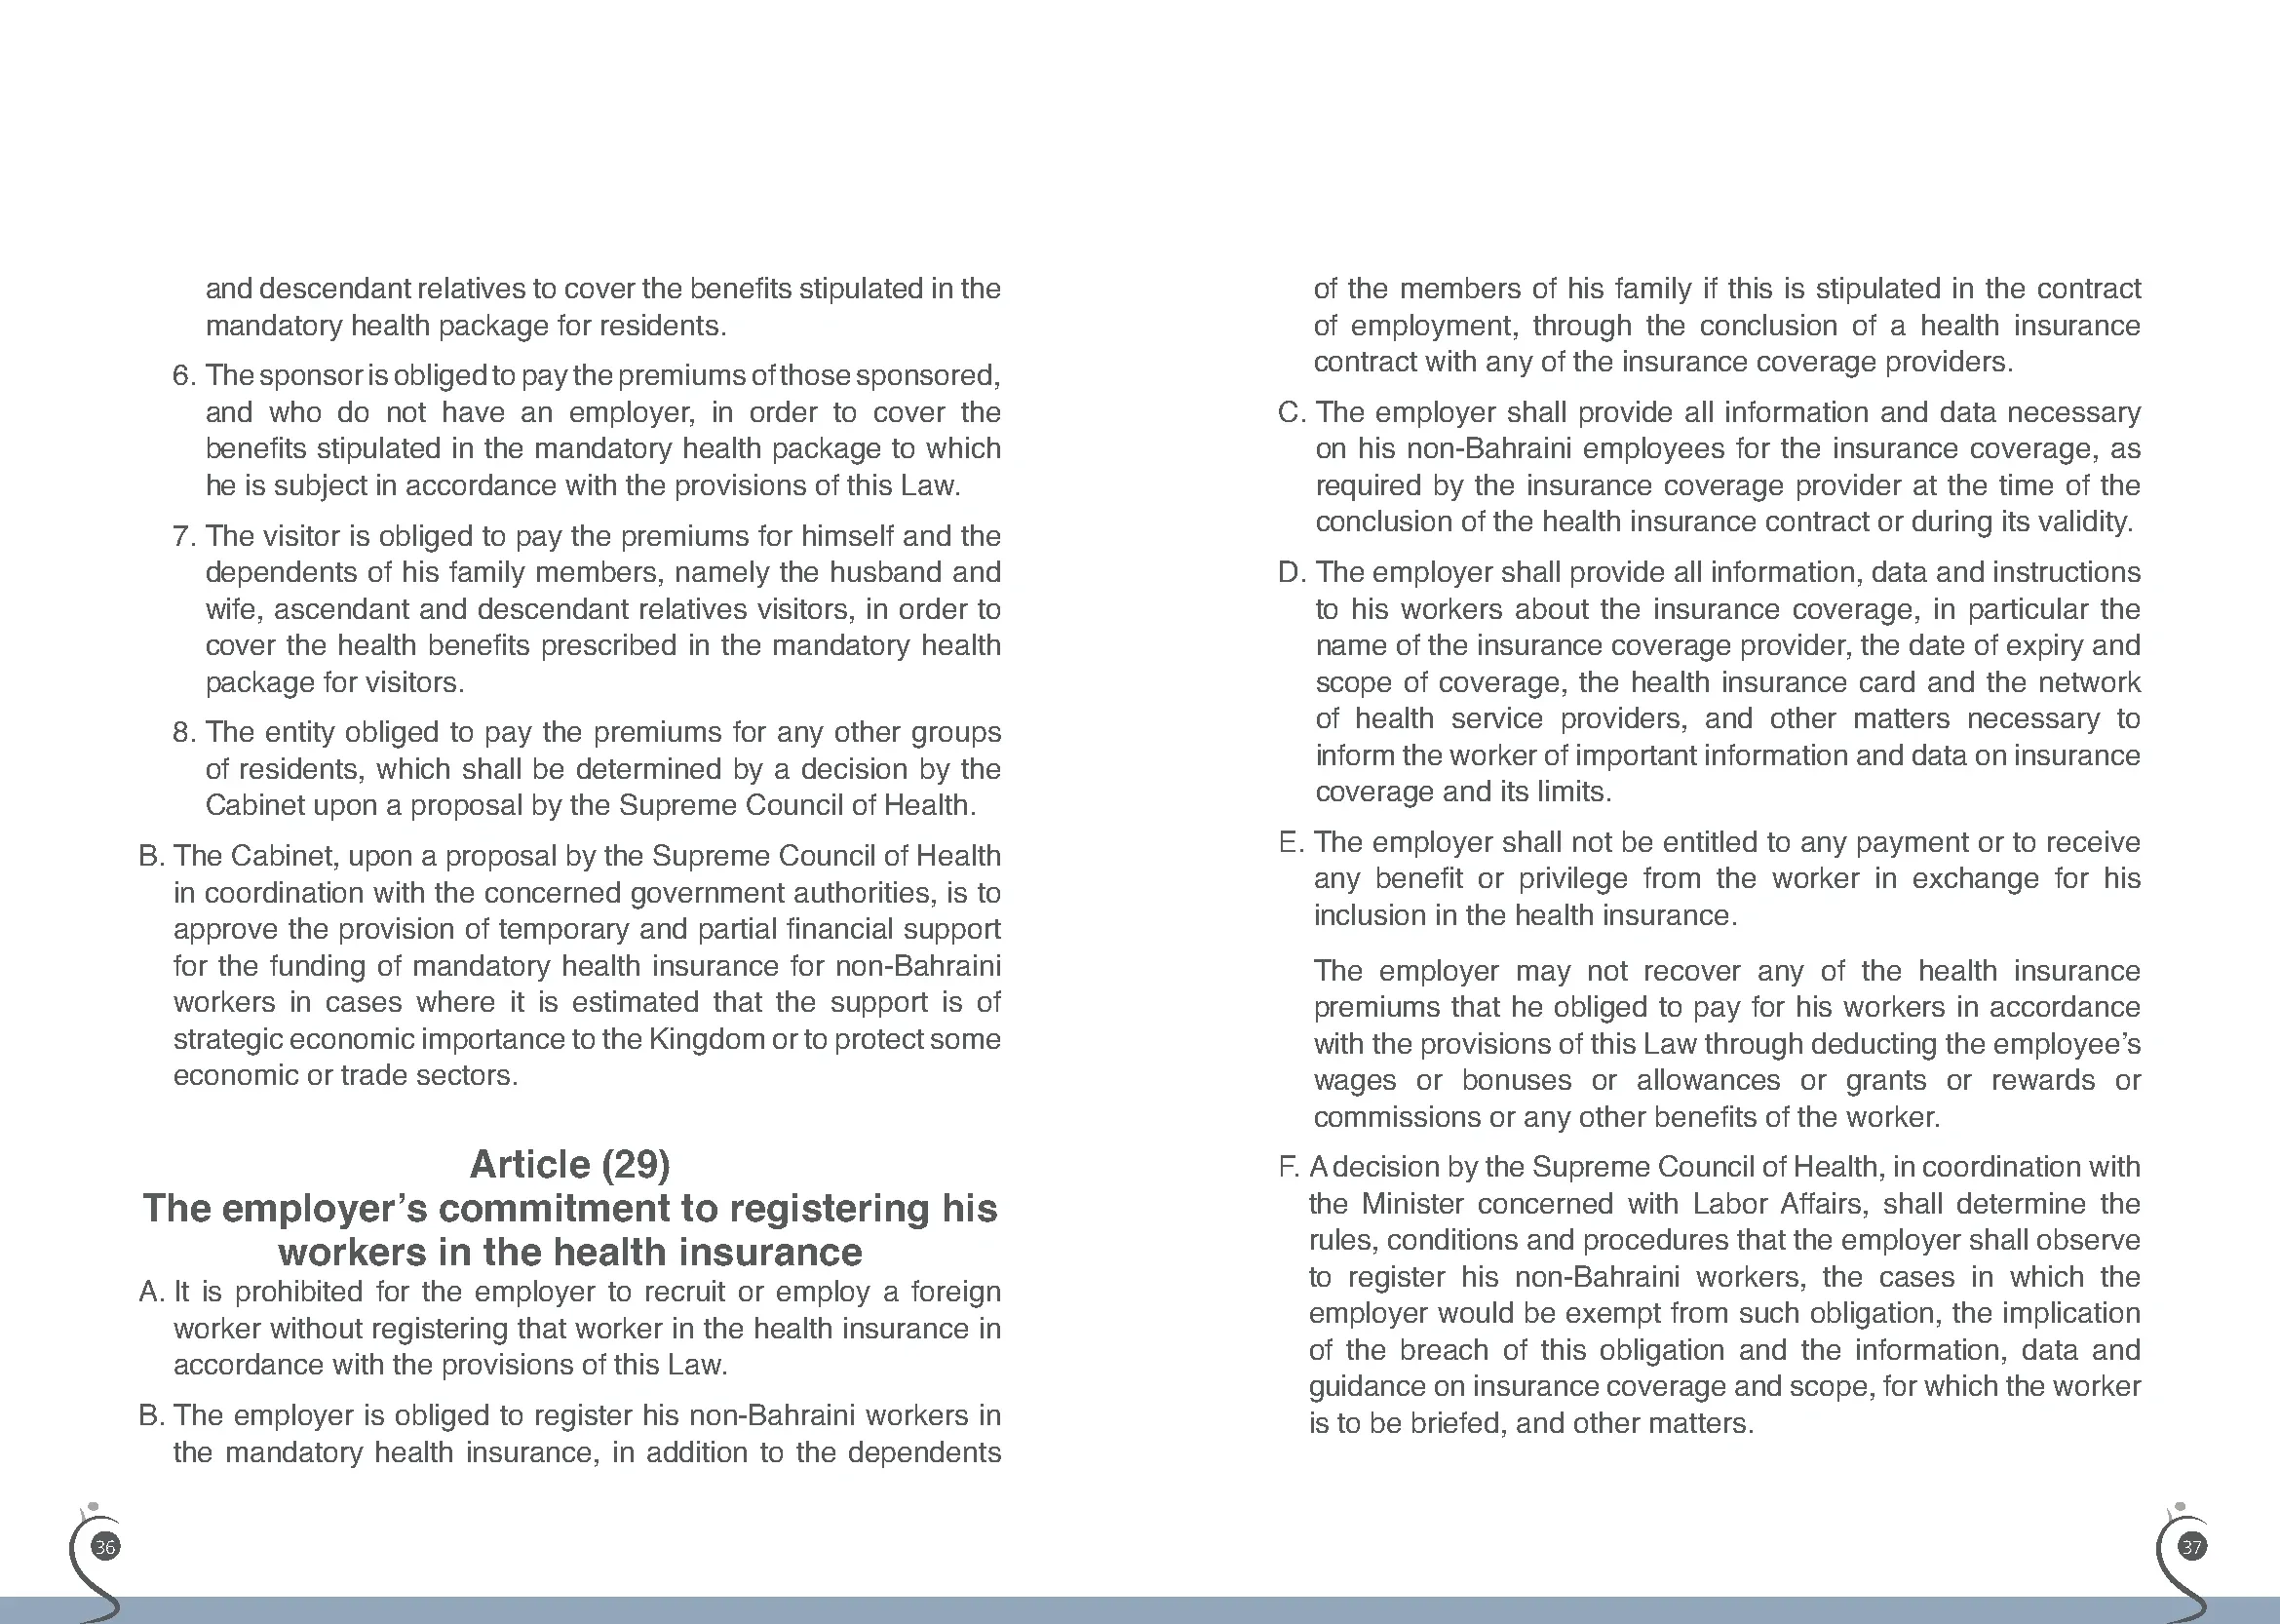
Article 29 of the official law gives the clearest checklist. It prohibits an employer from recruiting or employing a foreign worker without registering that worker in health insurance in accordance with the law. It requires the employer to register non-Bahraini workers in mandatory health insurance through a contract with a coverage provider.
The same article requires the employer to give workers information and instructions about the cover. It specifically names the coverage provider, expiry date, scope of coverage, health-insurance card and network of health-service providers. It also says the employer cannot receive a payment or benefit from the worker in exchange for inclusion and cannot recover the premium it is required to pay by deducting wages, bonuses, allowances, grants, rewards, commissions or other benefits.
Dependants are treated carefully in the text. Article 29 adds family dependants where the employment contract requires their cover. Article 28 separately assigns premium duties to sponsors, non-working residents and certain other groups. An employee should therefore read the employment contract and each dependant's sponsorship position instead of assuming that the employee card automatically covers a spouse or child.
04Who pays the health-insurance premium
| Person | Premium responsibility stated in Article 28 |
|---|---|
| Bahraini citizen and a person treated as a citizen | The government pays for the mandatory citizen package. |
| Non-Bahraini employee | The employer pays for the mandatory resident package. |
| Non-Bahraini employer who is a natural person | The person pays for themselves and resident family dependants listed in the law. |
| Non-working resident | The resident pays for themselves and listed resident family dependants. |
| Licensed worker without an employer | The worker pays for themselves and listed resident family dependants. |
| Sponsored resident without an employer | The sponsor pays for the sponsored person. |
| Visitor | The visitor pays for themselves and listed visiting family dependants. |
Source: Article 28 of the official Bahrain Health Insurance Law. The Cabinet and Supreme Council of Health may issue implementing decisions for categories, support, procedures and phases.
Article 32 adds a practical consequence for employers: where an employer fails to provide valid cover, the employer must pay the value of health-service claims for the worker according to the provider's declared price list. The issued decisions and facts of a case still matter, so a worker facing no cover should preserve the employment contract, payslips, messages and treatment bills and seek advice from the relevant authority.
For a spouse or child’s application, use the dependent-visa insurance checklist without assuming the employee’s policy covers every family member.
05Compare medical insurance by the treatment path
A useful comparison follows what happens when someone needs care. Ask each insurer or employer for the table of benefits and test the same scenario against every plan.
| Comparison row | What to verify in writing |
|---|---|
| Annual maximum | The total policy-year limit and any lower sublimits for a condition or service. |
| Provider network | The exact Bahrain hospitals, clinics, pharmacies, laboratories and diagnostic centres in the selected network. |
| Outpatient care | GP and specialist consultations, referral rules, tests, physiotherapy and medicines. |
| Inpatient and day care | Room class, surgery, intensive care, day procedures and pre-authorisation. |
| Co-pay and deductible | The amount paid by the member per visit, service, prescription or claim. |
| Pre-existing and chronic conditions | Disclosure duty, waiting period, underwriting decision and any annual sublimit. |
| Maternity and newborn | Waiting period, normal and caesarean delivery limits, complications, outpatient pregnancy care and newborn enrolment deadline. |
| Medicines | Formulary, prescription requirement, pharmacy network and approval for high-cost drugs. |
| Dental, optical and mental health | Whether included, optional or excluded and the separate limit. |
| Geography | Bahrain only, GCC, regional or worldwide cover, plus emergency and elective-treatment rules. |
| Direct billing and reimbursement | When the insurer pays the provider, when the member pays first, required documents and the submission deadline. |
GIG Gulf's health FAQ illustrates why these rows matter. It directs members to the table of benefits for maternity, co-pay and deductible details; explains that out-of-network treatment can move to reimbursement at reasonable and customary rates; and tells members to use the policy network and approval process. Those are product examples, not universal Bahrain rules.
Use the health-insurer comparison worksheet to compare the same network, benefits and cost-sharing fields.
06Health-insurance providers and regulatory checks
Use the CBB Licensing Directory to verify the legal insurer. Select Insurance Licensees and search the company name shown on the policy. A broker, employer portal, administrator or hospital network can handle part of the customer journey, but the policy should identify the licensed risk carrier.
| Official public product page | What it shows | Verify before buying |
|---|---|---|
| GIG Gulf Health Perfect | Individual and family plans, networks, selected-condition benefits, claims and policy documents. | The Bahrain table of benefits, plan network, underwriting result and co-pay. |
| Takaful International Afya | Five medical-plan categories, hospital and clinic networks and eligibility up to the stated age. | The chosen category, geographical area, benefits and exclusions. |
| Solidarity business medical insurance | Employer medical cover that may reimburse expenses or pay providers directly. | The employee census, network, benefit schedule and claim administration. |
| Bahrain Kuwait Insurance Moeen | A medical product designed for domestic helpers with published annual benefit examples. | Eligibility, annual limit, sublimits, network and reimbursement procedure. |
Providers and products change. Verify the legal company in the CBB register, then keep the final quote, policy schedule, table of benefits, membership card and wording. The product page is evidence of what was advertised; the issued documents show what applies to the member.
Before comparing plans, verify the licensed insurer that will issue the policy.
07What health insurance costs and the public figures you can verify
There is no official universal Bahrain premium for private individual or employer medical insurance. A real quote depends on age, member count, medical declarations, benefit limits, network, geography, co-pay, deductible and underwriting. Any article that gives one market price without those inputs is mixing different products.
Public insurer pages can still provide verifiable benefit figures. Bahrain Kuwait Insurance's Moeen page, checked 6 October 2026, states outpatient, day-care and emergency services up to BHD 3,000 per year for the described household-staff product and a BHD 500 annual amount for pre-existing and chronic conditions. It also lists a BHD 5 policy-cancellation fee before VAT and other taxes. These numbers describe that product, not the price or limit of standard employee or family insurance.
GIG Gulf's Bahrain health page presents seven Health Perfect plans and states that selected plan benefits differ. It advertises cover for declared pre-existing conditions from day one under its stated terms. The exact limit, network and member cost must be read from the Bahrain quote and table of benefits.
08How to use a health policy without an avoidable bill
- Get the current e-card or physical card. Confirm the member name, number, insurer or administrator and policy dates. GIG Gulf's official member page shows e-cards, benefits, dependants, provider search and claims in its app.
- Open the table of benefits. Find the annual limit, network, co-pay, deductible, waiting periods and service sublimits.
- Search the policy network. A provider's general licence does not prove it belongs to your selected insurance network. Use the insurer's locator or ask the insurer to confirm.
- Check referral and approval rules. Ask whether a specialist, scan, planned admission, surgery, maternity service or high-cost medicine needs a referral or pre-authorisation.
- Show the card and CPR. Let the provider verify eligibility before non-emergency treatment and confirm the member contribution.
- Keep clinical and payment records. Save prescriptions, referrals, approvals, itemised invoices, receipts, reports and discharge summaries.
- Use reimbursement only when the policy permits it. Submit the claim form and documents within the stated deadline. Out-of-network reimbursement may be limited to reasonable and customary charges under the product terms.
The Sehati portal provides government health-system services, while the insurer's member portal manages the private policy. Use the service named on the card when checking a network, approval or claim.
09When a medical claim or approval is denied
Ask for the decision in writing and identify whether the issue is eligibility, an inactive member record, out-of-network treatment, missing referral, missing pre-approval, waiting period, exclusion, sublimit, medical necessity, incomplete documents or a late claim. Request the clause and benefit-table row used.
Build a clean file with the card, schedule, table of benefits, provider invoice, medical report, prescription, referral, approval request, claim form, receipts and all messages. If the employer arranged the cover, ask HR to confirm the enrolment date, member record and policy documents.
Complain to the insurer through its formal channel first. If the dispute concerns a CBB-regulated insurer and remains unresolved, the CBB complaint route asks consumers to complain to the financial institution before escalating. The Imapro CBB insurance-complaint guide shows how to present the timeline, policy clause and requested remedy.
10Health-insurance questions in Bahrain
Is health insurance mandatory for expatriates in Bahrain?
The Health Insurance Law places residents within the mandatory system and assigns the premium for a non-Bahraini employee's resident package to the employer. The law also provides for phased implementation. Check the current member card and employer documents rather than assuming a medical test or work permit proves active insurance. See the official law.
Can an employer deduct the employee's mandatory premium from salary?
Article 29 says the employer may not recover the premium it is obliged to pay by deducting the worker's wages, bonuses, allowances, grants, rewards, commissions or other benefits.
Must the employer cover a spouse and children?
Article 29 links employer registration of family dependants to what the employment contract requires. Article 28 also assigns duties to sponsors and non-working residents. Check the contract, sponsorship and issued member list.
Is Sehati the same as a private health-insurance company?
No. Sehati is Bahrain's social health-insurance framework and also names official digital health services. A private policy is issued by an authorised coverage provider and has its own network, card and benefit table.
Is the expat medical check-up health insurance?
No. The MOH check-up is a work-permit health-fitness requirement. It does not replace a health policy.
What is a co-pay?
It is the member's percentage or amount for an eligible service under the policy. The Health Insurance Law defines coinsurance, and the private table of benefits shows when it applies.
Are pre-existing conditions covered?
It depends on the product, disclosure and underwriting. GIG Gulf advertises selected Health Perfect cover for declared pre-existing conditions from day one under its terms, while BKIC publishes a separate sublimit on its domestic-helper product. Read the issued benefit table.
Can I visit any hospital?
You may be able to receive care, but the payment method can change. In-network treatment may use direct billing. Out-of-network treatment can require payment first and may reimburse only an allowed amount. Confirm the network and approval before planned care.
What should HR give an expatriate employee?
Article 29 identifies the insurer or coverage provider, expiry date, scope, card and provider network as information the employer must give the worker, along with other information needed to understand the cover and limits.