Official sources checked
Life Insurance in Bahrain for Expats: Term Cover, Beneficiaries and Claims
By Gaurav Agarwal · Sources checked 6 October 2026
Choose life cover by the financial gap it must replace, not by a round number or a brand name. List debts, family income needs, education costs and existing savings. Set a cover period, name beneficiaries correctly, disclose medical and lifestyle facts accurately, and verify the Bahrain provider in the CBB Licensing Directory.
Jump to a section
01Verify who issues the policy
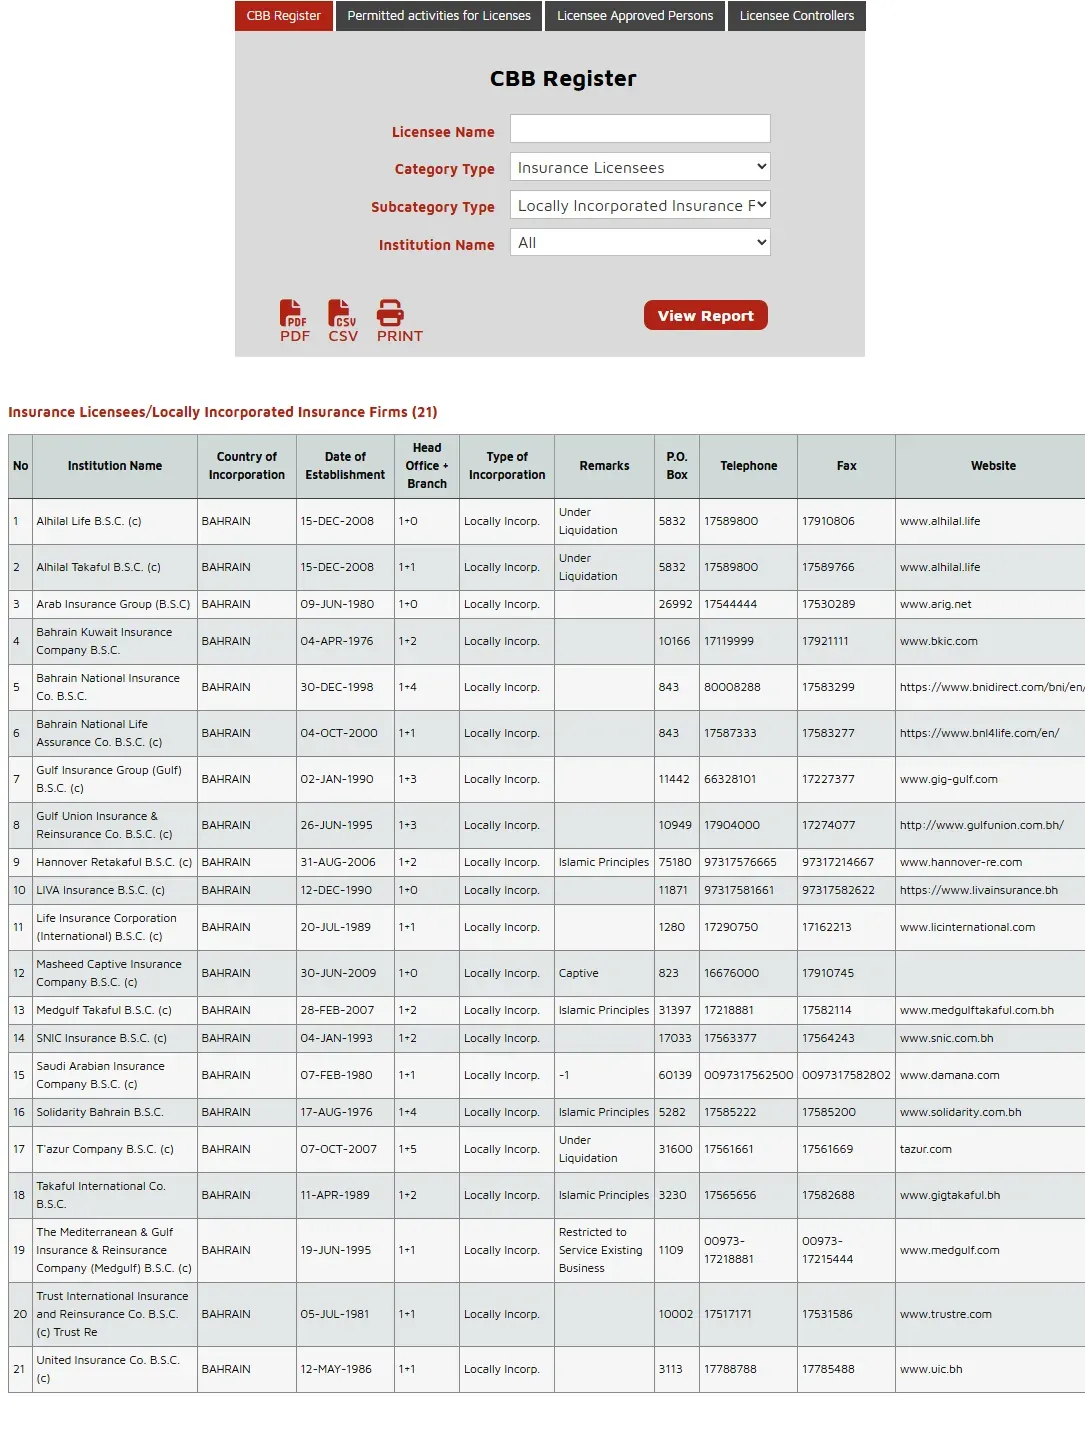
Life cover may be presented by an insurer, bank, broker or online distributor. The policy schedule should identify the legal insurer carrying the risk. Search that exact name in the CBB Licensing Directory, then match the website and contact details to the documents you received.
A distributor can explain or arrange a product, but the insurer named in the contract decides underwriting and claims under the wording. Keep the proposal, benefit illustration if supplied, schedule, wording, endorsements and payment receipts together.
02Term cover, savings products and loan cover solve different needs
| Type | Main purpose | Questions to ask |
|---|---|---|
| Term life | Pays the stated benefit if the insured person dies during the cover period, subject to the policy. | How long is the term? Is the premium fixed? What exclusions and disclosure rules apply? |
| Loan-linked cover | Protects a stated loan balance or lender interest. | Does the benefit reduce with the debt? Who receives payment first? What happens after refinancing? |
| Whole-life or savings-linked cover | Combines protection with longer-term value or investment features. | Which values are guaranteed, which are illustrative, and what are the charges and surrender terms? |
| Employer group life | Workplace benefit under an employer policy. | What is the benefit, who is enrolled, and when does cover end after employment? |
Do not compare these products by premium alone. A lower premium may reflect a shorter term, lower benefit, narrower eligibility or different guarantees.
03Calculate the protection gap and record ownership
- Add outstanding debts and final expenses.
- Estimate the income dependants would need and for how many years.
- Add planned education or care costs.
- Subtract savings and existing life benefits that would be available to the family.
- Choose a term that covers the main dependency period.
- Check who owns the policy, who is insured and who is named as beneficiary.
The Solidarity coverage calculator is one provider tool for testing assumptions. Treat any result as a starting point and compare it with the exact issued terms.
Beneficiary details need regular review
Record the beneficiary name and identifying details exactly as the insurer requires. Ask how a beneficiary change is made, whether a nomination can be revoked, and what happens if a beneficiary dies first. Review the nomination after marriage, divorce, a new child or another major family change. For estate or inheritance questions, obtain qualified legal advice rather than assuming a nomination decides every issue.
04Disclosure, exclusions and a future claim
Answer health, occupation, smoking, travel and hazardous-activity questions completely and accurately. If an answer changes before the policy starts, tell the insurer in writing. Ask for confirmation that underwriting is complete and note any special exclusion, premium loading or postponed decision.
Common claim records can include the claim form, policy details, death certificate, medical evidence, identification, beneficiary evidence and bank details. Requirements depend on the event and policy. The claimant should contact the insurer promptly, request the document list and keep copies and a claim reference.
Use the rejected-claim review guide to compare a refusal with the insurer’s stated clause and evidence.
05Questions about life insurance in Bahrain
Can an expat buy life insurance in Bahrain?
Eligibility depends on the provider, residency, age, health, occupation and product. Verify the issuing insurer and request a written quote based on your actual circumstances.
How much life cover do I need?
Use the protection-gap method: debts plus family needs and planned costs, less resources already available. Record the assumptions and review them when family or financial circumstances change.
Is employer life cover enough?
Check the benefit amount, beneficiary process and the date cover ends. A workplace benefit can leave a gap if it is small or stops with employment.
Can I cancel a savings-linked policy early?
Ask for the surrender terms, charges and current value before deciding. Guaranteed and illustrated values are different.
07Build the cover amount from obligations, not a sales target
Start with debts, the period dependants need support, education commitments, final expenses and assets already available. Then subtract existing life cover that will remain valid. This creates a documented protection gap without assuming a universal multiple of salary.
| Need | Evidence | Review question |
|---|---|---|
| Mortgage or finance | Current balance and linked cover | Does a lender policy reduce over time? |
| Family income | Household budget and support period | Which costs continue after death? |
| Education | Current commitments | Should the amount be held separately? |
| Emergency and final expenses | Family plan | Who can access money immediately? |
| Existing assets | Savings and investments | Are they liquid and available to beneficiaries? |
The Solidarity coverage calculator is one provider tool. Treat its result as an input rather than an independent recommendation. Verify the issuing company in the CBB directory.
08Term insurance, savings-linked cover and family takaful
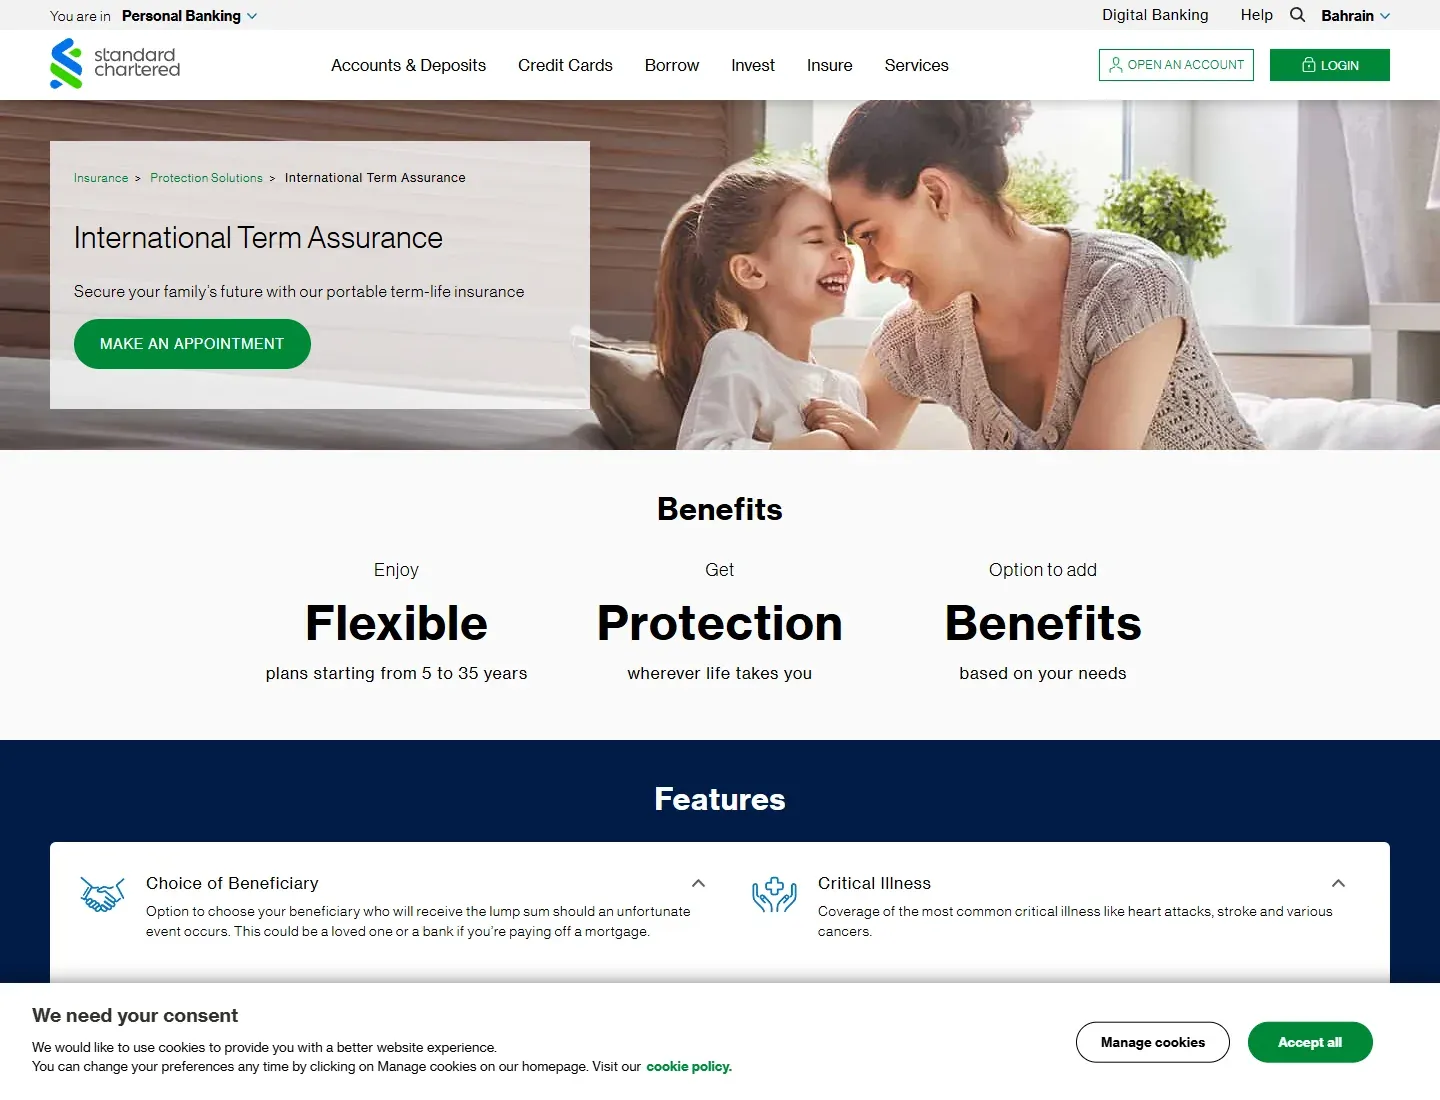
The Standard Chartered Bahrain term-assurance page describes portable term cover distributed through the bank. Takaful International's family-takaful page presents a Sharia-compliant structure. These are different product routes, and neither public page replaces the proposal, illustration and policy wording supplied to the applicant.
| Product route | Main purpose | Questions before signing |
|---|---|---|
| Level term | Protection for a fixed period | Are premium and benefit level for the full term? |
| Decreasing term | Cover that can track a falling debt | Does the reduction match the finance balance? |
| Savings-linked policy | Protection combined with investment or savings | What are charges, surrender values and projected versus guaranteed amounts? |
| Family takaful | Protection using a takaful structure | How are contributions, benefits and any account values described? |
09Design the policy so a future claim can be made
Worked example: an expatriate buys term cover while employed in Bahrain and later moves to another country. Before moving, the customer asks whether the policy is portable, how premiums can be paid, whether occupation or residence changes must be declared, and whether beneficiaries overseas can submit a claim. The answers are saved with the policy.
- Use full legal names and current contact details for the owner, insured person and beneficiaries.
- Answer health, occupation, smoking and travel questions completely.
- Store the schedule, wording, application copy and payment evidence securely.
- Tell beneficiaries that cover exists and how to contact the insurer.
- Review nominations after marriage, divorce, birth, death or a move.
- Ask the insurer how Bahrain succession rules and the policy nomination interact in the specific case.
For a disputed decision, request the clause, underwriting record and reason in writing. Follow the insurer's complaint process, then the CBB route when its conditions are met.
Can an expatriate keep Bahrain life insurance after leaving?
It depends on the policy. Ask about portability, permitted residence and payment before moving.
Is credit life enough for a family?
Credit life is normally designed around a debt. Calculate the separate family-income gap.
Are illustrations guaranteed?
Separate guaranteed values from projected or non-guaranteed values in the illustration.
Who receives the claim?
Check the beneficiary wording, ownership and applicable legal process with the insurer.
10Check the underwriting decision and illustration
After the application, the insurer may accept standard terms, charge a higher premium, exclude a condition, reduce a benefit or ask for more evidence. Do not rely on the original quote after underwriting. Request the final terms and decide whether the changed policy still solves the protection need.
| Final document | What to confirm |
|---|---|
| Schedule | Insured person, benefit, term and premium |
| Endorsement | Any exclusion, loading or special condition |
| Illustration | Guaranteed and non-guaranteed values shown separately |
| Payment mandate | Frequency, currency and failed-payment consequences |
| Cancellation terms | Cooling-off rights and surrender impact where relevant |
Keep the insurer's acceptance notice with the application copy. If a future claim dispute concerns disclosure, these records show the questions asked and the answers supplied.