Official sources checked
Insurance Brokers in Bahrain: How to Verify and Compare Them
By Gaurav Agarwal · Sources checked 6 October 2026
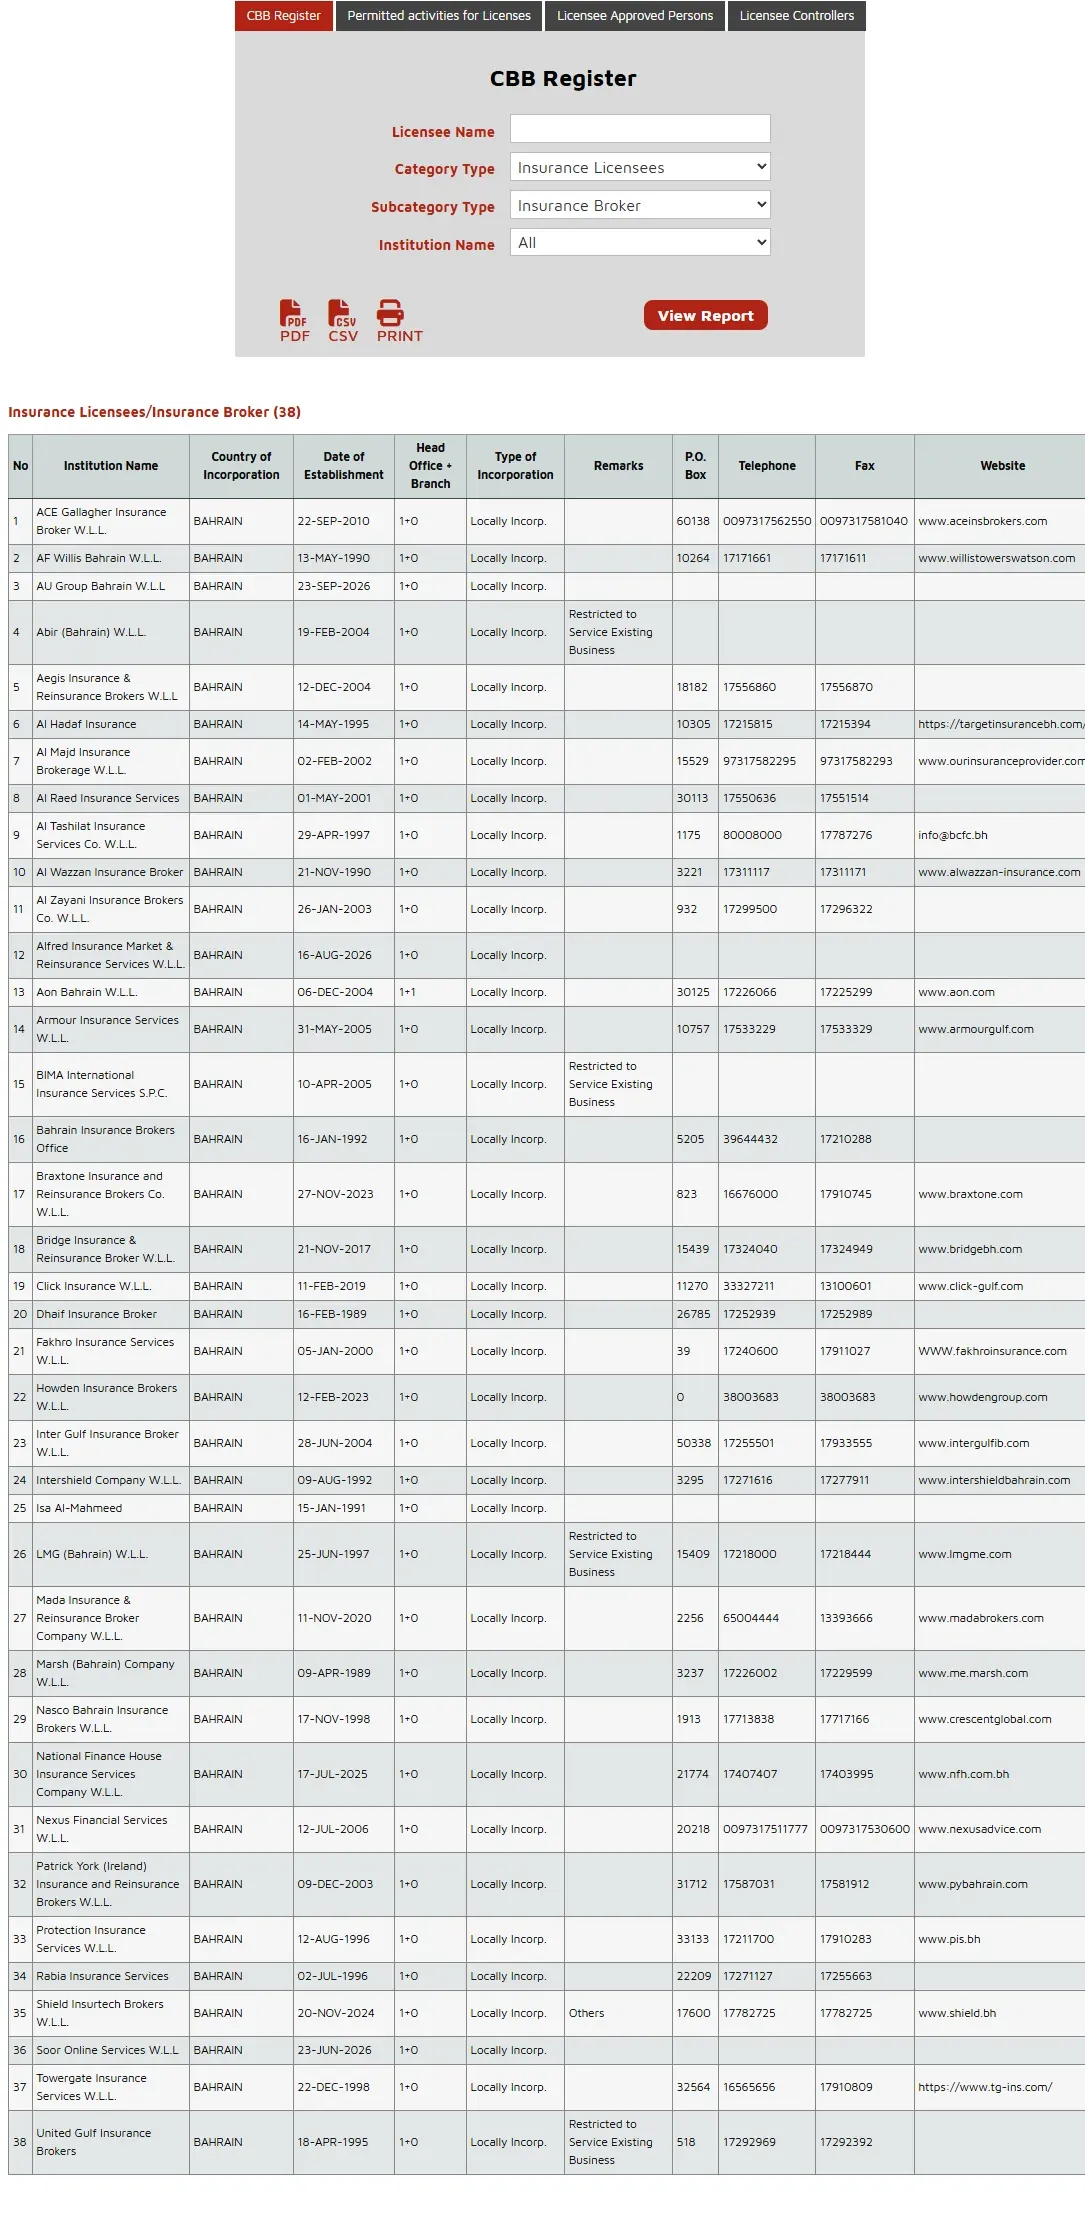
A broker can arrange cover, but the policy must identify the licensed insurer carrying the risk. The CBB Licensing Directory returned 38 entries in the Insurance Broker subcategory when checked on 6 October 2026. Verify the broker and the insurer separately, then compare the broker's provider panel, fee disclosure, documents and service after purchase.
01Insurer, broker, comparison portal and administrator are different
| Role | What it may do | What to verify |
|---|---|---|
| Insurer | Issues the policy and carries the insured risk. | Legal name, CBB category, product and policy wording. |
| Insurance broker | Arranges or advises on cover from one or more insurers. | Broker licence, participating insurers, remuneration and service scope. |
| Comparison portal | Displays quotes or routes a buyer to a broker or insurer. | Licensed entity behind the site, quote panel, data use and payment recipient. |
| Administrator | May manage a health network, approvals or claims. | Insurer named on the policy and administrator named on the card. |
| Loss adjuster | Assesses a loss for a claim. | Appointment, scope and insurer claim reference. |
The CBB directory places brokers, insurers, managers and loss adjusters in separate subcategories. A familiar brand or useful app does not replace the legal role shown in the contract.
02How to verify a Bahrain insurance broker
- Open the CBB Licensing Directory.
- Select Insurance Licensees, then Insurance Broker.
- Search the exact legal name from the website footer, quote or payment page.
- Match the CBB website field to the domain you are using.
- Read any register remark and confirm the firm can perform the current service.
- On the quote, identify the separate insurer that will issue the policy.
- Verify that insurer in the appropriate CBB insurance-firm category.
03Compare brokers and portals on the same rows
| Question | Evidence to request |
|---|---|
| How broad is the panel? | Names of insurers actually quoted for this product and risk. |
| Is advice independent? | Explanation of recommendation, ownership links and panel limits. |
| What will I pay? | Premium, taxes, broker fee and optional add-ons shown separately. |
| Who receives payment? | Legal payee and a receipt matching the transaction. |
| What documents will I receive? | Quote, schedule, wording, certificate, endorsements and receipt. |
| What happens after purchase? | Endorsement, renewal, cancellation and claim-support channels. |
| How are complaints handled? | Formal broker complaint route and insurer complaint route. |
A portal with three insurers can still be useful, but it is not a whole-market comparison. Ask which insurers were eligible, which returned a quote and why others were absent.
04Trace every quote to the risk carrier
The quote should identify the insurer, insured person or business, risk, period, limits, excess or deductible, major conditions and total premium. For motor cover, compare repair basis and territorial extension. For health cover, compare network, annual limit, copay and preauthorisation. For travel cover, compare territory, dates, medical limit and evidence rules.
Open Imapro's licensed-insurer directory to check similar company names. If the broker brand appears more prominently than the insurer, locate the policy issuer before paying.
05Fees, commission and add-ons
Ask the broker to show the total amount due and identify any broker fee, instalment cost or optional service. If the broker says its service is free to the buyer, ask how it is paid and whether that affects the provider panel. Keep the written answer with the quote.
Do not accept preselected add-ons without reviewing them. Roadside assistance, replacement vehicle, travel extras or administrative services may have their own provider, conditions and cancellation terms.
Use the full-cost insurance comparison to keep premiums, fees and accepted excess separate.
06Who helps with a claim or complaint?
A broker may help transmit a claim, but the insurer decides the claim under the policy. Ask whether the broker provides claim support, what evidence it needs and whether you can also track the claim directly with the insurer.
For a service complaint about the broker, use the broker's formal channel. For a coverage or claim dispute, complain to the insurer as well. If the regulated firm's final response does not resolve the matter, use the CBB complaint form with the earlier complaint and evidence. The Imapro complaint guide explains the record to keep.
07Questions about insurance brokers in Bahrain
How many insurance brokers are listed in Bahrain?
The CBB register returned 38 Insurance Broker entries on 6 October 2026. The count can change, so check the live directory.
Is a broker the same as an insurer?
No. CBB uses separate licence categories. The policy should name the insurer carrying the risk.
Does a comparison portal show every insurer?
Do not assume so. Ask for the actual panel and which insurers returned a quote for your risk.
Can I complain about a broker?
Use its formal complaint route first, keep the response and use the CBB form if escalation is needed.
09Compare the broker's panel before comparing its prices
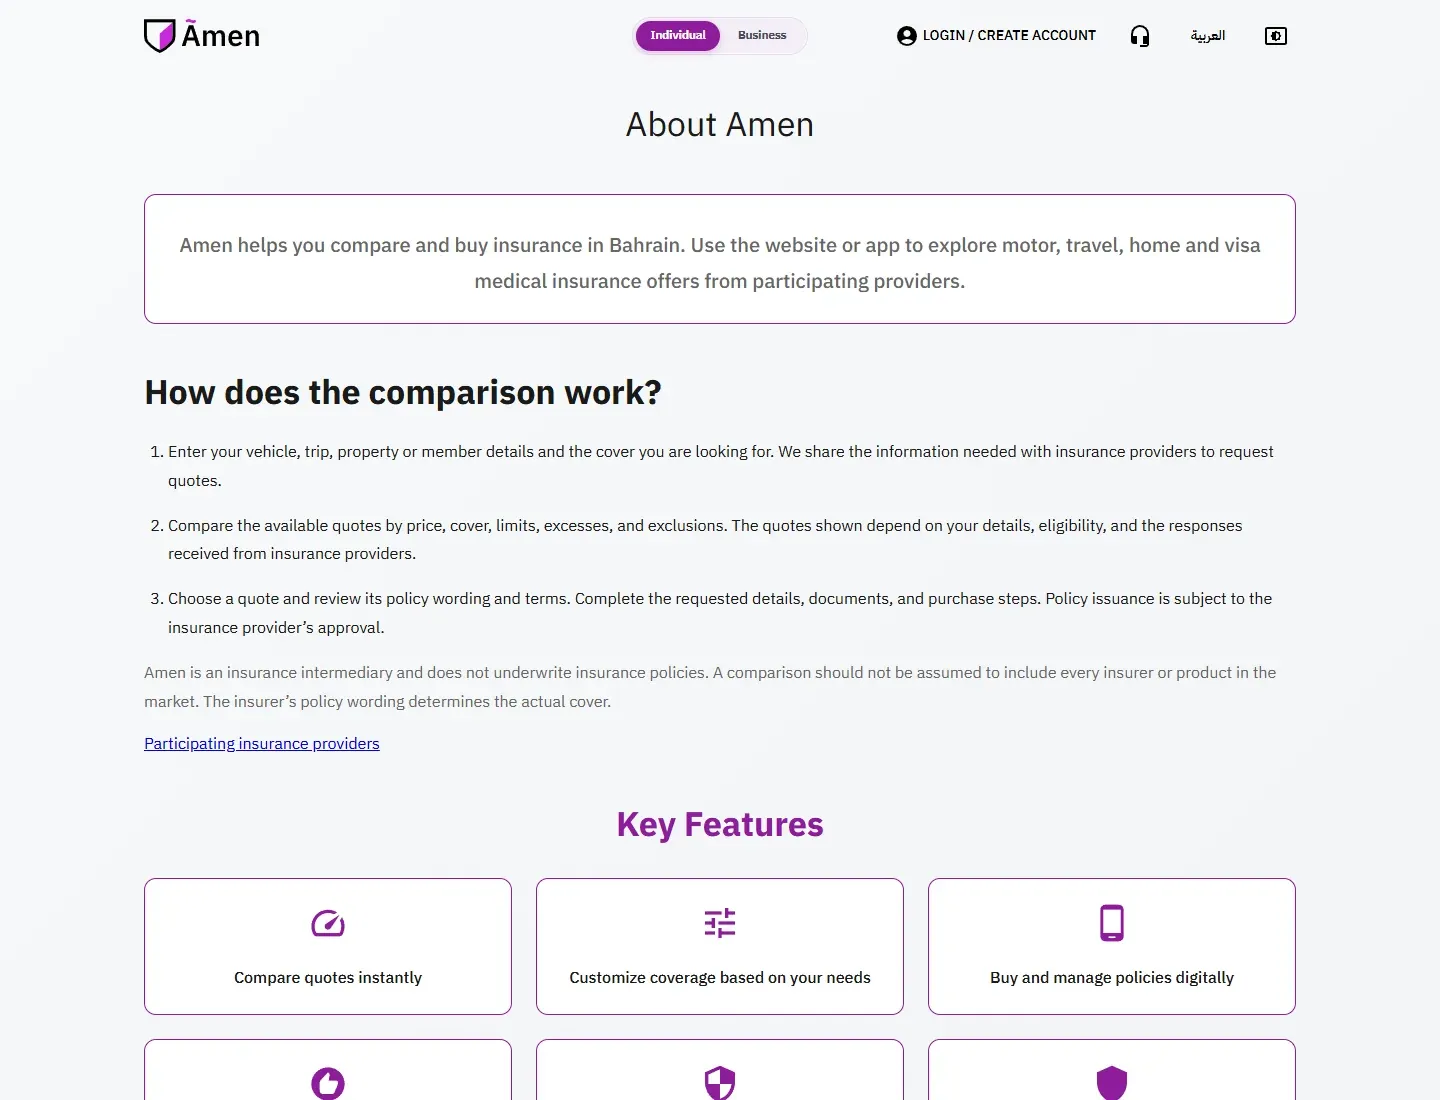
A comparison screen only compares the insurers connected to that broker or aggregator at that moment. Amen's official about page identifies Shield Insurtech Brokers as the operator of its platform. Shield's official site describes its regulated intermediary role. These disclosures help identify the seller, but the final policy must still name the insurer carrying the risk.
| Question | Why it matters | Evidence to keep |
|---|---|---|
| How many insurers were searched? | A small panel can miss a suitable quote | Results screen and partner list |
| Did every quote use the same inputs? | Different excesses or benefits make prices incomparable | Quote summaries |
| Who is the risk carrier? | The insurer, not the portal brand, pays an eligible claim | Proposal and schedule |
| Who handles changes and claims? | Service may stay with the broker or move to the insurer | Terms and contact details |
| Are fees or add-ons included? | The checkout total can differ from the base premium | Itemised receipt |
10Worked example: two broker quotes that look cheaper
Hypothetical example: a customer receives Quote A from an aggregator and Quote B from a traditional broker. Quote A has the lower premium but a higher own-damage excess and omits agency repair. Quote B has a higher premium, a lower excess and a written agency-repair endorsement. Neither is automatically better.
- Copy each insurer's legal name from the proposal.
- Verify the insurer and intermediary separately in the CBB Licensing Directory.
- Normalise the cover type, vehicle value, excess, repair basis, territory and add-ons.
- Ask whether the broker fee is included in the displayed total.
- Read the cancellation, amendment and claim-assistance terms.
- Choose after comparing the likely out-of-pocket cost and service route, not the headline premium.
The websites of Bridge Insurance & Reinsurance Brokers and Howden Bahrain illustrate advisory broker models, while digital aggregators emphasise instant comparison. The relevant distinction is the service promised in writing and the insurers included in the panel.
11What to ask a broker to put in writing
| Topic | Written answer to request |
|---|---|
| Market search | Which insurers were approached and which declined |
| Recommendation | Why the selected policy fits the stated need |
| Remuneration | Broker fee, commission disclosure where applicable, and add-on charges |
| Claims | Whether the broker only forwards documents or actively follows the claim |
| Renewal | Who sends reminders and whether the market will be re-quoted |
| Data | Which insurers receive personal, vehicle, medical or business information |
The CBB insurance rulebook material distinguishes aggregator activity from additional broker services such as handling claims. Do not assume a platform will negotiate a claim unless its terms promise that service and the relevant approval applies.
Does a broker always find the whole Bahrain market?
No. Ask which licensed insurers were included in the search.
Can a broker reject my claim?
The insurer named on the policy makes the coverage decision. A broker may help transmit evidence or explain the response.
Should I pay the broker or the insurer?
Follow only verified written payment instructions and keep an itemised receipt identifying the policy and payee.
Where do I complain?
Complain first to the regulated firm responsible for the issue, then use the CBB route when its conditions are met.