Official sources checked
Professional Indemnity Insurance in Bahrain: What Businesses Should Check
By Gaurav Agarwal · Sources checked 6 October 2026
Professional indemnity insurance responds to defined claims arising from professional services, subject to the policy. Before comparing price, match the insured entity and services, claims-made trigger, retroactive date, limit, defence costs, deductible, territory, exclusions and notification duties to your contracts and risk.
Jump to a section
01Verify the insurer and any regulatory requirement
Verify the legal insurer in the CBB Licensing Directory. A broker can arrange the cover, but the schedule should identify the insurer carrying the risk.
Do not assume every profession has the same statutory or contractual requirement. Check the rule of the regulator, licensing body, tender or client contract that applies to the specific business. Obtain qualified legal or regulatory advice when the requirement affects licensing.
02The timeline matters as much as the limit
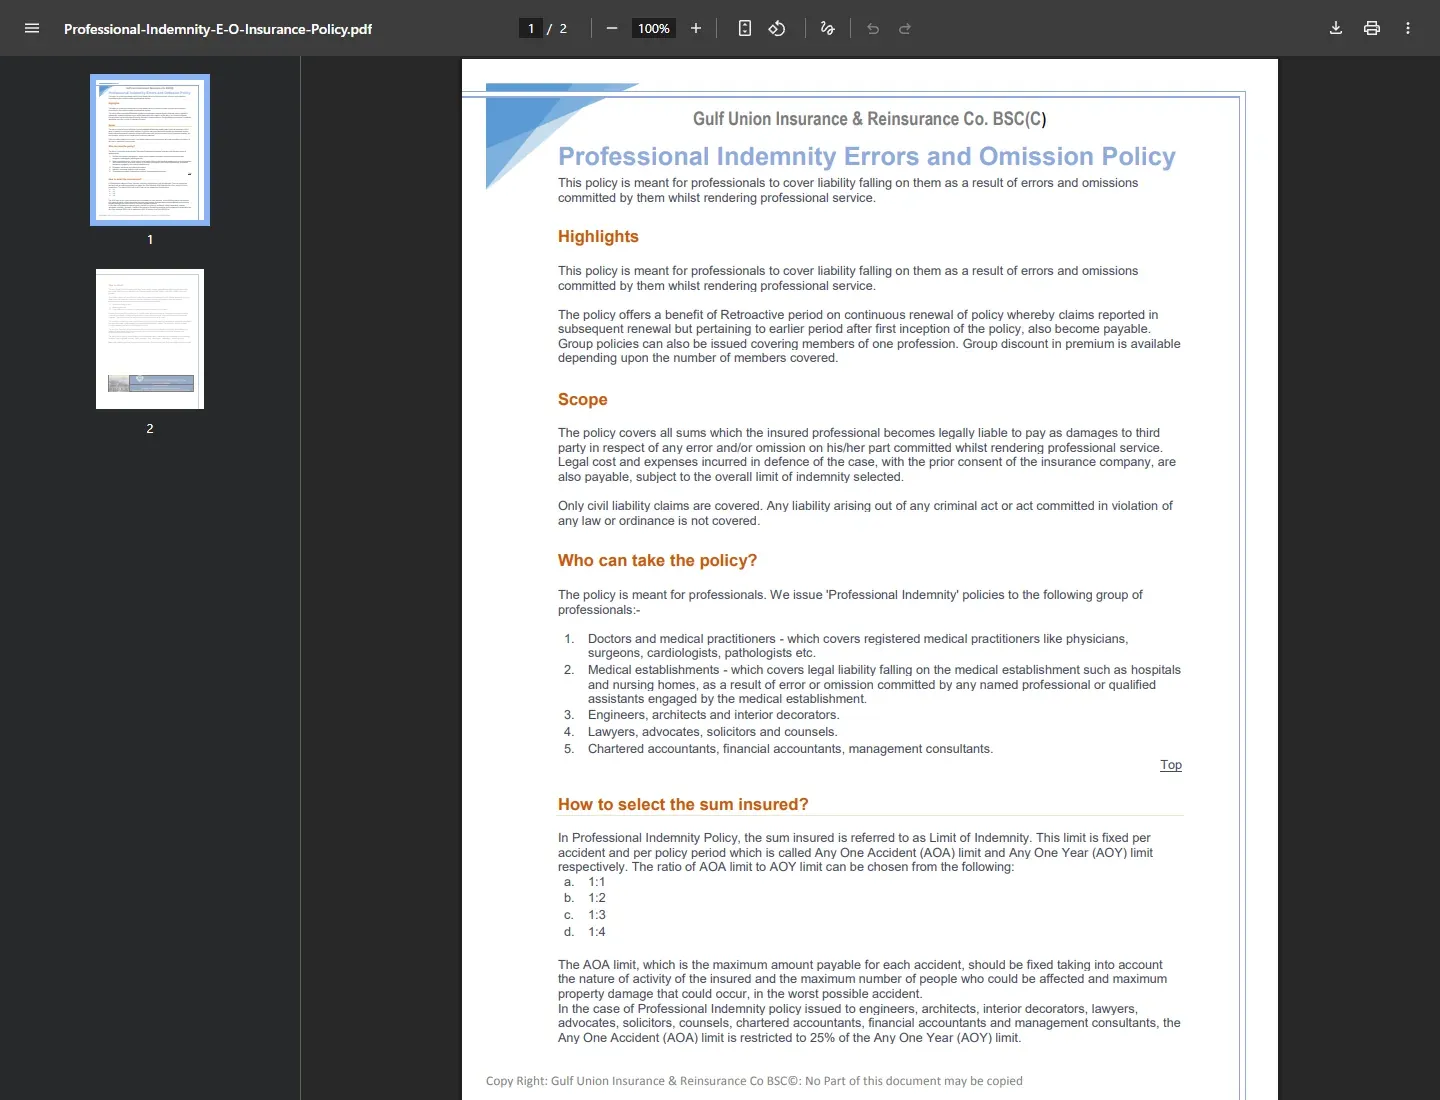
The Gulf Union professional indemnity document describes a retroactive-period benefit on continuous renewal and states that the event must fall within the policy or retroactive period while the claim is first made in writing during the policy period. That is a provider example, not a universal wording.
| Term | Question to ask |
|---|---|
| Insured services | Does the description cover every service, entity and territory? |
| Claims-made trigger | When must the claim be made and reported? |
| Retroactive date | How far back can the act or omission occur? |
| Limit | Is it per claim, annual aggregate or both? |
| Defence costs | Are they inside or outside the limit, and is consent required? |
| Deductible | What does the business pay for damages and defence? |
| Territory and jurisdiction | Where may work be done and claims brought? |
| Run-off cover | What happens after closure, sale or retirement? |
03Prepare a consistent proposal for quotations
- List every legal entity and professional service.
- Break down revenue by service and territory.
- Describe the largest contracts and client types.
- Provide staff qualifications and quality controls.
- Disclose prior claims and circumstances accurately.
- State the required limit, deductible and retroactive date.
- Attach contract terms that create material liabilities.
- Ask for the schedule, wording and endorsements.
The Arabia Insurance Bahrain property and casualty page describes professional indemnity for legal liability from negligence, error or omission during professional activity. Its broad summary does not replace the issued definitions and exclusions.
04Notify circumstances before they become claims
The Gulf Union document says the insurer should be informed immediately of an event likely to give rise to a liability claim and should receive legal notices or summonses. Other wordings may define notification differently, so follow the actual policy.
Do not admit liability, settle, appoint counsel or incur defence costs without checking the consent provisions. Preserve contracts, scope changes, advice, emails, files, invoices and the chronology. At renewal, disclose known circumstances and confirm continuity of the retroactive date.
If a claim or complaint is disputed, request the written decision and clauses. Use the insurer complaint process, then the CBB complaint form where appropriate.
If a claim is refused, use the rejected insurance claim review to identify the exact decision, clause and evidence.
05Questions about professional indemnity
Is professional indemnity mandatory for every Bahrain business?
No universal requirement is established here. Check the regulator, licence, tender and client contract for the specific profession.
What is a claims-made policy?
It ties cover to when a claim is made and reported, subject to the wording and retroactive date. Read the exact trigger.
Are defence costs included?
The schedule and wording decide whether defence costs are covered and whether they reduce the limit.
Why preserve the retroactive date?
Changing it can affect whether earlier work falls within the insured timeline. Confirm continuity at renewal.