Bahrain finance guides
Send money from Bahrain to India: compare the rupees received
By Gaurav Agarwal · Sources checked 6 October 2026
To compare a transfer from Bahrain to India, ask each provider how many rupees the recipient will receive for the same total amount paid in Bahraini dinars. Check the fee, receiving method, delivery conditions and identification requirements before accepting a quote.
Jump to a section
- 1. Choose how the money will reach India
- Match the transfer purpose and account to the Indian receiving route
- 2. Compare total BHD paid with net INR received
- 3. Treat a reference rate as a comparison point
- 4. Prepare identification and recipient details
- 5. Check delivery conditions and save the reference
- 6. Handle a delay, error or cancellation promptly
- Before you pay
- Frequently asked questions
To send money from Bahrain to India, compare the INR the recipient will receive for the same total BHD payment. Confirm the receiving method, complete identity checks, review the final quote and save the transfer reference. A low transfer fee alone does not tell you which service delivers more rupees.
Checked: 6 October 2026. This guide compares the information to request, rather than declaring a cheapest provider. No live transaction quote was obtained, and the examples below do not promise an exchange rate, fee or delivery time.
1. Choose how the money will reach India
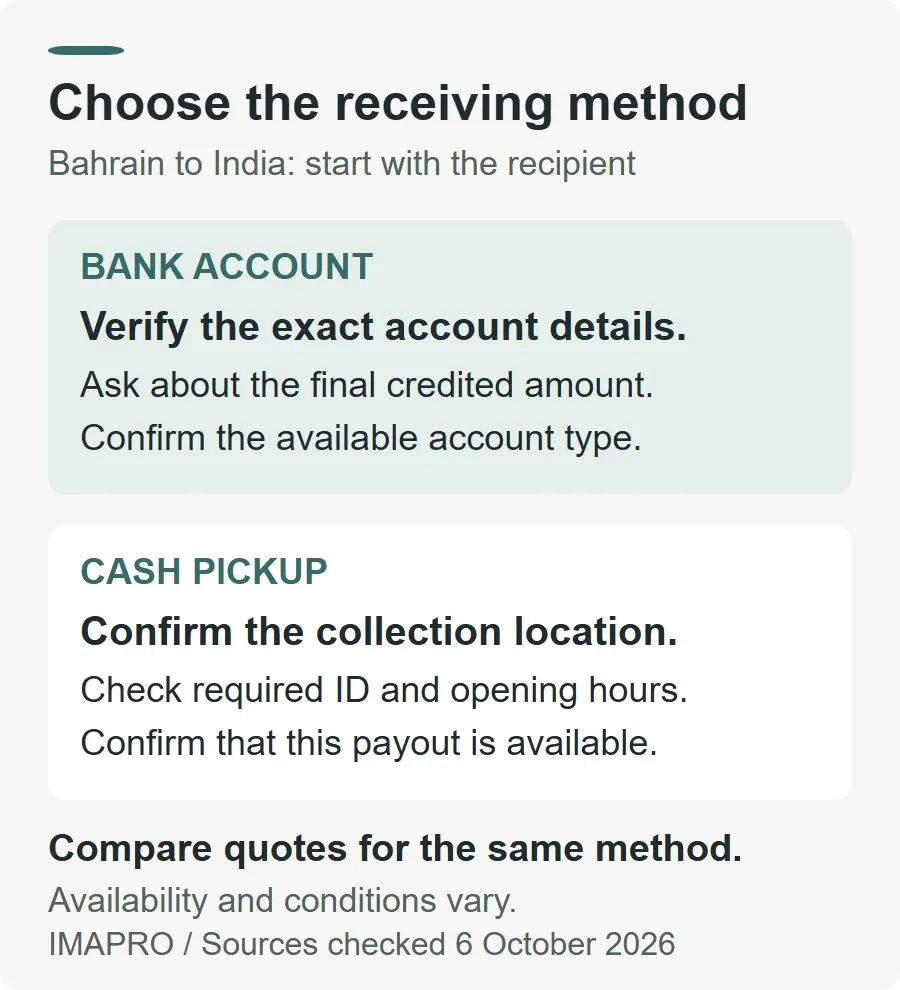
Start with the recipient. Do they want money credited to a bank account, or do they need to collect cash? Then check which services are available for that exact destination and amount. Avoid comparing a bank deposit with cash collection as though they were the same product.
Western Union’s Bahrain-to-India page offers bank-account transfers and cash pickup. Its online service describes payment with a Bahrain-issued debit card. The page also warns that a bank payment follows the account number supplied, so the recipient should verify that number before you send.
BFC’s online portal FAQ describes bank transfers and cash payout, with different fees, rates and limits. It also says the portal can send to NRE and NRO accounts in India. Confirm the account and transfer purpose with the provider if you are unsure which option fits.
For cash collection, ask for the actual payout location, opening hours and required identification before choosing the service. For a bank deposit, ask the recipient for the details requested by the provider’s India form. Do not copy a routing-code checklist meant for another country.
Match the transfer purpose and account to the Indian receiving route
Family support, a transfer to your own non-resident account and a business payment are different instructions. Tell the provider which one you need before comparing prices. The Reserve Bank of India's MTSS Master Direction, updated 29 September 2026, describes the Money Transfer Service Scheme as an inward personal-remittance arrangement. Its restrictions apply to that scheme, not to every bank transfer into India.
Under MTSS, the direction permits personal remittances such as family maintenance and excludes trade, property purchases, investments, charitable contributions and credits to NRE accounts. Its direct-to-account instructions also say the payment should not be credited to NRE or NRO accounts. This does not contradict BFC's statement that its portal supports NRE/NRO transfers: the practical question is which receiving arrangement the provider will use for your account and purpose. Ask BFC and the receiving bank to confirm that route; do not label every remittance an MTSS transfer.
The same RBI direction sets an MTSS cap of USD 2,500 per remittance and 30 remittances to one individual beneficiary in a calendar year. It normally permits cash payment only up to INR 50,000, with amounts above that paid through the specified non-cash methods; it describes an exception for foreign tourists. These are scheme-specific limits, not a general Bahrain-to-India allowance. Ask which scheme applies before using any limit to plan a transfer. RBI MTSS conditions, sections 3.4 and 8.
If the purpose or account falls outside the offered route, pause and ask for an appropriate supported service. Do not choose a misleading purpose just to get through an app form. For a substantial or unusual payment, get the bank's receiving instructions before funding the transfer.
2. Compare total BHD paid with net INR received
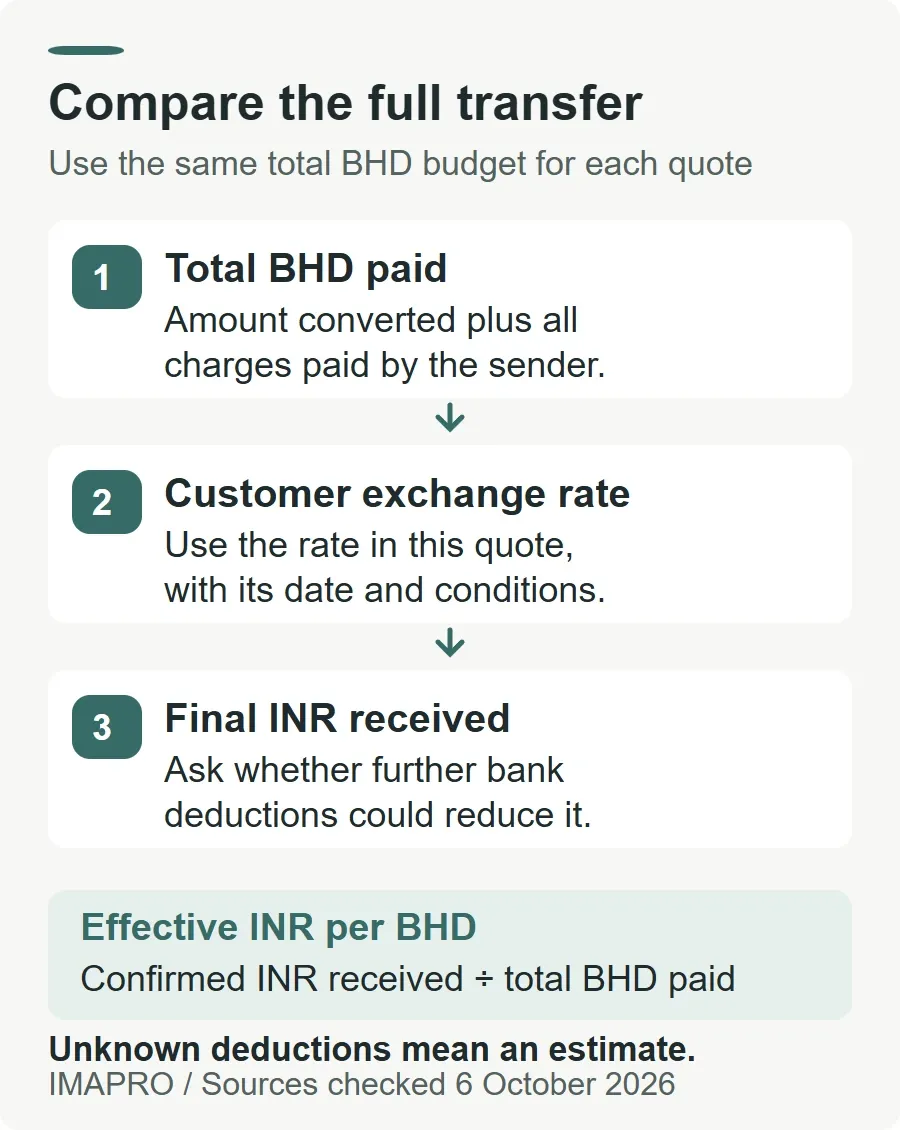
Choose one total budget in BHD and ask each provider for a quote using that budget. Make clear whether the amount you enter includes fees or is only the amount to be converted. Otherwise, two apparently identical transfers can cost different amounts.
| Record | What to check |
|---|---|
| Quote date and time | Record when the quote was obtained and whether it expires. |
| Payment and payout | Use the same funding method and Indian receiving method wherever possible. |
| BHD being converted | Separate the transfer principal from charges paid on top. |
| Total BHD payable | Include the transfer fee and any other charges shown at checkout. |
| Customer exchange rate | Record the rate attached to this quote, not a general currency converter. |
| INR recipient amount | Ask whether this is the final credited amount or whether further deductions can apply. |
| Delivery estimate | Keep the quoted estimate and its conditions alongside the price. |
Where the final receiving amount is confirmed, a simple comparison is:
Effective INR per BHD = confirmed INR received ÷ total BHD paid.
This is arithmetic, not a new exchange-rate quote. If recipient deductions remain unknown, label the result an estimate. Do not put zero in the fee or deduction field just because the website does not show a number.
BFC’s terms of service say its exchange rate and commission appear on the transaction receipt and that beneficiary or intermediary banks may deduct additional charges. Western Union likewise says it earns money from currency exchange and that fees and rates can vary by channel and other factors. Compare both components, then check the final recipient amount.
3. Treat a reference rate as a comparison point
A rate seen in a search result is not proof of what a provider will give you. Check its timestamp, currency direction and service type. A cash-currency buying or selling rate can differ from a remittance rate; LuLu Money’s Bahrain FAQ explicitly distinguishes these services.
Freshness matters even on an official website. When checked on 6 October 2026, the rate table in BFC’s international-transfer page displayed a 17 July 2026 update timestamp. This guide therefore does not reproduce that table as today’s BHD-to-INR rate. Obtain a current transaction quote before making a choice.
If a promotion changes the fee, save its conditions too. Compare the amount available for your transfer, not an introductory offer you may not qualify for.
4. Prepare identification and recipient details
Check registration requirements before the day you need to send. BFC’s published terms require Bahrain residency, a valid CPR card, a local bank account and completed registration for its online portal. Its FAQ describes electronic identity checks and a branch alternative. These are BFC’s conditions, not a universal checklist for every provider.
LuLu’s Bahrain FAQ describes registration using an email address, mobile number and CPR ID. It directs new customers to a branch with their original valid CPR to complete its identity checks. Existing customers with current verification may follow a different route. If your identity document needs attention, use the Bahrain CPR renewal and replacement guide before starting a time-sensitive transfer.
- Ask the recipient to confirm their name and the exact account or collection details.
- Enter the transfer purpose truthfully and respond to the provider’s document requests through its official channel.
- Review saved beneficiary details again, especially after a bank-account change.
- Keep identity documents, card details and one-time codes out of public messages and shared screenshots.
India bank details and cash collection need separate checks
Western Union's India receiving instructions specify the bank account number and Indian Financial System Code (IFSC), remittance purpose, address and mobile number for bank receipt. The account-holder name should match the receiver name. Obtain the IFSC from the recipient's bank records rather than guessing from the bank's name, and recheck it after a branch or account change.
For its cash route, Western Union asks for sender details, the MTCN and government-issued photo ID, with payment after verification. Its India page also advertises a cash-to-bank change feature, but the stated eligible sending countries exclude Bahrain. Do not rely on that feature as a backup for a Bahrain booking. Ask the Bahrain provider what changes are available before paying. India collection and delivery-change conditions.
5. Check delivery conditions and save the reference
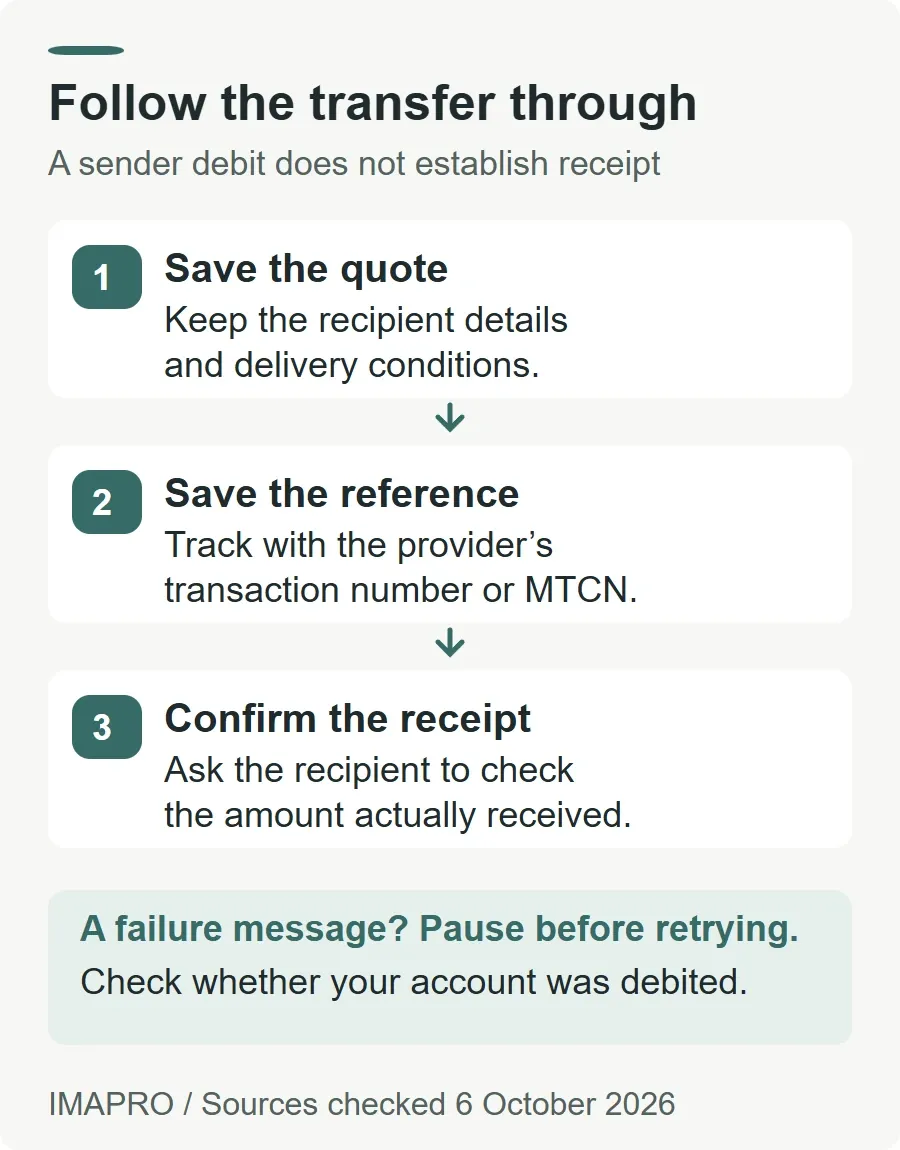
Ask when the quoted delivery period begins: after booking, after the provider receives payment, or after verification finishes. Keep the answer with the receipt. A payment leaving your Bahrain account is not, by itself, confirmation that the recipient has received it.
Western Union qualifies its cash-pickup timing for matters including identification, regulatory checks, recipient actions and agent hours. Its MTCN is the tracking reference. BFC provides an online status tracker using its transaction number. Use the reference for the provider you actually booked with.
If LuLu’s payment screen reports failure, its FAQ tells customers to check whether their bank account was debited before trying again, then await a status update or contact the bank about a refund. That is a useful reason to pause rather than create a second transfer immediately.
Before paying, save the quote or confirmation privately. Afterwards, keep the receipt, reference, recipient details and the delivery estimate together. Ask the recipient to confirm the amount credited so you can reconcile it with the quote.
6. Handle a delay, error or cancellation promptly
Contact the provider through its official support channel with the reference, payment time, promised delivery estimate and current status. Say whether the money has left your account and whether the recipient has checked theirs. Ask for a complaint reference and a written response if the issue remains unresolved.
Do not assume a transfer can be recalled after payment. BFC’s FAQ warns that cancellation may be impossible once a bank transfer has been processed. Its terms also describe possible refund deductions and conversion at the prevailing buying rate, subject to the stated exception for BFC negligence. Read the terms attached to your transfer and ask for the expected refund amount before accepting a cancellation.
For unresolved concerns, the Central Bank of Bahrain consumer-information page provides complaint routes. CBB says it reviews complaints for possible breaches of its regulatory requirements. Keep the provider’s response and supporting records; contacting the regulator does not promise compensation or an immediate reversal.
Describe the failure precisely when you ask for help
| What you can see | Useful next question |
|---|---|
| Bank debited, payment screen failed | Ask the sender whether the booking exists and whether payment was matched to it before retrying. |
| Provider says sent, Indian account has no credit | Give the sender the reference and ask for the payout status or trace. Have the recipient check the stated account, rather than only SMS alerts. |
| Cash ready, collection refused | Ask the named agent which requirement is unmet, such as identification or a name mismatch, then ask the sender to resolve it. |
| Recipient receives less than quoted | Compare the receipt with the credit and ask which charge or conversion caused the difference. |
This table is an editorial troubleshooting sequence, not a diagnosis or a refund timetable. It combines the LuLu failed-payment warning, BFC tracking guidance and BFC charge and refund terms. Provide private records only to the relevant institution through its official channel.
Before you pay
Confirm five things: the correct recipient, the correct receiving method, the full BHD debit, the expected INR credit and the delivery conditions. If any fee, deduction or timing condition is unclear, ask for it before proceeding. For other local money-management topics, browse the Bahrain finance guides.
Frequently asked questions
Which service is cheapest for sending money from Bahrain to India?
No provider is established as cheapest here. Compare fresh quotes for the same total BHD payment and payout method, then choose using the confirmed INR amount and delivery conditions. A lower advertised fee can be offset by the exchange rate or deductions. Western Union price conditions.
Can someone in India receive money without a bank account?
A supported cash-pickup route may work. Confirm the booked collection service and its ID requirements first. Western Union's India instructions require sender details, MTCN and government-issued photo identification. India receiving guide.
Can I send to an NRE or NRO account?
BFC's portal FAQ says it supports those accounts, but the receiving arrangement matters. MTSS has account restrictions. Ask the provider and recipient bank to confirm the suitable route rather than using the account label alone. BFC account support; RBI MTSS direction.
Is the rate on a currency converter the rate I will receive?
Use the rate on your transaction quote. LuLu distinguishes remittance rates from cash-currency buying and selling rates. Also check the timestamp and direction: BHD sent and INR received. LuLu rate explanation.
Should I send again if the app says payment failed?
First check whether your account was debited and whether the provider has a transfer record. LuLu explicitly advises checking the debit before another attempt. An error screen alone does not establish that no money moved. LuLu failed-payment instructions.
Can I cancel after the money has left Bahrain?
Ask the provider immediately. BFC warns that processed bank transfers may not be cancellable, and its refund terms can involve deductions and rate adjustment. Obtain confirmation of cancellation and the expected refund instead of assuming the full original debit will return. BFC cancellation FAQ; refund terms.
This article provides general information, not personalised financial, investment, tax or legal advice. Provider availability, requirements, prices and terms can change. Confirm the current terms for your own transfer through the provider’s official service.