Bahrain finance guides
Best credit card in Bahrain? Compare fees, cashback and repayment
By Gaurav Agarwal · Sources checked 6 October 2026
Compare the annual fee, rewards on your actual spending and the total cost of repayment. ila Blue has no annual fee, Standard Chartered Rewards has a published BHD 33 annual fee, and BisB Cashback requires clarification of its card-specific tariff. No card is best for everyone.
Jump to a section
- Credit cards in Bahrain: a practical shortlist
- Choose the spending pattern before choosing the card
- Check salary, residence and documents early
- Calculate rewards after exclusions and caps
- Read beyond the annual fee and headline interest rate
- The minimum payment is not the interest-free amount
- Treat lounge access and insurance as conditional benefits
- Get these answers before applying
- Frequently asked questions
The best credit card in Bahrain depends on what you spend, what you can repay and which benefits you will actually use. Start with the annual fee, eligible rewards and cost of carrying a balance. This guide compares a small, verifiable shortlist from ila Bank, Standard Chartered and Bahrain Islamic Bank, then shows how to assess an offer against your own spending.
Checked 6 October 2026. Prices and conditions below come from the linked official product pages and tariffs available on that date. This is a selective comparison, not a ranking of every Bahrain card or an assurance of approval. General information only, not personal financial advice.
Credit cards in Bahrain: a practical shortlist
Compare the primary card you would apply for, rather than assuming every product from one bank has the same price. The table separates confirmed terms from information that still needs a written answer.
| Card | Annual fee and borrowing rate | Main comparison point | Important qualification |
|---|---|---|---|
| ila Blue | Primary annual fee: free. Interest: 1.833% monthly; published annual rate: 22%. ila tariff | Cashback option: 1% on domestic and international transactions, with lower rates or exclusions for certain categories. Product terms | A useful starting comparison for everyday spending. Foreign transaction charges still matter. |
| ila Switch | Primary annual fee: free. Standard tariff: 1.25% monthly on transferred balances; 1.833% on purchases. ila tariff | The product page advertises an introductory 0% rate for six months on the transferred amount. Current offer | Compare a written transfer quote, any charges and the remaining balance after the introductory period. |
| Standard Chartered Rewards | BHD 33 annual fee including applicable VAT. Interest: 2.50% monthly; published annual interest rate: 30%. Service and Price Guide, page 7 | Points and travel benefits. Points are not a cashback percentage. Product page | Check the reward redemption value and lounge conditions before assigning those benefits a dinar value. |
| BisB Mastercard Cashback | Card-specific annual membership fee and effective repayment cost are not established by the reviewed product page and generic tariff. Obtain written confirmation. | 3% supermarkets, 2% international and 1% e-commerce; BHD 200 monthly minimum spend and BHD 25 monthly cashback cap. Product page | Do not treat its service-fee structure as a conventional interest rate or assume that no advertised annual fee means no cost. Card terms |
Why no HSBC Cashback entry? HSBC says its Bahrain consumer banking transfer to BBK completed after close of business on 27 November 2025. An old HSBC tariff in search results is therefore not evidence of a currently available HSBC retail card. Existing customers should use the transition guidance and their current issuer documents. HSBC transfer announcement, checked 6 October 2026.
Choose the spending pattern before choosing the card
Use several recent statements to make a monthly budget by category. Include quiet months as well as holidays. A supermarket offer can be valuable to one household and barely relevant to someone whose spending is mostly rent, school fees or transfers.
| Your main use | Compare first | Question to resolve |
|---|---|---|
| Everyday local purchases | Eligible cashback after annual fees | Which merchants and transactions are excluded? |
| Groceries and online orders | Category rates, monthly thresholds and caps | How are online supermarket orders classified? |
| Travel and foreign websites | Foreign transaction charges and usable travel benefits | Does the benefit apply to this booking, currency and traveller? |
| An existing unpaid balance | Total repayment cost over the intended repayment period | What remains payable when the introductory rate ends? |
| Occasional use | Fixed fees and conditions for retaining benefits | Would the annual fee outweigh the rewards? |
Set a personal value of zero for a benefit you would not otherwise use. Avoid adding an expensive trip or an unnecessary purchase merely to qualify for a fee waiver.
Compare three repayment situations separately
For someone paying the full bill, the useful comparison is eligible rewards and genuinely used benefits after fees. For someone carrying a balance, begin with the repayment cost and time to clear it. For a balance transfer, compare the transferred debt and any new purchases separately. A card can look attractive in one situation and costly in another.
Use a whole year of typical spending where possible, with separate rows for supermarkets, other local purchases, education, government payments, foreign purchases and excluded transactions. Apply each card's earning categories, then its monthly minimum and cap. Deduct annual membership and transaction costs. Value miles or vouchers only at a redemption you could actually use, and keep borrowing costs separate so they remain visible.
Check salary, residence and documents early
For ila Blue and Switch, the published primary-card age range is 21 to 65. Minimum monthly income is BHD 300 for employed Bahrainis, BHD 500 for employed non-Bahrainis, and BHD 1,000 for self-employed applicants and professionals. The page lists minimum service of three months for Bahrainis and six months for non-Bahrainis. Meeting those published thresholds is not an approval guarantee. ila eligibility, checked 6 October 2026.
ila’s general card FAQ instead lists an upper age of 59. Because the public pages conflict, applicants above that age should confirm eligibility directly before applying. ila FAQ, checked 6 October 2026.
Standard Chartered lists resident salaried and self-employed applicants, with primary-card ages 21 to 60. Its documents include salary evidence and a smart-card copy; expatriates also need passport and residence-permit copies, and self-employed applicants need a commercial registration copy. The reviewed eligibility page does not publish a minimum salary figure. Ask for the requirement for the exact card. Standard Chartered eligibility and documents, checked 6 October 2026.
BisB’s cashback page lists age 21 or above and a minimum credit limit of BHD 300. That is a credit limit, not a stated minimum salary. Confirm income, employment and residence requirements with the bank. BisB eligibility, checked 6 October 2026.
A large approved limit is also a borrowing commitment
For conventional consumer-finance assessments within CBB CM-5, banks ordinarily include 5% of available credit-card limits when calculating the repayment ratio. If the outstanding amount including interest exceeds the limit, the full outstanding amount is counted; charge cards are excluded from this definition. A card you rarely use can therefore affect a later loan assessment. Ask how the proposed limit fits alongside existing facilities.
The same chapter ordinarily caps total consumer-finance repayments at 50% of gross regular income, subject to specified exceptions and a fuller affordability review. This is a conventional-bank rule with a defined consumer-finance scope, not a recommended card limit or a claim about every Islamic card contract.
Calculate rewards after exclusions and caps
ila’s cashback table reduces government transactions to 0.5% and education to 0.20%; fuel, charity and cash withdrawals earn none. Those categories can materially change the result for a household with large school or government bills. ila rewards table, checked 6 October 2026.
For BisB, the advertised category percentages do not establish what happens to a purchase that is both international and online, or how every merchant is classified. Ask which single rate applies, what spending counts toward the minimum, and whether refunds affect the threshold. Do not add advertised category rates together. The product page establishes the categories, minimum and cap, but leaves those edge cases to clarification. BisB cashback offer, checked 6 October 2026.
Standard Chartered’s published Rewards points schedule gives two points per BHD 1 for general local and international spending, with reduced local earning categories and no points for charity or fuel. Two points are not two dinars or 2% cashback. Compare the actual voucher, statement-credit or miles redemption you intend to use. Points earning schedule and unit definition on page 8 of the tariff, checked 6 October 2026.
Use an annual rewards worksheet
Multiply eligible spending in each category by that card's published earning rate, apply the conditions and caps, and add the results. Subtract membership charges and the transaction costs triggered by that spending. If a reward figure depends on an unconfirmed merchant category or redemption value, leave it unresolved instead of treating the best possible outcome as certain.
For ila Blue, a free primary membership and the published 1% standard cashback rate are useful inputs, but government and education payments have lower rates and excluded transactions earn none. For BisB, calculate each month's result separately because the BHD 200 minimum and BHD 25 cap are monthly. An annual spending total cannot show whether every month qualified. Sources: ila categories and BisB conditions, checked 6 October 2026.
Read beyond the annual fee and headline interest rate
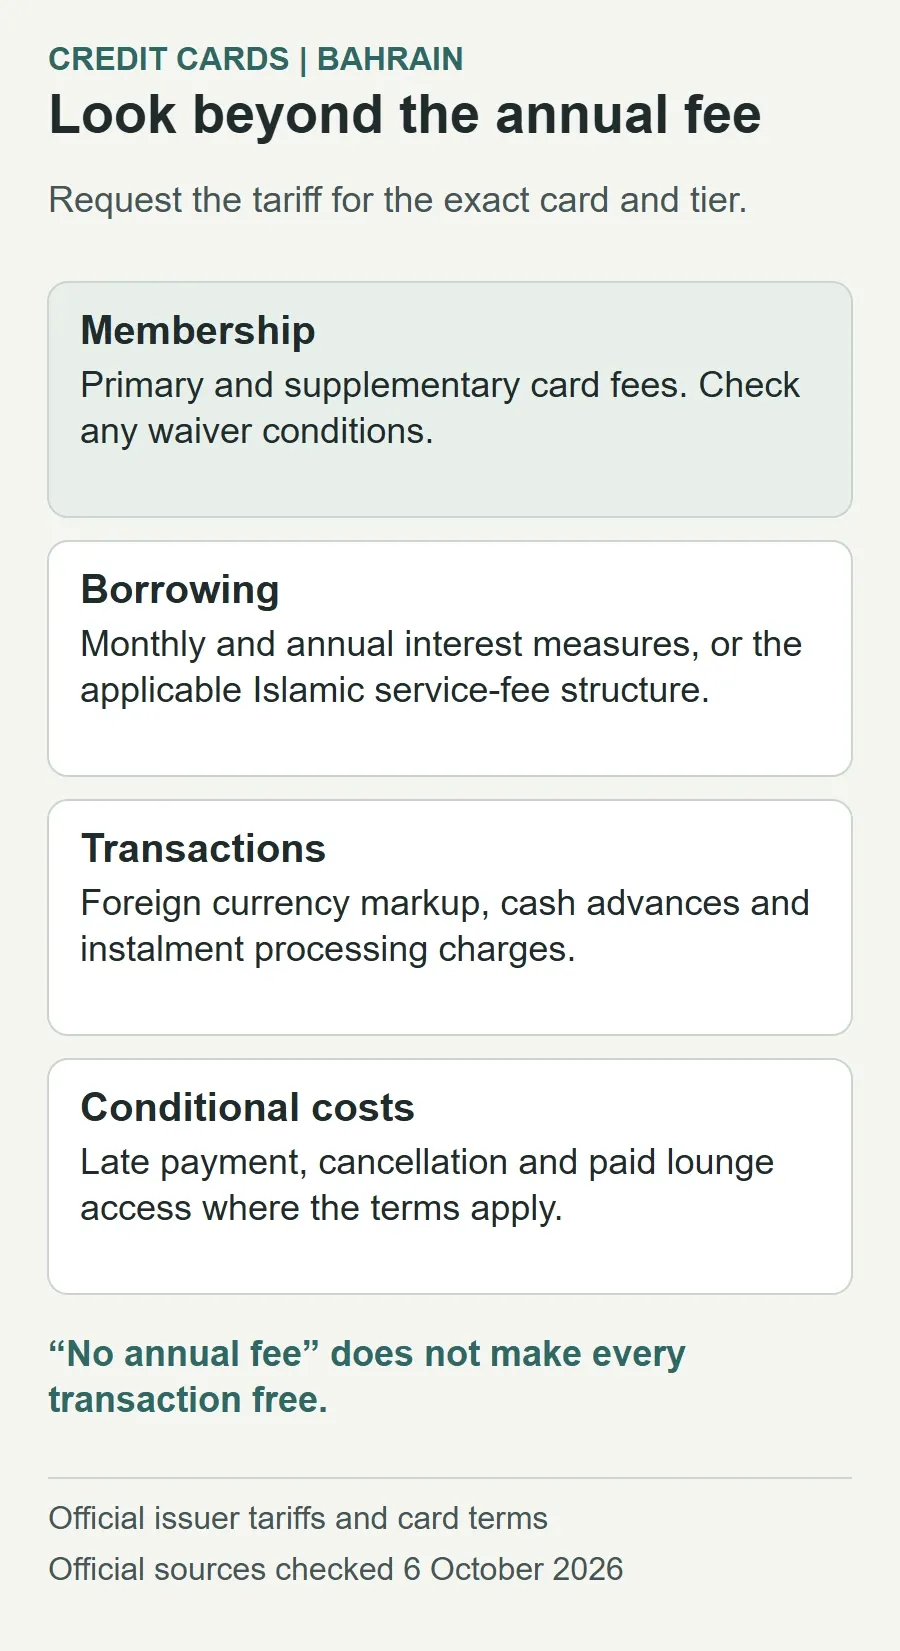
A free annual membership does not make every transaction free. ila’s current tariff lists FX markup of 2.97% for GCC transactions and 3.3% internationally, and a cash-advance fee of 5.50% with a BHD 5.500 minimum, inclusive of applicable VAT. It also lists a 5% Easy Payment Plan processing fee, minimum BHD 5.500, effective May 2026. Check which classification applies to your purchase. ila tariff, checked 6 October 2026.
A processing fee remains a cost when the interest rate is 0%. Calculate it on the transaction amount using the exact offer, check any minimum, and add all scheduled repayments and separately charged fees. Do not reuse an instalment-plan fee as the fee for a balance-transfer offer.
Ask for both the monthly rate and the annual measure the issuer uses. An annual interest rate, an effective annual rate and an APR that includes particular costs are not interchangeable labels. Preserve the bank’s stated units. Do not compare a monthly card rate directly with an annual loan rate.
BisB’s terms describe a fixed service fee and possible waivers linked to repayment. Its generic tariff reviewed here does not name a Cashback column. A figure from another tier cannot safely fill that gap. Request the current Cashback tariff and worked examples for paying in full, paying partly and withdrawing cash. BisB terms and generic card tariff, checked 6 October 2026.
Keep Islamic service fees distinct from annual membership
BisB's card terms actually name Cashback in the service-fee schedule: BHD 170 monthly and BHD 2,040 annually, with wording allowing waiver based on repayment. These are the stated service-fee amounts before any applicable waiver, not a verified annual membership price or the amount every customer will pay. The available generic tariff does not establish the exact Cashback membership charge or reproduce a complete worked waiver calculation. Request both in writing before comparing its effective cost with a conventional card.
Ask for separate illustrations of full repayment, partial repayment, a cash withdrawal and a missed payment. The distinction matters because a headline cashback rate cannot establish the net result of a contract whose actual service-fee waiver has not been explained. Keep the unverified parts blank rather than substituting another BisB tier's price.
The minimum payment is not the interest-free amount
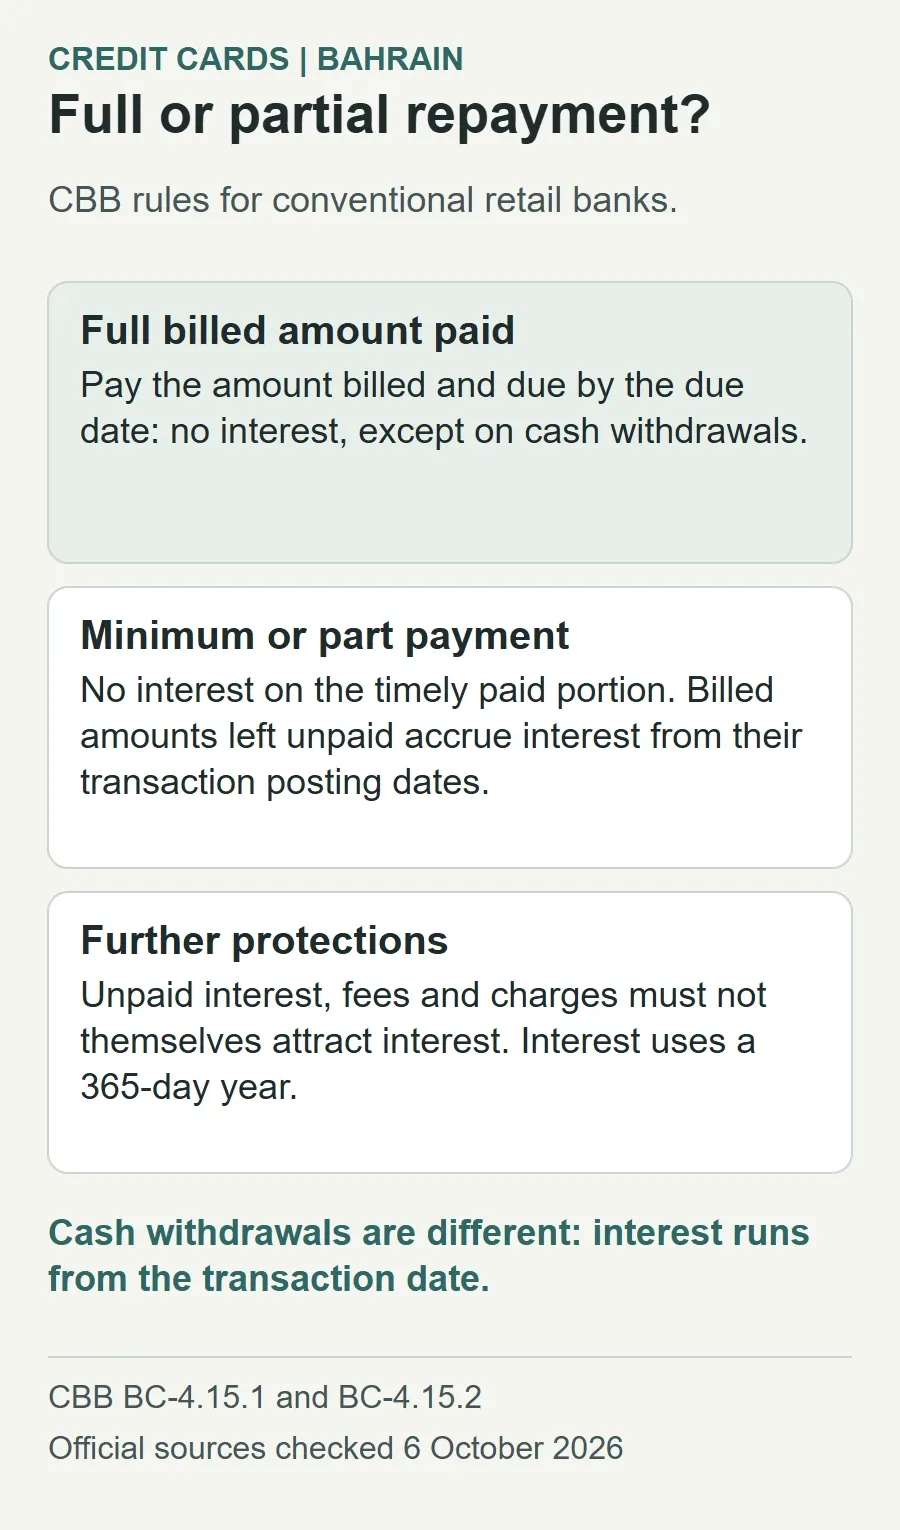
Separate three dates and amounts: the statement date, the payment due date and the full statement balance. Paying the minimum can satisfy a payment requirement while leaving most of the borrowing unpaid.
Standard Chartered’s tariff gives 20 days from statement date to payment due date. Its minimum is the greater of BHD 10 or 1% of outstanding principal plus all instalments, fees, charges and interest. Standard Chartered tariff, page 7, checked 6 October 2026. For conventional retail banks, CBB rules say full payment of the amount billed and due by the due date avoids interest except on cash withdrawals. Interest must not be charged on timely partial payments against that bill; interest on billed amounts left unpaid is calculated from the transaction posting date. Outstanding interest, fees and charges must not themselves attract interest. Ask the issuer for the eligible principal and dates behind any charge. CBB BC-4.15.1 and BC-4.15.2, checked 6 October 2026.
When a payment covers interest and fees as well as principal, the amount by which the debt falls can be smaller than the amount paid. The result depends on transaction dates, payment allocation, new spending and the agreement’s charging method. Ask the issuer for a repayment illustration using your actual balance and intended payments.
Before accepting a card, ask what happens to the interest-free period after partial payment and how it is restored. Check whether an automatic payment covers the minimum, a fixed amount or the full statement balance. Keep enough money in the funding account and verify that payment was received.
Check the statement calculation transaction by transaction
Cash advances need a separate line: under CBB BC-4.15.1(c), conventional retail-bank cash-withdrawal interest runs from the transaction date, even though a purchase bill may qualify for interest-free treatment when fully paid on time. BC-4.15.2 requires a 365-day year for card-interest calculations. Keep the cash-advance fee separate from that interest.
If a finance charge is unclear, request the principal balance used, posting dates, cash-transaction dates, payment credits and rate. Check that timely payment against the billed amount has been recognised and that outstanding interest, fees and charges have not themselves attracted interest. A monthly percentage alone cannot reproduce a statement without those dates and allocations.
Read the balance-transfer payment order
The ila Switch product page states that payments settle transferred balances first. It advertises six months at 0% on transferred amounts, followed by 1.25% monthly on what remains, and 1.833% monthly on new purchases. New spending and transferred debt can therefore be subject to different pricing and allocation. Ask how your planned payment will be split and what balance remains when the offer ends. Confirm the offer's eligibility, fees and start date before relying on it.
Treat lounge access and insurance as conditional benefits
Standard Chartered’s current Rewards page specifies the Visa Airport Companion app and an international transaction of at least USD 1 equivalent every 90 days, completed at least ten days before a lounge visit. It states a USD 32 usage charge if the spending condition is missed and USD 32 for an additional guest. Check the app and current terms before travelling. Rewards lounge conditions, checked 6 October 2026.
For any card, review the insurance policy itself: covered travellers, trip length, exclusions, excess, booking-payment conditions and the claims procedure. A marketing mention of travel insurance is not enough to establish that a particular trip is covered. Use the Bahrain travel insurance guide to structure that separate comparison.
Get these answers before applying
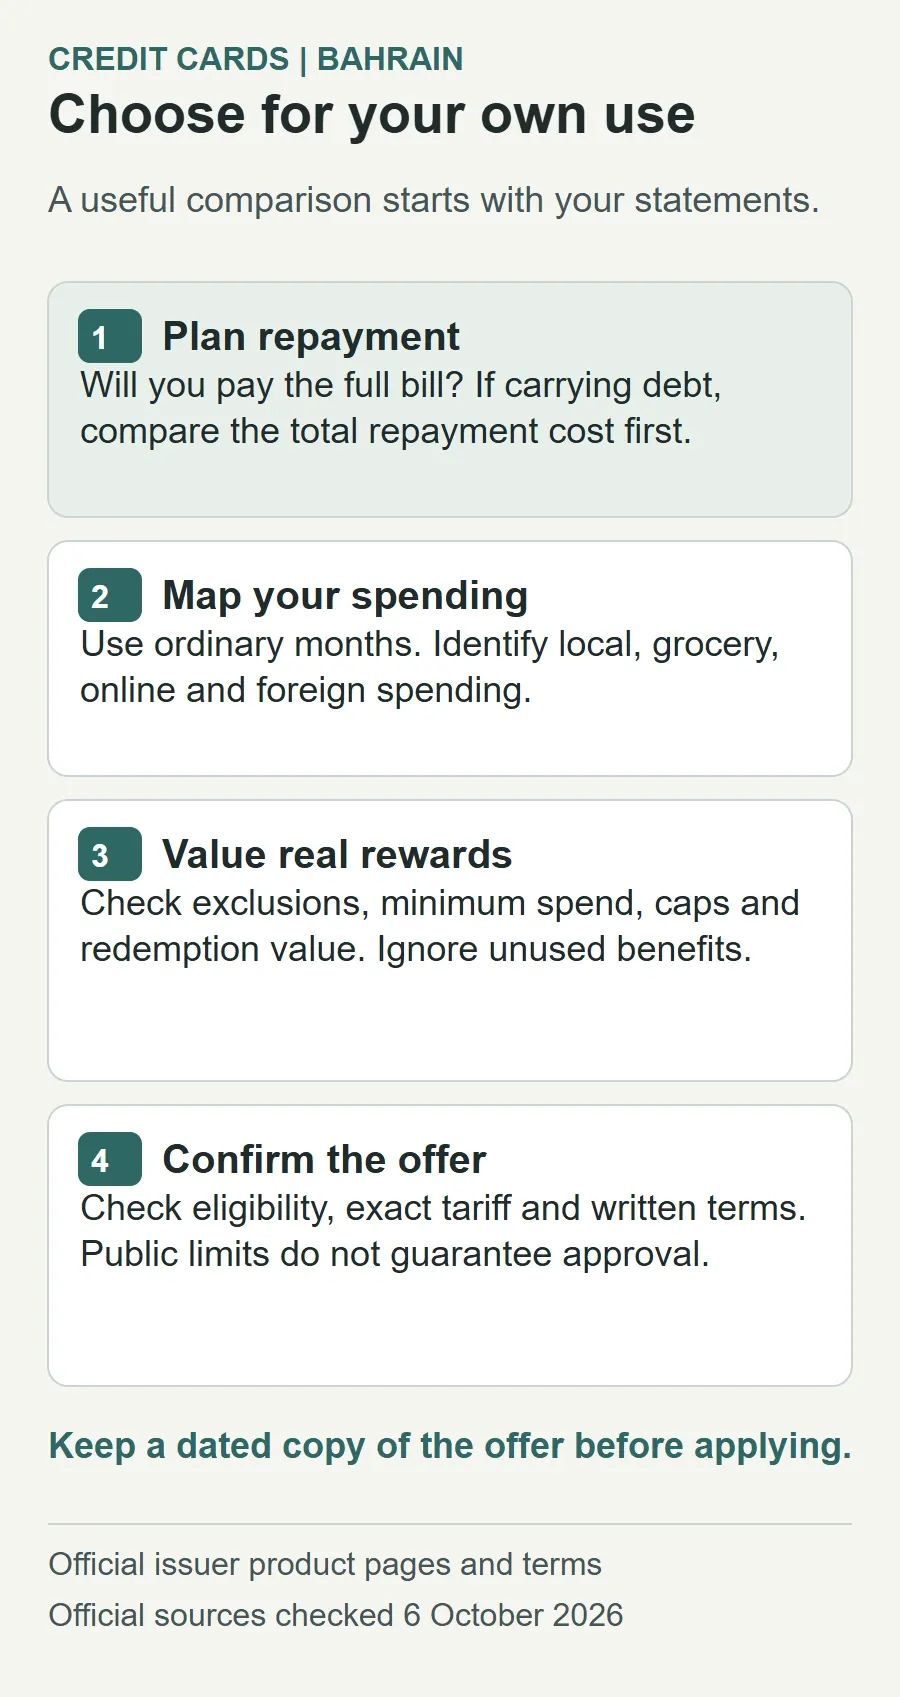
- Confirm the exact product. Record the issuer, card tier, eligibility and whether the offer is open to new applicants.
- Save the dated tariff. Include membership, supplementary-card, FX, cash-advance, late-payment, instalment and cancellation charges.
- Request repayment examples. Ask for total payable under full repayment and the realistic repayment period you expect.
- Check reward mechanics. Confirm merchant categories, caps, minimum spend, refunds, expiry and redemption value.
- Confirm the final offer in writing. A general product page does not establish your approved limit or any individual waiver.
If a fee differs from what was disclosed, preserve the agreement, statement and complaint correspondence. The Central Bank of Bahrain’s consumer page explains its complaint role and links to the applicable procedure. It does not promise reimbursement simply because a customer dislikes a correctly disclosed charge. CBB consumer information, checked 6 October 2026.
Source note: ila’s linked tariff states February 2026 effectiveness with a May 2026 instalment-fee update. Standard Chartered’s linked guide is version August 2025; its card notes state the card charges apply from June 2024. These are document dates, separate from our 6 October 2026 check. Undated product pages and older files should be reconfirmed with the issuer before application.
Keep a decision record you can revisit
| Evidence | What it resolves |
|---|---|
| Exact card name and issuer | A legacy page, award or premium-banking membership does not establish today's card availability. |
| Current tariff and personal offer | Confirms membership price, waiver conditions, borrowing or service charges and the actual approved limit. |
| Reward rules and intended redemption | Shows category exclusions, minimums, caps, expiry, merchant classification and usable value. |
| Payment instruction and sample statement | Confirms what is debited, when it reaches the issuer and how payments are allocated. |
| Benefit terms | Confirms lounge registration, qualifying spend, guest costs and insurance eligibility. |
Repeat the comparison when a fee waiver ends, your spending changes or a new tariff takes effect. Under the conventional-bank BC-4.3 disclosure rules, monthly card statements and advance disclosure of relevant changes are required. Save the notice as well as the original tariff so you can establish which terms applied to a particular statement.
Frequently asked questions
Which credit card is best in Bahrain?
No single winner follows from this selective comparison. Compare your repayment pattern, eligible annual rewards, fixed charges and the benefits you will use. Missing BisB card-specific pricing and individual approval conditions prevent a complete price ranking.
Does a card with no annual fee have no cost?
No. ila Blue and Switch have free primary membership in the reviewed tariff, but borrowing, foreign transactions, cash advances and some payment plans can cost money. Use the exact ila tariff for the transaction you intend.
Will paying the minimum avoid interest?
Not necessarily. For conventional retail banks, BC-4.15.1 protects full timely payment except cash withdrawals and also protects the timely paid portion of a bill. Billed principal left unpaid can accrue interest from posting dates. A minimum payment and full repayment have different consequences.
Does interest apply to a cash withdrawal even if I pay the bill in full?
For conventional retail cards, cash withdrawals are an exception to the full-payment protection. BC-4.15.1(c) starts cash interest on the transaction date. The issuer may also charge the separate cash-advance fee in its tariff.
Can an expatriate get an ila Blue or Switch card?
The product page publishes an employed non-Bahraini route with BHD 500 minimum monthly income and six months of service. Approval still depends on assessment. Its upper age differs from the general FAQ, so confirm the applicable limit if that affects you.
Is BisB's BHD 300 figure a minimum salary?
No. The reviewed Cashback product page states a minimum credit limit. It does not establish a BHD 300 salary requirement. Obtain income and employment criteria directly for that card.
Can I add supermarket, online and international cashback rates together?
Do not assume so. The BisB page lists category rates but does not resolve every overlapping category or merchant classification. Ask which rate applies to the particular transaction and how refunds, the monthly minimum and the cap are handled.
Are two reward points worth 2% cashback?
No. The Standard Chartered schedule establishes points earned, not their cash value. Use the points required for an available redemption and the value you would actually receive.
Does 0% balance transfer cover purchases too?
Not necessarily. ila Switch distinguishes transferred balances from new purchases and applies payments to transfers first. Confirm the transfer fee, payment allocation, expiry and post-offer rate in your written offer.
Does a lounge logo guarantee free entry?
No. Standard Chartered Rewards has app registration, qualifying international-spend and timing conditions, plus guest or non-qualifying usage charges. Confirm the current conditions before travelling.
Will an unused card matter when I apply for a loan?
It can. Within the scoped conventional consumer-finance rules, CM-5.4.5 counts available card limits in the repayment assessment. The balance alone does not describe that commitment.
Can I rely on an old HSBC Bahrain cashback comparison?
Check the current issuer first. HSBC confirms that its Bahrain consumer-banking transfer to BBK completed after business on 27 November 2025. An old indexed tariff does not establish a product available to new HSBC retail applicants today.