Motor insurance pillar
Car Insurance in Bahrain: Prices, Cover, Claims and Licensed Insurers
By Gaurav Agarwal · Reviewed 6 October 2026
Every registered car in Bahrain needs valid third-party liability insurance. Comprehensive insurance adds cover for your own car, subject to the policy. For a private car, the CBB schedule shows maximum annual third-party premiums from BHD 50 to BHD 83 before any permitted adjustments, based on engine capacity. A comprehensive quote has no single public market price, so compare the insured value, excess, repair basis, drivers and extensions on the same terms.
01Third-party or comprehensive: what each one pays for
| Question | Third-party liability | Comprehensive |
|---|---|---|
| Meets the minimum insurance requirement? | Yes, when the issued policy meets Bahrain's compulsory liability rules. | Yes. The comprehensive contract includes the compulsory liability section. |
| Damage you cause to another vehicle or property? | Covered within the compulsory policy rules and limits. | Covered through the liability section. |
| Injury to another person? | Covered under the liability section, subject to the compulsory wording. | Covered through the liability section. |
| Damage to your own car when you are at fault? | No. | Usually covered for listed insured events, less applicable excess and exclusions. |
| Theft, fire, flood, windscreen or roadside help? | Not own-car benefits. | They can be included or optional. Check the schedule and wording. |
| Agency repair? | Not an own-car benefit. | May be included for a stated vehicle age or sold as an option. |
| Best fit | A driver who can absorb the loss of their own car and wants the legal minimum. | A driver who wants protection for the car's value as well as liability cover. |
Sources: CBB motor insurance schedule, CBB Resolution No. 23 of 2016, and Takaful International's public motor explanation.
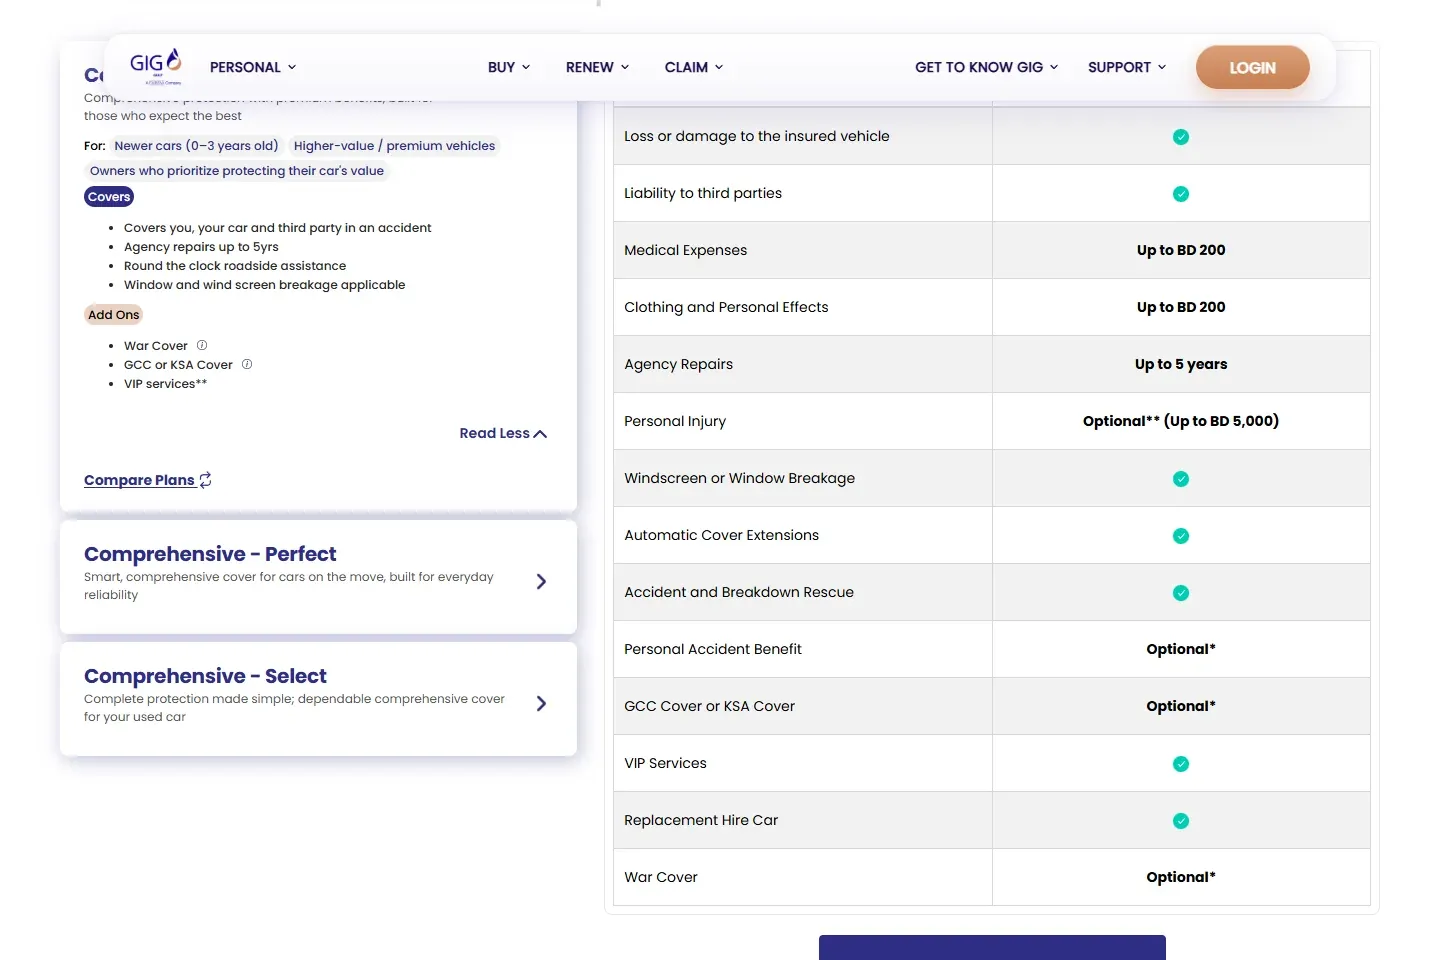
The legal labels do not tell you whether two comprehensive quotes are equivalent. GIG Gulf's current public comparison, for example, separates plans by agency-repair period, medical expenses, personal injury, replacement car, roadside assistance and territorial extensions. Liva and Takaful International publish different packages and options. The policy schedule issued in your name is the usable comparison document.
Read the focused third-party versus comprehensive guide if the cover decision is your main question.
02The compulsory insurance rule and GDT registration requirement
Bahrain's compulsory motor liability framework is set out in the unified policy issued under CBB Governor Resolution No. 23 of 2016. The official policy wording defines the compulsory civil-liability policy for vehicle accidents and the rules used for third-party motor claims. Insurer product pages from GIG Gulf, Liva and Arabia Insurance also describe third-party liability as the compulsory or minimum cover.
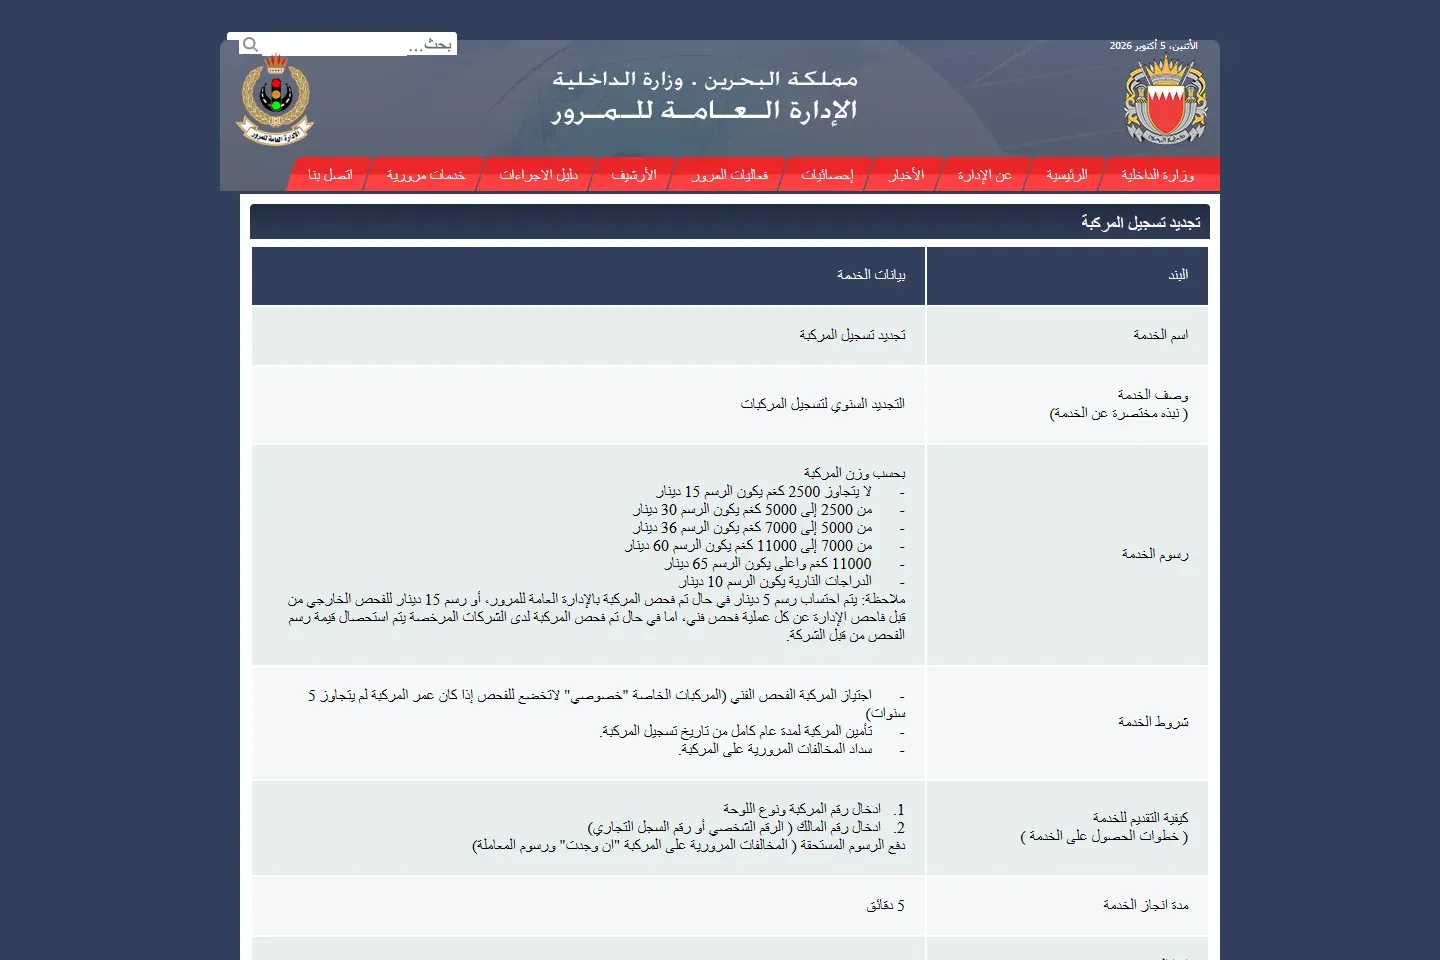
The General Directorate of Traffic treats insurance and vehicle registration as connected but separate steps. Its vehicle-registration renewal service says the vehicle must be insured for a full year from the registration date. It also lists any required technical inspection and clearance of traffic contraventions. Paying the insurer does not by itself finish the government renewal.
03Official price and excess references
Maximum annual third-party premiums for private cars
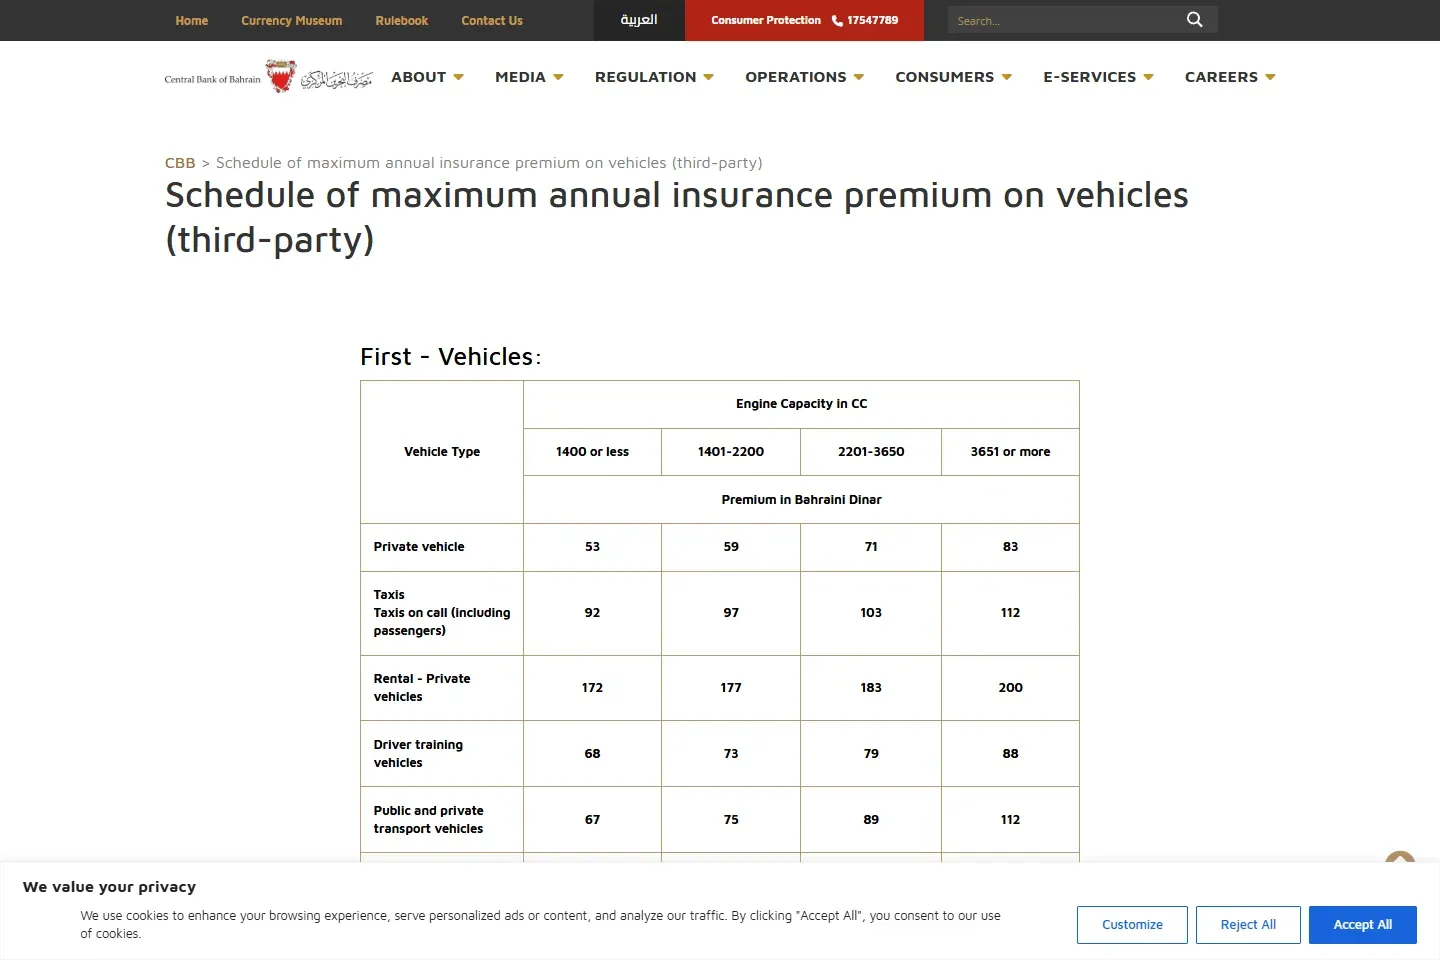
The CBB insurance schedule publishes maximum annual premiums for third-party insurance. For a private car, the displayed figures checked on 5 October 2026 were:
| Private-car engine capacity | CBB maximum annual premium |
|---|---|
| Up to 1,400 cc | BHD 50 |
| 1,401 to 2,200 cc | BHD 59 |
| 2,201 to 3,600 cc | BHD 71 |
| More than 3,600 cc | BHD 83 |
Official source and date: Central Bank of Bahrain insurance schedule, checked 5 October 2026. Use the CBB calculator for the applicable vehicle type and inputs.
These figures are the public maximum schedule for the base category shown. They are not a promise that every driver will receive that exact figure, and they are not comprehensive-insurance prices. Use the calculator and written quote because the schedule contains vehicle categories and permitted adjustments that may affect the result.
Published comprehensive excess example
There is no honest universal Bahrain comprehensive premium or excess range because the insurer sets the quote and the schedule can add different excesses. A public wording can still show the scale and structure. New India Assurance's Bahrain comprehensive wording publishes this compulsory excess table:
| Vehicle insured value | Compulsory excess | Additional young or novice driver excess |
|---|---|---|
| Up to BHD 20,000 | BHD 50 | BHD 50 |
| More than BHD 20,000 and up to BHD 50,000 | BHD 100 | BHD 100 |
| More than BHD 50,000 | Agreed between the insurer and insured | BHD 200 |
The same wording states an additional BHD 100 deductible where the person driving is unknown. This is a New India policy example checked 5 October 2026, not a market-wide tariff.
Ask every insurer to state the base excess, any driver-age or licence-related excess, windscreen excess, off-road excess, unknown-driver excess and any contribution for agency repair or betterment. A BHD 20 saving in premium can disappear in one claim if the excess or repair contribution is higher.
04Motor insurers to verify in the CBB register
The CBB Licensing Directory is the official place to check the legal insurer. Select Insurance Licensees, then the relevant locally incorporated or overseas insurance category, and search the legal name. The list below includes providers that had a public Bahrain motor product or wording when checked on 6 October 2026. It is a practical cross-check, not a permanent or exhaustive register.
| Brand or public motor page | Legal name to look for in the CBB register | What the official page provides |
|---|---|---|
| GIG Gulf | Gulf Insurance Group (Gulf) B.S.C. (c) | Plan comparison, policy handbooks, claims and renewal. |
| Bahrain Kuwait Insurance | Bahrain Kuwait Insurance Company B.S.C. | Bahrain insurer portal and policy services. |
| Solidarity Bahrain | Solidarity Bahrain B.S.C. | Motor quotes, renewal and motor claims. |
| Takaful International | Takaful International Co. B.S.C. | Third-party and comprehensive takaful benefits, wording and claims. |
| SNIC Insurance | SNIC Insurance B.S.C. (c) | Motor cover and benefit information. |
| Liva Bahrain | LIVA Insurance B.S.C. (c) | Comprehensive products, terms and claims information. |
| Arabia Insurance | Arabia Insurance Company S.A.L., Bahrain branch | Third-party and comprehensive products, wordings and renewal. |
| New India Assurance | The New India Assurance Co. Ltd., Bahrain branch | Three motor cover levels, wordings and claim documents. |
| United Insurance Company | United Insurance Co. B.S.C. (c) | Causeway cover for Bahraini vehicles in Saudi Arabia and non-Bahraini vehicles in Bahrain. |
Do not rely on a trading name, comparison page or payment app alone. The certificate and schedule should identify the insurer that carries the risk. If a seller cannot show that legal name, stop and check the CBB directory.
05How to compare car-insurance quotes without distorting the result
- Fix one insured value. Give every provider the same realistic vehicle value. A lower value can reduce the premium while also reducing a total-loss settlement.
- Name every regular driver. Provide the ages, licence history and claims information the insurer asks for. Let the insurer confirm whether a driver restriction or extra excess applies.
- Choose the repair basis. Ask whether the quote includes agency repair, an insurer-approved garage or a contribution if you choose the agency yourself.
- List the extensions you need. Common comparison rows include roadside recovery, replacement car, windscreen, flood and storm, personal accident, GCC or Saudi cover, off-road use and no-claims discount.
- Request the documents. Get the quote, benefit table, schedule, wording and endorsements. A message that states only the premium is not enough.
- Compare the claim cost. Add the compulsory excess and any additional excess that applies to your likely driver and repair choice.
GIG Gulf's public plan table shows why this method matters. Its displayed Prestige and Perfect plans differ in agency-repair years, medical expenses, personal injury and optional services. Liva's official car page lists three years of agency repair for new cars and a courtesy car of up to seven days on its stated product. Takaful International's motor page lists vehicle-replacement durations of 8, 10 or 15 days depending on the selection. These are provider examples, so confirm the benefit in the issued schedule.
06Agency repair, approved garage, excess and depreciation
Agency repair means the policy allows repair through the authorised dealer body shop under the stated conditions. It is usually limited by vehicle age, plan or an endorsement. Approved-garage repair sends the car to a repairer in the insurer's network. Neither phrase tells you who pays for parts depreciation, betterment or an upgrade in repair choice.
GIG Gulf's current public comparison lists agency repair for up to five years on one displayed plan and up to three years on another. Its Motor Perfect handbook explains that a policyholder who chooses agency repair when it is not covered may bear 50% of the labour cost. New India's official FAQ says its comprehensive cover provides agency repair for up to three years and that older vehicles use an approved garage, with agency repair potentially involving a depreciation or labour contribution. Those rules belong to the cited products and must not be assumed for another policy.
Before paying, ask the insurer to answer these questions in writing:
- How many years of agency repair does this quote include?
- Which garages are in the approved network for this vehicle?
- What compulsory and additional excesses can apply?
- Can depreciation or betterment be deducted for parts?
- Who authorises repairs, and can work start before approval?
- How is a total loss valued, and what documents are required?
The CBB's compulsory-policy resolution and public insurer wordings contain detailed third-party repair and settlement rules. For your own-car claim, the comprehensive schedule and wording control the result.
If a named driver’s licence also needs renewal, use the driving licence renewal guide and check the policy’s driver conditions separately.
07Car-insurance claim process in Bahrain
- Deal with safety and injuries first. The official GDT reporting flow tells users to call the Traffic Inquiry Centre on 199 when an accident involves injuries. Use emergency services when the situation requires them.
- Record the scene safely. Photograph the vehicles, damage, number plates and wider road position if it is safe. Do not put yourself or other road users at risk.
- Use the official accident route. Bahrain's settled damage-only accident service covers accidents with vehicle damage and no injuries. The reporter selects the affected or at-fault driver, enters the details and attaches photos. The at-fault driver completes the acknowledgement when required.
- Save the report number. The government service sends the registered report number to the parties. The national portal also provides a service to inquire about an electronic traffic report.
- Notify the correct insurer. A comprehensive policyholder normally contacts their own insurer under that contract. For a third-party vehicle-damage claim, the insurer of the at-fault vehicle is central to the compulsory claim. Follow the policy and insurer instructions.
- Submit the claim file. New India's official motor page lists the CPR, vehicle registration, driving licence, insurance document, accident report and photos among its claim documents. Other insurers may request more.
- Wait for inspection and authority. The insurer may inspect the car, appoint a garage or request an estimate. Do not authorise repairs until the insurer confirms the process if you expect it to pay.
- Keep a timeline. Save the claim number, submissions, inspection date, approval, repair updates and settlement offer. Written records make a later review or complaint much easier.
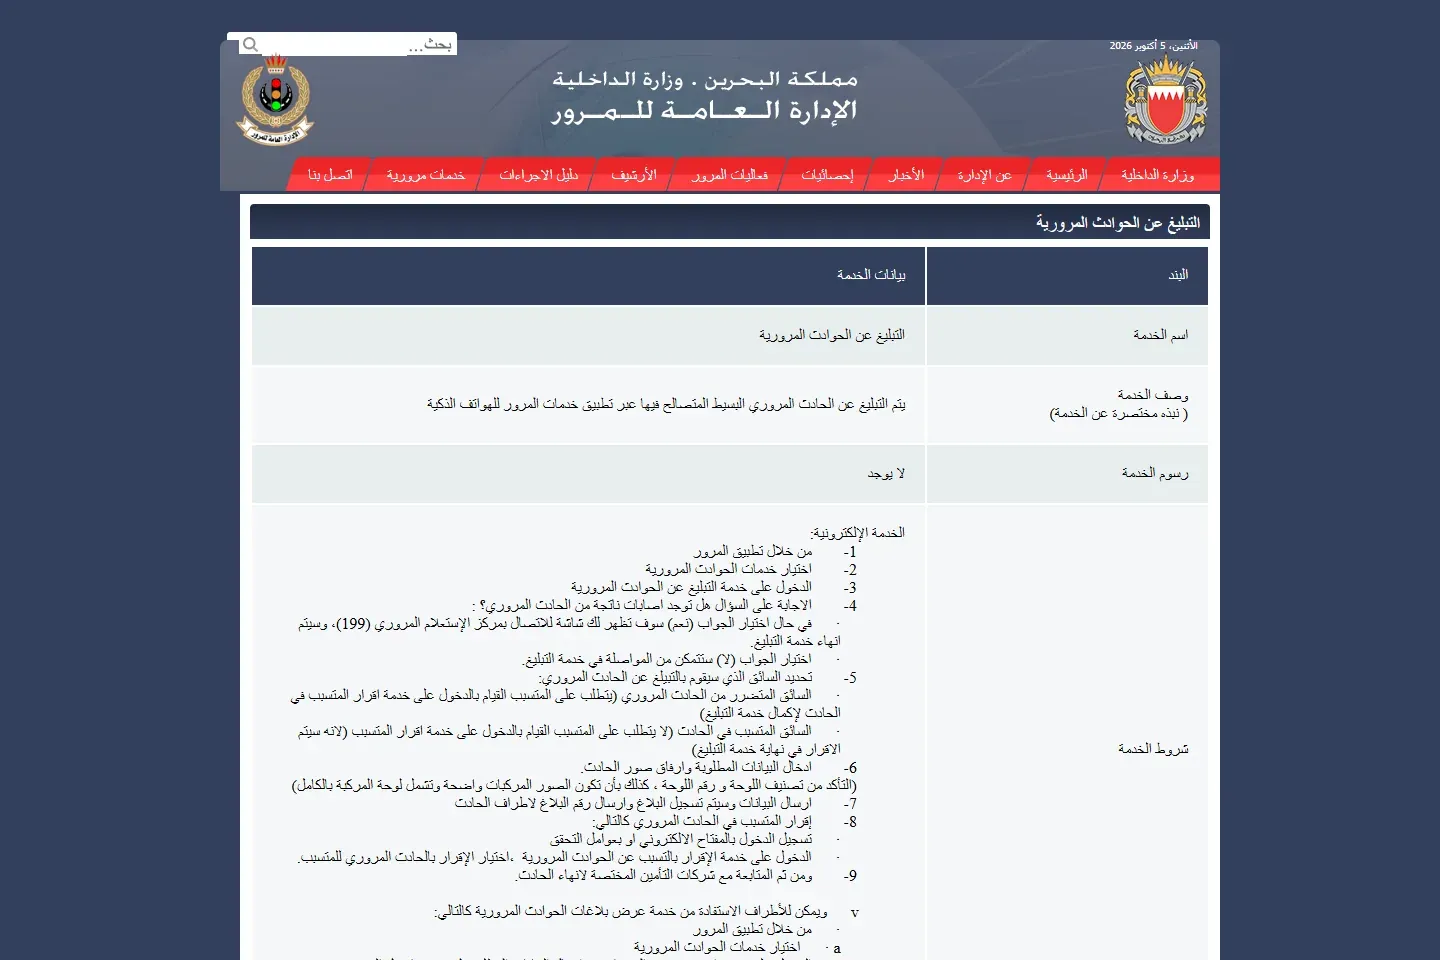
The printable GDT agreed-upon accident form says photos should show the accident from all sides and lists the vehicle ownership card, insurance policy and driving licence among the documents attached when the form is submitted. The dedicated Bahrain accident-report and insurance-claim guide walks through the reporting screens and claim handoff.
08Renew the insurance before vehicle registration
Start with the current certificate and renewal notice. Confirm the legal insurer, vehicle and plate details, expiry date, current insured value, cover type, repair basis, drivers, no-claims position, excesses and optional benefits. A renewal can change both price and terms.
After payment, save the new certificate and schedule. Check that the policy starts when the old one ends and provides the full year required by the GDT renewal service. Then complete any inspection, clear contraventions and submit the registration renewal.
Use the general car-insurance renewal guide for the full sequence. Provider-specific guides cover Solidarity renewal, Bahrain Kuwait Insurance renewal, Takaful International renewal and Arabia Insurance renewal. Those pages keep the brand transaction separate from the broader comparison intent of this pillar.
09What to do when a policy, repair or claim goes wrong
If the policy is missing from the registration flow, first compare the certificate's plate, chassis, start date and policyholder information with the vehicle record. Send the insurer the receipt and certificate and ask it to confirm that the policy was issued correctly. The insurance-status guide keeps this narrow problem separate from buying or renewal.
For a disputed claim, ask the insurer for its decision and the policy clause in writing. Build one file containing the schedule, wording, accident report, photos, claim submission, repair estimates, correspondence and decision. The rejected-claim guide explains how to test the reason against the contract.
The CBB complaint form is an escalation route after the complaint has first been raised with the financial institution. Use the CBB insurance-complaint guide to assemble the chronology and evidence. A complaint is stronger when it identifies the disputed decision, policy clause, requested remedy and insurer's final response.
10Car-insurance questions people ask in Bahrain
Is car insurance mandatory in Bahrain?
Yes. Third-party motor liability is the minimum cover for a registered vehicle. The compulsory wording is tied to CBB Resolution No. 23 of 2016, and GDT requires a full year of insurance for vehicle-registration renewal. See the official resolution and GDT renewal page.
How much is third-party car insurance in Bahrain?
The CBB schedule checked 5 October 2026 showed maximum annual private-car premiums of BHD 50, 59, 71 and 83 across four engine-capacity bands. Use the official CBB calculator because vehicle category and permitted adjustments can affect the figure.
How much is comprehensive car insurance?
There is no official universal price. The quote depends on the vehicle, insured value, driver information, claims record, repair basis, excess and selected benefits. Compare written quotes on identical inputs.
What is the cheapest legal cover?
Third-party liability is the minimum cover, but the cheapest valid quote still needs to match the vehicle and driver information and come from a CBB-licensed insurer. The cheap car-insurance guide shows how to compare cost without removing a benefit you need.
Can family members drive my insured car?
Only rely on the answer in your schedule and wording. Ask whether the policy restricts drivers by name, age, licence duration or use, and whether an additional excess applies. GIG's policy handbooks, for example, define the policy through the schedule, certificate, application and endorsements.
Does Bahrain car insurance cover Saudi Arabia or the GCC?
Some comprehensive plans include or sell a territorial extension, and causeway insurance serves separate cross-border situations. Check the countries, cover sections and dates in writing. The government portal lists United Insurance Company services for causeway cover.
Do I need an accident report for a claim?
Insurers generally require the official accident record or report number for a motor claim. Use Bahrain's official damage-only accident-reporting service where eligible, or contact GDT on 199 when the government flow directs you to do so. Follow the insurer's document checklist.
What is no-claims discount?
It is a discount or rating benefit based on claim-free history under the insurer's rules. Ask for the renewal calculation and a no-claims certificate if you plan to move provider. Takaful International publishes a BHD 2.200 fee, including VAT, for a no-claim certificate on its current motor page.
Can I cancel the policy after selling the car?
Ask the insurer for its cancellation requirements and refund calculation. Liva's published motor terms and FAQ wording says evidence such as deregistration, transfer of ownership or alternative insurance may be required before cancelling the compulsory liability section.
11Every Imapro Bahrain motor-insurance guide
Documents, checks, payment and the GDT handoff.
Government insurance, inspection and fee requirements.
What to check when a policy is missing or unclear.
GDT reporting, evidence and insurer submission.
The cover decision and wording differences.
Price checks without hidden reductions in cover.
The insurer-first complaint and escalation file.
Test the reason against the schedule and wording.
Official renewal and registration handoff.
Renew through the provider's official route.
Renew motor takaful and verify the new certificate.
Quick renewal, documents and final checks.
12. Arabic car-insurance terms used in Bahrain
People searching تأمين السيارات, تأمين مركبات or تأمين السيارات البحرين are usually looking for the same first decision covered above: compulsory third-party liability or broader comprehensive cover. Use the current CBB third-party premium schedule, verify the provider in the CBB Licensing Directory, and confirm the government renewal step through GDT.
| Arabic term | Meaning | Guide to use |
|---|---|---|
| تأمين السيارات | Car insurance | This pillar for cover, prices, claims and renewal |
| تأمين ضد الغير | Third-party insurance | Third-party versus comprehensive guide |
| تأمين شامل | Comprehensive insurance | Compare own-damage benefits, excess and repair basis |
| تجديد تأمين السيارة | Renew car insurance | Online renewal guide |
ما الفرق بين التأمين ضد الغير والتأمين الشامل؟
يغطي التأمين ضد الغير المسؤولية تجاه الطرف الآخر وفق الوثيقة، بينما قد يضيف التأمين الشامل تغطية أضرار مركبتك. راجع جدول الوثيقة والتحمل والاستثناءات قبل الدفع.
كيف أتحقق من صلاحية تأمين السيارة؟
راجع شهادة التأمين وبيانات المركبة، ثم استخدم القنوات الرسمية لشركة التأمين وخدمة تجديد تسجيل المركبة لدى الإدارة العامة للمرور.
Browse renewal, claims, quotes and cover guides in the Bahrain motor insurance hub.