Bahrain finance guides
Non-resident bank accounts in Bahrain: what to verify with the bank
By Gaurav Agarwal · Sources checked 6 October 2026
Specific routes exist: BBK Al Hayrat terms include non-residents, while BisB offers GCC onboarding subject to nationality, residence and product conditions. Confirm documents, remote activation, fees and restrictions for your exact situation before applying.
Jump to a section
- 1. Explain your residence and nationality separately
- 2. Use a product-specific eligibility shortlist
- 3. Get the correct identity and address checklist
- 4. Confirm whether the whole process can be completed remotely
- 5. Check charges and service restrictions before funding
- 6. Obtain a clear answer before applying
Some Bahrain bank accounts explicitly accept non-residents, but eligibility depends on the product and applicant. BBK's Al Hayrat terms include individuals of all nationalities who are not resident in Bahrain. BisB advertises a remote route for GCC citizens, with its general terms specifying GCC nationals living in GCC countries. Neither route establishes that every visitor can open any Bahrain account.
Checked 6 October 2026. This guide separates confirmed eligibility from conditions that still need the bank's written answer. If you live in Bahrain and need an everyday resident account, start with the Bahrain account-opening guide.
1. Explain your residence and nationality separately
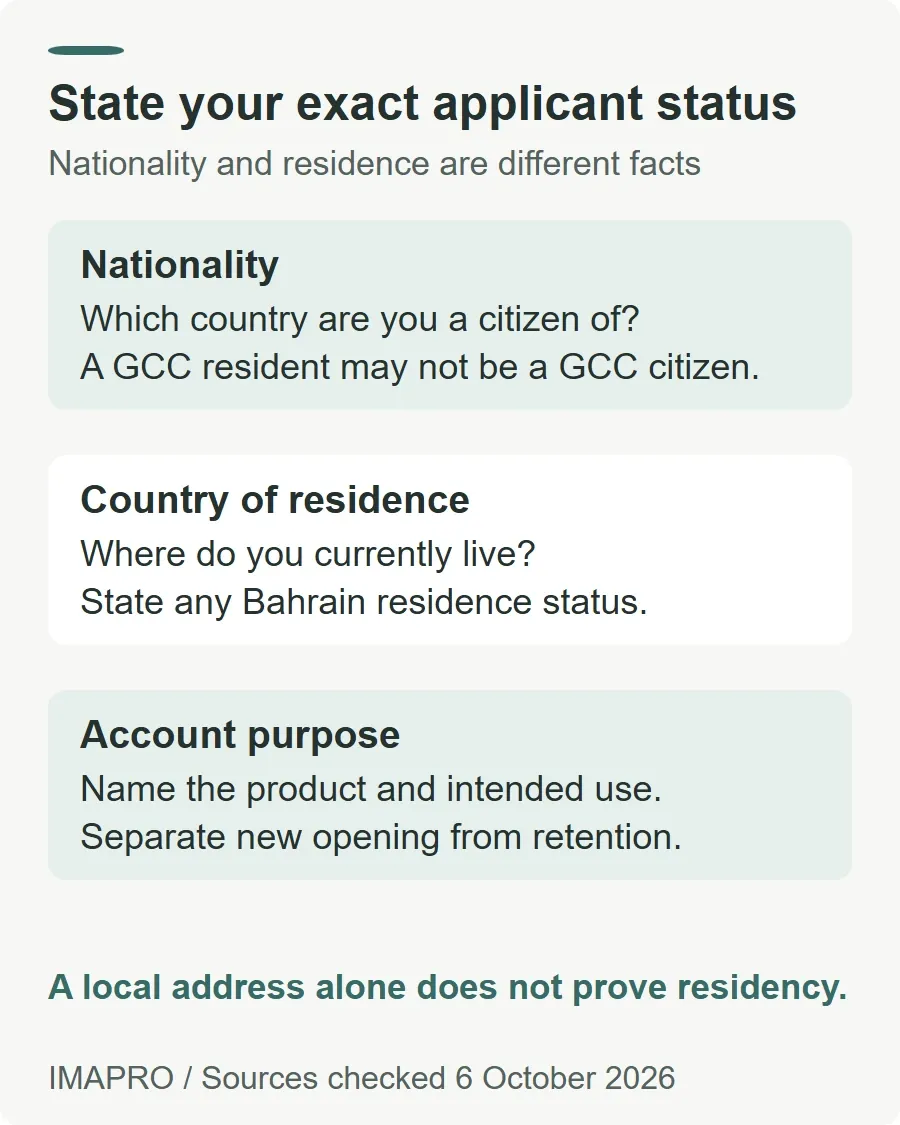
When asking a bank about eligibility, state your nationality, country of residence, whether you hold Bahrain residence documents, and the account's intended use. A non-Bahraini customer may be a Bahrain resident. A person living in Saudi Arabia may be a GCC citizen or a citizen of another country. Those are different application situations.
The distinction matters in the official sources. BisB's GCC route is for citizens, not everyone with a GCC residence permit. In contrast, ila's account-opening FAQ says an applicant must live in Bahrain and be at least 18. Being able to use an existing account abroad does not prove that someone abroad can open a new one.
If you are visiting Bahrain or waiting for residence approval, tell the bank that exact status. Do not describe yourself as a resident merely because you have a local contact address or are physically in the country.
2. Use a product-specific eligibility shortlist
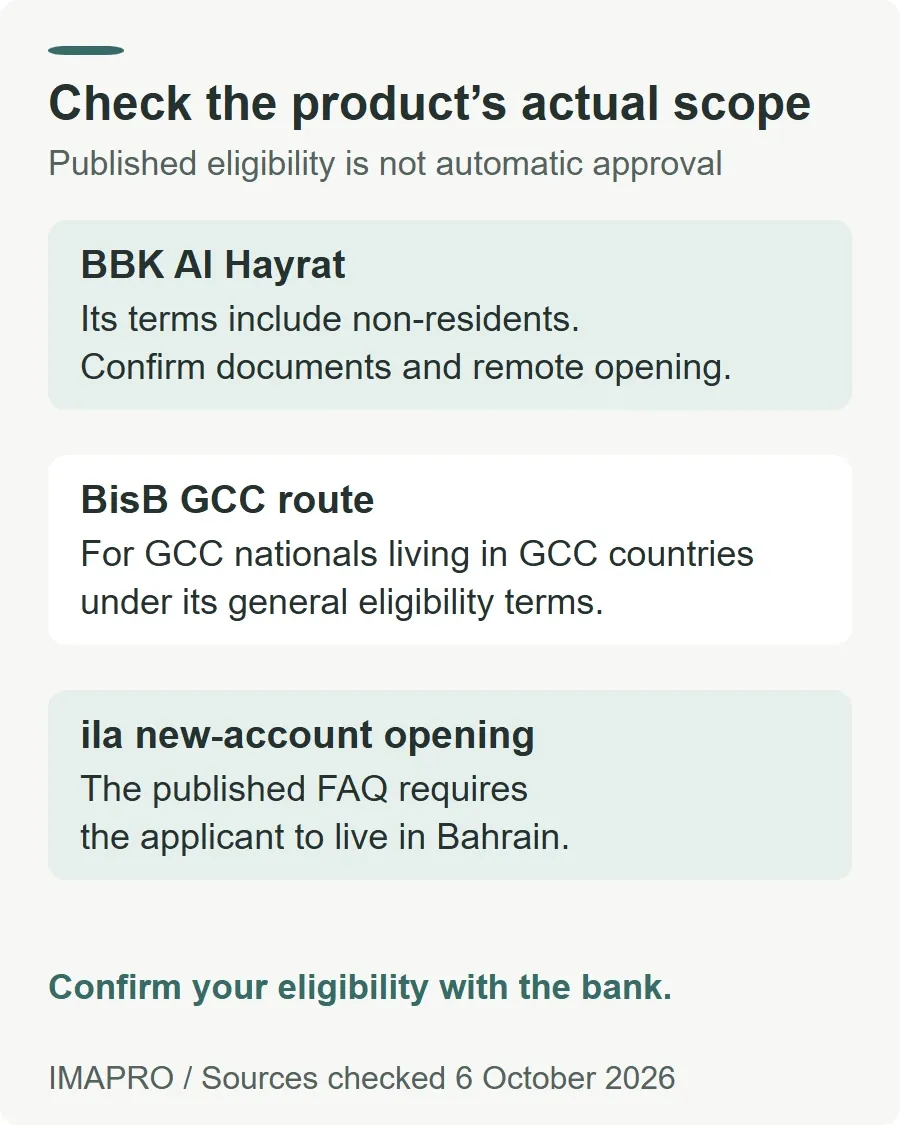
| Route | What is confirmed | What remains to check |
|---|---|---|
| BBK Al Hayrat Savings Account | Section 5.2 of the current linked terms permits individual residents and non-residents of all nationalities above age 18. Section 5.1 specifies an opening deposit of BHD 50 or more. | Accepted non-resident documents, country-specific review, remote-opening availability and the services needed for your intended use. |
| BisB GCC onboarding | The bank advertises online opening without a Bahrain residence requirement. Its general terms specify GCC nationals residing in GCC countries, aged 18 or over, subject to bank conditions. Current accounts have a separate age threshold of 21. | The chosen account, service restrictions and any additional verification. Do not extend this route to a non-GCC citizen living in a GCC country. |
| ila account opening | The FAQ requires living in Bahrain. | It is not a confirmed new-account route for a non-resident under the published FAQ reviewed here. |
Sources: BBK terms, sections 5.1 and 5.2; BisB GCC onboarding; BisB account eligibility terms; and ila FAQs.
BBK's Al Hayrat is a prize-linked savings product. Its terms exclude specified BBK staff, board members and family members, and preserve other account conditions. Eligibility to apply is not unconditional approval or proof that it provides every payment feature you need. This article does not assess prize odds or recommend entering a draw.
Also avoid a common search-result mix-up: BBK's NRI page describes NRE, NRO and related India banking arrangements. “Non-resident Indian” is not the same question as “non-resident of Bahrain”. Confirm the country and legal branch where the account will be held.
3. Get the correct identity and address checklist
For its GCC onboarding route, BisB lists a valid GCC identity card and passport, proof of residence such as a utility bill or rental agreement, and any additional documents requested during the application. Ask which document dates and address formats are accepted for your country.
BBK's official Al Hayrat eligibility guide confirms that section 5 does not provide a complete non-resident document list. Its general terms require information and supporting documents when opening an account and when subsequently requested. A CPR or residence-permit list for a different BBK account should not be presented as Al Hayrat's non-resident checklist.
Before arranging travel or paying for document certification, ask the bank to confirm:
- Which identity documents it accepts for your nationality and residence.
- Which overseas address evidence is acceptable, and how recent it must be.
- Whether originals, certified copies or translations are required.
- What evidence of income, source of funds and intended account activity it needs.
- Which tax-residence declarations apply to your application.
These are questions to resolve, not a universal mandatory-document list. A resident-status box on an application form is not proof that the product accepts non-resident applicants.
4. Confirm whether the whole process can be completed remotely
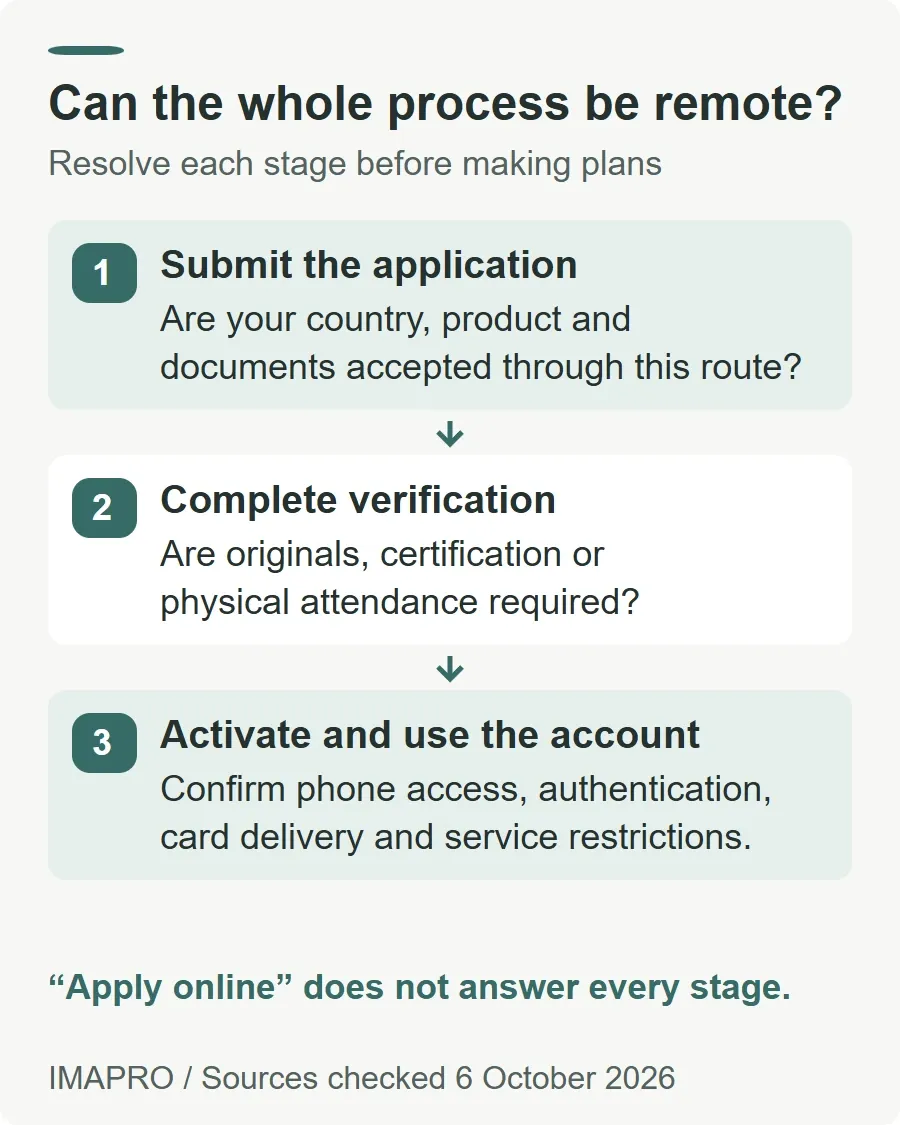
BisB's published GCC route uses its mobile app: select the signup option, provide the requested information and complete verification. The page says no branch visit is needed. Treat its opening-time language as a description subject to document verification, not a guaranteed approval deadline.
For BBK Al Hayrat, the reviewed terms and bank eligibility guide do not establish a complete remote-opening process for customers outside Bahrain. Obtain an answer for your country and documents before assuming that a general app-opening advertisement applies to you.
Separate these questions: can you submit remotely, can the bank verify you remotely, and can you activate and use the account from abroad? Ask about the accepted phone number, authentication, card delivery and any step that requires physical attendance. Use the bank's own website to reach its app or contact channel.
5. Check charges and service restrictions before funding
BisB's GCC page states that opening the account carries no fee, while account and service charges can still apply. BBK's BHD 50 Al Hayrat opening deposit is money placed in the account, not an account-opening fee. Neither statement establishes the total cost of maintaining or using the account.
Request the tariff for the precise product and ask about minimum-balance charges, dormancy, international transfers, foreign-currency conversion, card use and closing the account from abroad. Keep an unanswered fee marked as unknown rather than zero.
Resolve the BisB service discrepancy in writing. Its GCC promotional FAQ says customers can apply for credit cards or financing after opening. Its current general terms list finance and credit-card applications among exclusions for GCC customers, alongside certain other services. Both were reviewed on 6 October. This guide therefore does not promise those facilities. Ask which restrictions govern your exact account and status.
BisB's terms also require updated customer documents and allow account restrictions if required information is not supplied. Ask how you will update an expired ID or changed address while abroad. If you are comparing Islamic product structures as well as eligibility, see the Islamic banking guide.
6. Obtain a clear answer before applying
Use a short request that lets the bank assess the actual situation:
I am a citizen of [country] and currently reside in [country]. I do not hold Bahrain residence status. I want a personal [account type] for [purpose]. Please confirm whether this product accepts my circumstances, the required documents, whether all opening and activation steps can be completed remotely, and the applicable fees and service restrictions.
This is a blank enquiry template, not an application or a bank-approved checklist. Add accurate details privately through the bank's verified channel. If you already have an account and are leaving Bahrain, ask about retaining or changing that existing account separately from eligibility for a new one.
Save the product name, bank response, applicable terms and tariff together. A useful answer identifies the route and its conditions; a generic “apply online” response does not resolve whether the bank accepts your non-resident circumstances.
General information only. This guide is not personal financial, legal or tax advice and does not guarantee bank approval. Confirm current eligibility and account conditions directly with the provider before committing funds.