Bahrain finance guides
Close a bank account in Bahrain: balances, linked payments and proof
By Gaurav Agarwal · Sources checked 6 October 2026
Check outstanding obligations and linked payments, submit the bank's required closure instruction, arrange the remaining balance and obtain written confirmation. Notice, documents, charges and remote access depend on the bank and product.
Jump to a section
To close a bank account in Bahrain, first check outstanding obligations and linked payments, then submit the bank's required closure instruction, arrange the remaining balance and obtain written confirmation. Withdrawing the money, deleting an app or leaving Bahrain does not establish that the account has closed.
Official sources checked: 6 October 2026. This is a departure and account-switching checklist for personal banking. The examples below are bank-specific; they do not establish a single notice period, fee or remote closure process for every Bahrain account.
1. Specify exactly what you want to close
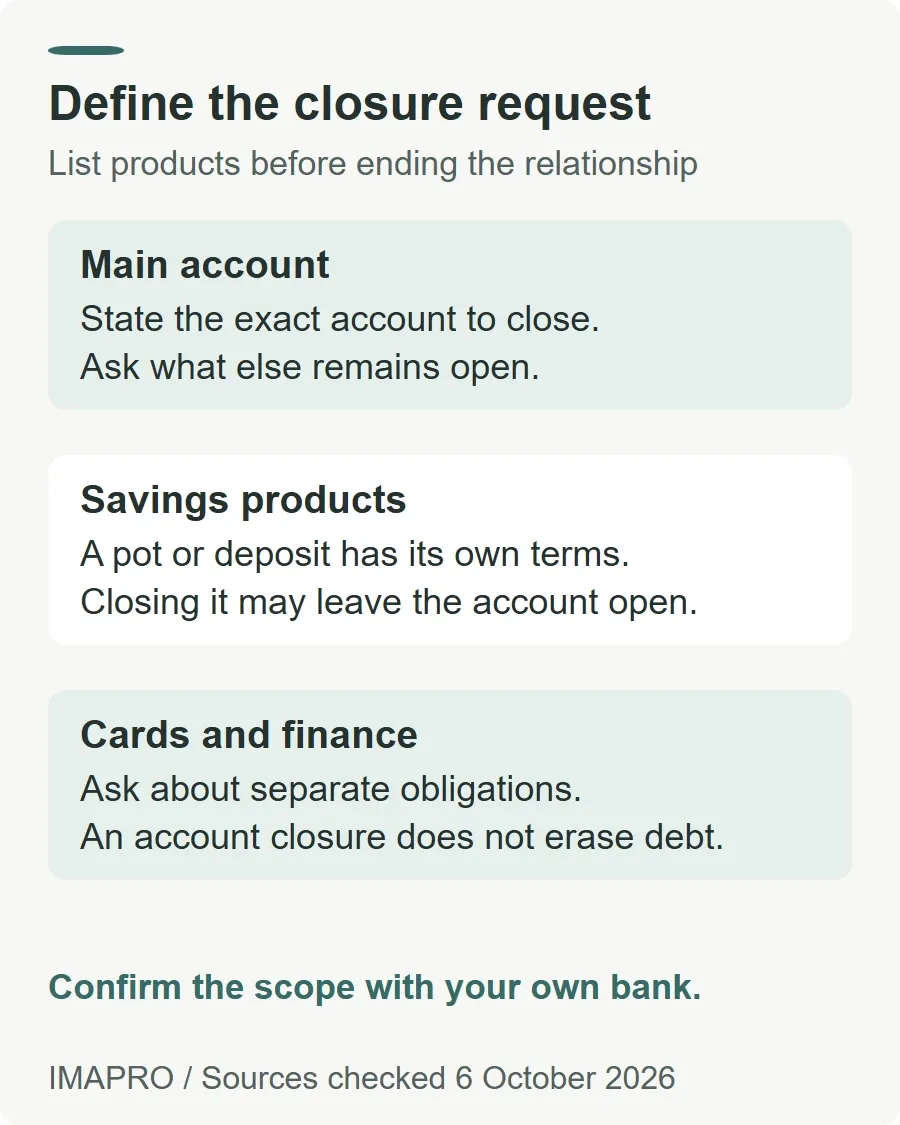
List the accounts and products you hold with the bank: the main BHD account, foreign-currency accounts, savings pots, deposits, debit cards, credit cards and finance facilities. Tell the bank whether you want to close one product or end the full relationship. Ask it to identify anything that will remain open.
For example, ila's savings FAQs describe closing a Hassala through its More Options menu after moving the remaining funds to the current account. Savings+ closure is requested through the contact centre, with the remaining balance and accrued interest transferred to the applicable currency account. Neither instruction by itself closes the main banking relationship.
Check that an online form belongs to your current bank. HSBC's Bahrain announcement confirms its retail banking business transferred to BBK on 27 November 2025. Former retail customers should follow current BBK guidance rather than assume an old HSBC closure form still provides the correct route.
If switching banks, make sure the replacement account is usable before rerouting essential payments. The Bahrain bank-account opening guide covers that separate application task.
2. Resolve liabilities and pending transactions
Ask for a list of unsettled items before emptying the account. Include card transactions awaiting posting, overdrafts, finance repayments, fees, outstanding cheques and any deposit pledged as security. Request the amount and date needed to settle each item, rather than relying only on the displayed available balance.
Under ila's account terms, section 21, written notice can be given to close accounts, but closure follows payment of account-related charges and liabilities. Section 17 also warns that international correspondent charges may arrive later and be debited separately. Ask how any pending transfer costs will be handled.
BisB's general terms state that an account containing an agreed pledged deposit remains open until the secured facility is fully settled. Closing a deposit account should therefore not be treated as a way to cancel a financing obligation.
If a fixed deposit must be broken, ask for its separate early-withdrawal calculation. The Bahrain fixed-deposit guide explains why the amount returned can differ from the original maturity expectation.
3. Redirect salary, bills and recurring payments
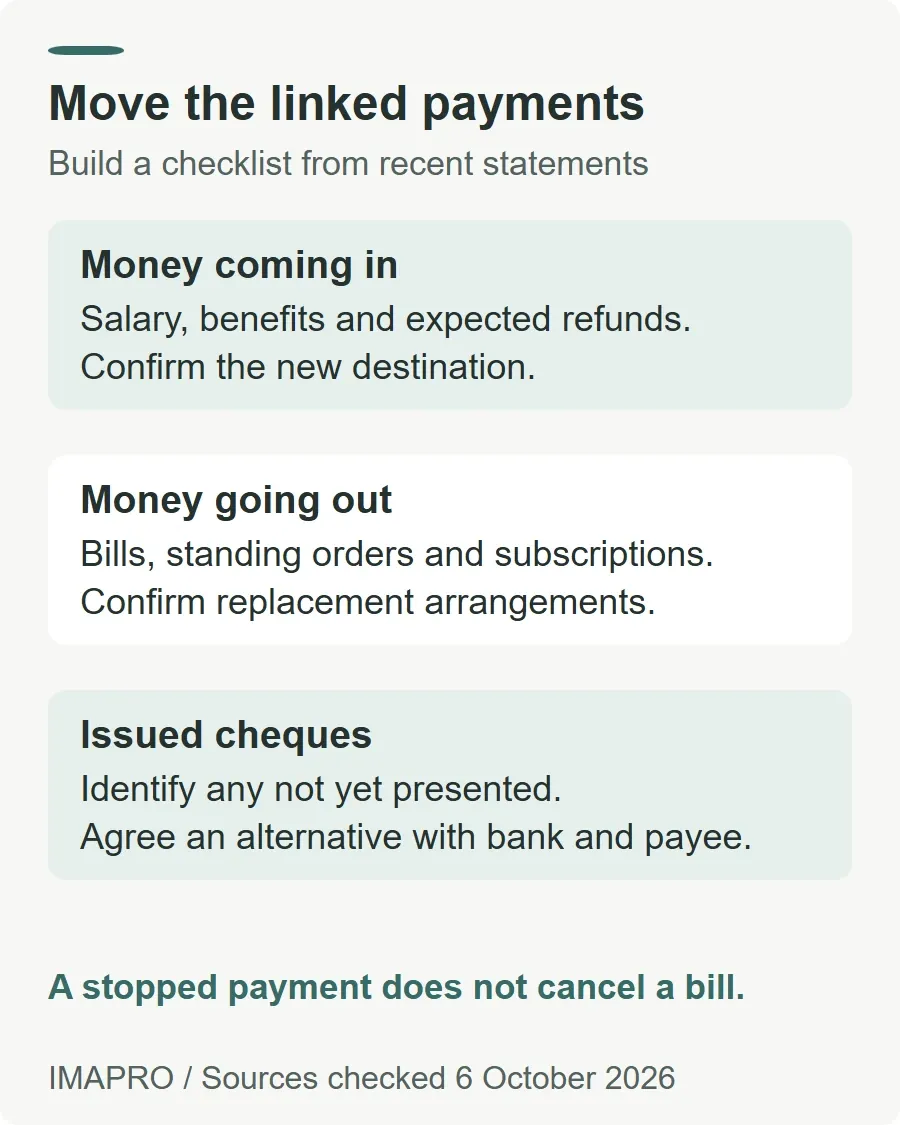
Review recent statements and make a payment list before sending the final closure request. Use it to record what has moved, what has stopped and what still needs a response.
| Item | Action to confirm |
|---|---|
| Salary, final salary and employment benefits | Ask the payer which account will receive any remaining payment and whether its change deadline has passed. |
| Utility bills and standing orders | Arrange the replacement payment method and ask the bank to confirm cancellation of the old instruction. |
| Card subscriptions and recurring purchases | Update or cancel the arrangement with the merchant and check the next billing date. |
| Issued cheques | Identify any not yet presented and arrange an agreed alternative with the payee and bank. |
| Expected refunds and incoming transfers | Ask the sender and bank how payment should be redirected before closure. |
NBB's account terms, clause 16.4, require cancellation of payments into and out of the account and replacement of issued cheques with alternative payment methods. These are explicit NBB terms; the table adds practical questions to organize the handover.
Keep enough access to check that replacement arrangements work. Do not treat cancellation of a payment instruction as cancellation of the underlying rent, bill or other agreement. Resolve any uncertain obligation with the relevant provider.
4. Confirm the accepted request, notice and cost
Contact the bank through its official app, website or published service channel. Ask for the closure form or instruction format for the exact product. Confirm identity requirements, necessary signatures, any original documents and whether a branch visit is required. A signed email should not be assumed acceptable until the bank confirms the channel.
NBB's clause 16.3 specifies ten days' prior written notice from the customer, provided no liabilities are outstanding. This is a notice requirement, not a guaranteed completion time. Its clause 12.4 requires the written request of all holders for joint-account closure.
Ask for a dated cost breakdown covering the closure itself, any required document, residual transfer, foreign-exchange conversion and separate product settlement. No universal closure fee is established here. A missing fee on a short webpage is not proof that the whole exit is free.
If you have already left Bahrain, ask whether the bank accepts an authenticated remote instruction, requires a service-centre visit or permits an authorized representative. Confirm any certification requirements before paying for documents. The reviewed sources do not establish one complete overseas closure route applicable to every customer.
5. Settle the remaining balance and keep closure proof
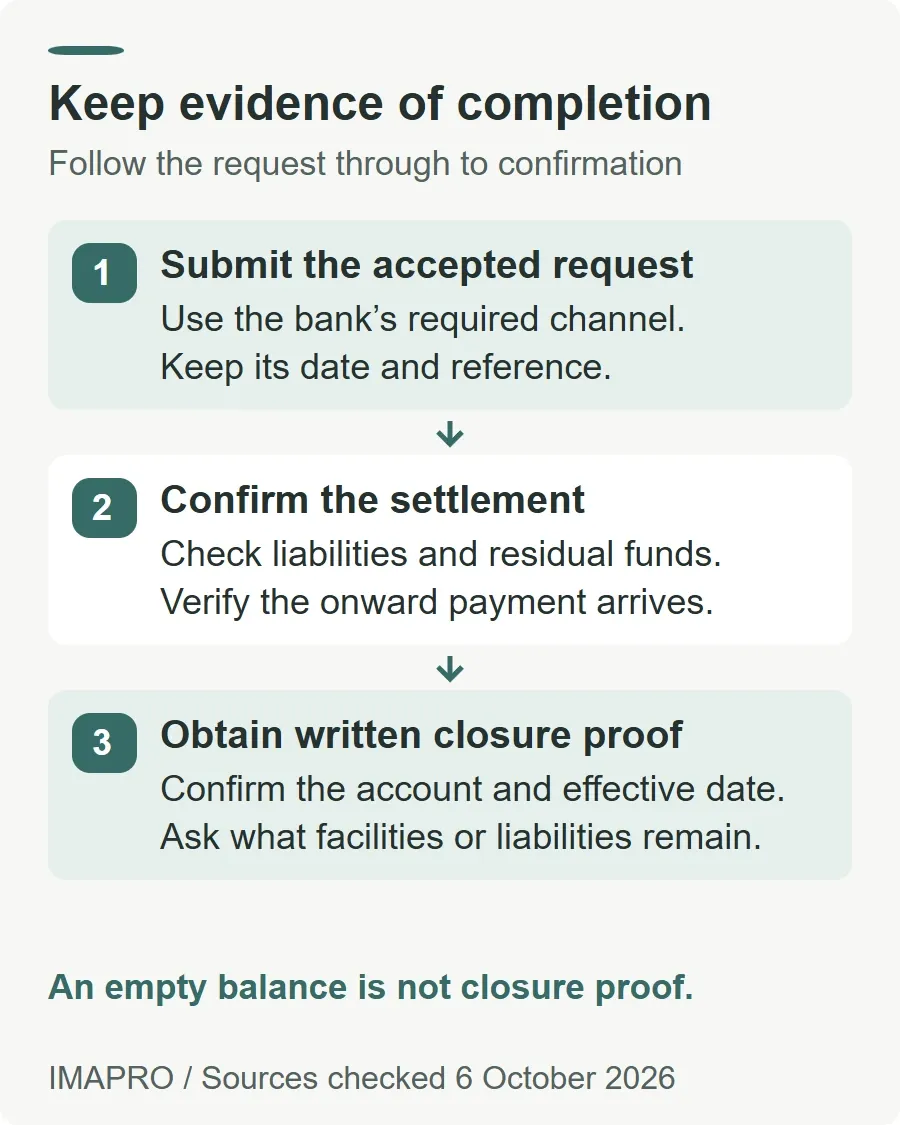
Give the bank a verified destination for residual funds and confirm the currency, deductions and payment method. Ask what happens to pending refunds and any interest or profit not yet credited. Do not promise yourself the last displayed balance without a settlement calculation.
NBB's clause 16.5 provides for returning funds at the customer's cost, subject to its rights and no outstanding liabilities. Its terms also require unused cheques and related cards to be returned. BisB instead instructs customers to destroy cards and chequebooks on closure in its closure terms. Follow your own bank's instructions.
Request a final statement and written confirmation showing which account or relationship closed and the effective date. Ask whether any separate liability or facility remains. A closure acknowledgement and a clearance or no-liability certificate answer different questions; request the document you actually need.
Keep the request, acknowledgement, settlement calculation, outgoing transfer proof and final confirmation securely. Check that the residual payment reached its destination. If the bank says the request is pending, ask for the unresolved item and next action in writing.
6. Follow up on delays instead of abandoning the account
Inactivity is not a reliable closure plan. BBK's current general terms, section 6, distinguish dormant accounts from closed accounts and allow applicable charges on dormant credit balances. Do not assume a small balance will disappear cleanly or that deleting banking access ends the contract.
If closure stalls, send a concise follow-up with the request date and reference, the bank's previous answer and the exact unresolved issue. Ask whether the obstacle is identification, notice, a pending payment, security over funds or an unsettled charge. Use the bank's formal complaint channel if ordinary follow-up does not resolve it.
The CBB consumer-information page explains its role in reviewing complaints for possible regulatory breaches and links to the applicable complaint procedure. Follow that route with supporting records if escalation is needed. It does not guarantee a particular closure date or refund outcome.
General information only. This guide is not personal financial or legal advice. Confirm current terms with the bank, especially if the account is restricted, pledged, disputed or subject to a court instruction.