Official sources checked
Health Insurance for Expats in Bahrain: Local and International Cover
By Gaurav Agarwal · Sources checked 6 October 2026
Separate three questions: who must arrange and pay for the cover, which Bahrain providers you can use, and whether you need treatment outside Bahrain. The Bahrain Health Insurance Law sets employer and dependant responsibilities, while the issued plan decides the network, benefits, cost sharing and claims.
01Start with employment status and sponsor records
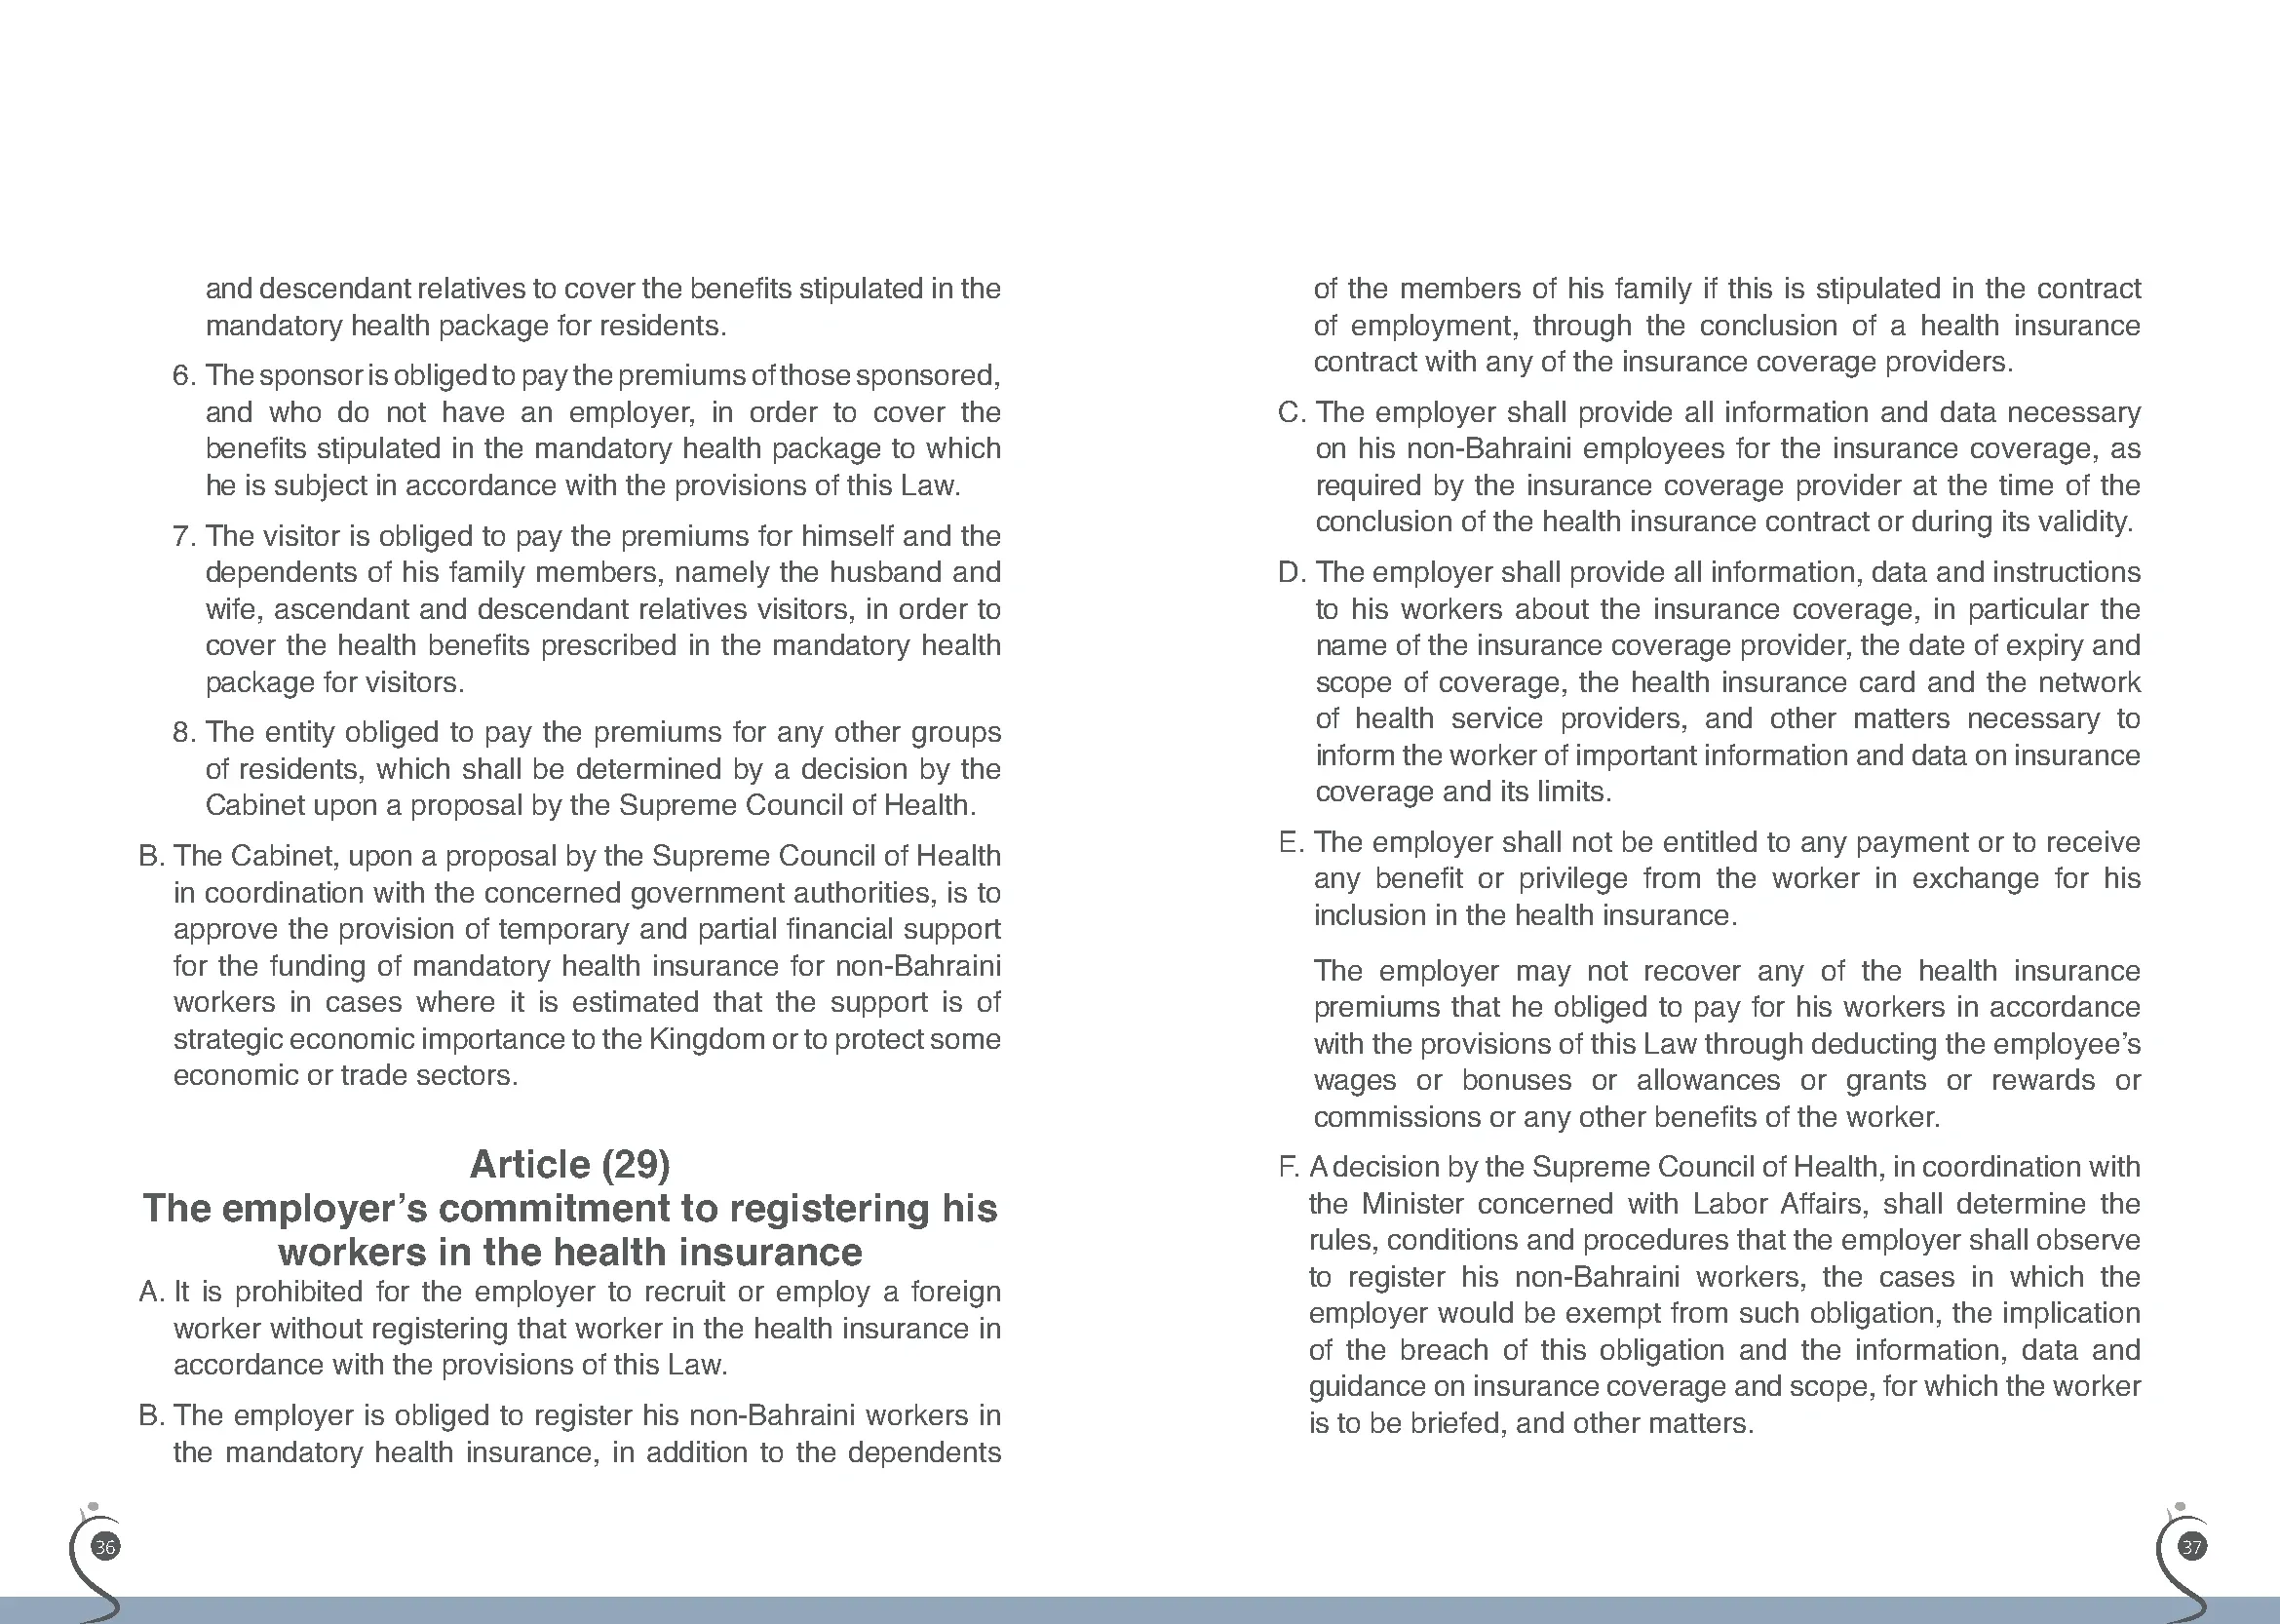
Article 29 of Bahrain's Health Insurance Law addresses contributions for non-Bahraini workers and their dependants. Read the official text and the current implementation information on Sehati, then check the employment contract and the policy issued for the worker.
Do not confuse insurance with the separate expatriate medical examination used for work or residency processes. A medical-fitness result does not show your hospital network or treatment benefits.
The medical-fitness result guide covers the separate examination record, not insurance cover.
Use the Sehati law and enrolment guide to separate the legal framework from your actual policy record.
02Local plan or international plan?
| Question | Local Bahrain plan | International plan |
|---|---|---|
| Primary use | Routine and hospital care in a Bahrain network | Multi-country residence or treatment needs |
| Direct billing | Often tied to the named local network | May vary by country and provider |
| Claims | Local approval and reimbursement rules | More reimbursement and overseas evidence may apply |
| Geography | Bahrain, with stated extensions if any | Regional or worldwide area, sometimes excluding countries |
| Price drivers | Network, age, benefits and cost sharing | Geography, age, deductible, benefits and underwriting |
| Regulatory check | Verify the Bahrain insurer in the CBB register | Identify the issuing entity and where it is regulated |
A worldwide label can still have country exclusions, treatment restrictions or a high deductible. A local plan can be better for daily direct billing if the right doctors and hospitals are in network.
03Build the plan around real providers and medicines
- List the clinics, hospitals, specialists and pharmacies you use.
- Check them against the exact plan network.
- List regular medicines and ask about the formulary and approval.
- Record copays for GP, specialist, pharmacy and diagnostics.
- Check chronic-condition, maternity, dental, optical and mental-health terms.
- Ask what happens during travel or temporary work outside Bahrain.
Recheck network participation before planned treatment. An insurer brand can operate several networks with different access and cost sharing.
04Employer cover, dependants and upgrades
Obtain the employer policy summary or member guide and identify who is enrolled, the effective date, network, annual limit and cost sharing. For a spouse or child, confirm enrolment and start date rather than assuming the worker's card extends automatically.
If the employer plan is too narrow, compare an upgrade or separate plan only after checking coordination rules. Ask which plan pays first, whether duplicate benefits are allowed and how pre-existing conditions are treated when moving between plans.
Use the family health-insurance checklist before assuming a workplace policy enrols a spouse or child.
05What changes an expat medical-insurance quote
Age, family size, network, annual limit, deductible, copay, geography, maternity, dental, optical, chronic-condition terms and underwriting can change a quote. Record every variable and the quote date. Do not present one person's premium as a Bahrain price range.
For a fair comparison, request the same deductible, geography and benefit set from each provider. Use the health-insurer comparison worksheet once it is live, and keep the quote assumptions.
Use the medical-insurance quote comparison to hold benefits and cost sharing constant.
06Using the plan and making a claim
For direct billing, show the correct card and identification, then confirm eligibility, network, referral and preauthorisation. For reimbursement, keep the signed form, medical report, prescription, itemised invoices, payment receipts, test results and bank details requested by the policy.
When employment ends or changes, ask the employer and insurer for the exact coverage end date and continuation options in writing. Do not wait until treatment is needed to discover that access ended.
07Questions expats ask about health insurance
Must an employer provide health cover to an expat worker?
Read Article 29 of the official law and current Sehati implementation information, then verify the worker's issued policy and effective date.
Are dependants automatically covered?
No assumption is safe. Check the law, contract, enrolment record and policy schedule for each dependant.
Is international insurance better?
It is useful when you need wider geography, but compare direct billing, deductible, exclusions and overseas claims. A suitable local network may work better for routine Bahrain care.
Does the medical fitness test provide health insurance?
No. Fitness screening and treatment insurance are separate processes.
09Separate four systems that expats often confuse
A work-permit medical examination is not a health-insurance policy. The Ministry of Health expatriate-checkup page describes the fitness process and authorised facilities. The Health Insurance Law and Sehati portal cover a different system. Employer cover, individual private cover and an international plan can each add separate terms.
| Item | Purpose | What it does not prove |
|---|---|---|
| Medical fitness result | Work-permit health screening | Private treatment cover |
| Employer insurance card | Access under the employer plan | Cover for every dependant or overseas treatment |
| Individual local policy | Benefits under a Bahrain-issued plan | Worldwide portability |
| International medical plan | Wider geography depending on terms | Compliance with every local employment requirement |
10Local versus international cover on the same facts
The Supreme Council of Health Sehati publication describes mandatory and private package concepts for residents. For extra cover, compare a local product such as the GIG Gulf Bahrain health page with a wider product such as the Solidarity Bupa Global brochure. These examples show different positioning, not a ranking.
| Decision row | Local plan question | International plan question |
|---|---|---|
| Geography | Which Bahrain and GCC providers are covered? | Which countries and elective-treatment zones apply? |
| Direct billing | Which local hospitals use the card? | Which overseas providers offer cashless access? |
| Reimbursement | What applies outside the local network? | What currency, forms and time limits apply? |
| Evacuation | Is it included or unnecessary for the plan? | Who decides medical necessity and destination? |
| Leaving Bahrain | Does cover end with employment or residence? | Can the policy move with the insured person? |
11Worked example: employer cover with a family gap
Hypothetical example: an employee has an employer card covering local inpatient and outpatient treatment. The spouse and child are not listed, and the family regularly travels to its home country. The family should not replace the employee plan blindly.
- Obtain the employer certificate and benefit schedule.
- Confirm whether dependants can be added and who pays the contribution.
- List required hospitals, medicines, maternity needs and travel geography.
- Request local-family and international-family quotes using the same ages and medical disclosures.
- Compare waiting periods, pre-existing-condition decisions, copays, annual limits and network access.
- Coordinate start and end dates so nobody is left unintentionally uninsured.
Verify every insurer in the CBB Licensing Directory. Keep a copy of the application because incomplete medical disclosure can become central to a later claim dispute.
Does the work-permit medical test give health insurance?
No. It is a fitness-screening process. Ask separately for the insurance certificate and benefits.
Must an employer cover dependants?
Check the employment contract and current legal requirements. Do not infer dependant benefits from the employee card.
Can I add international cover above an employer plan?
Yes, products may be available, but coordinate benefits and disclose existing cover.
What happens when I change jobs?
Ask both employers for exact policy end and start dates and read the job-change continuity guide.
If a contractual complaint remains unresolved after the insurer's response, use the CBB complaint route.
12Prepare one quote pack for every insurer
Use the same facts for every quote: ages, Bahrain residence status, employment status, dependants, medical history, current medicines, required providers, preferred geography and requested benefits. Different inputs produce comparisons that look precise but are not comparable.
| Information | Why it matters |
|---|---|
| Age and family composition | Defines who must be underwritten |
| Medical disclosure | Affects acceptance, exclusions and pricing |
| Provider list | Tests the exact network |
| Travel pattern | Defines useful geographic cover |
| Employer benefits | Prevents unnecessary duplication and reveals gaps |
Ask the insurer to identify any unanswered question before you pay. Save the completed proposal and final schedule, because a verbal summary cannot prove what was disclosed or accepted.