Bahrain finance guides
Savings accounts in Bahrain: access, returns and fees
By Gaurav Agarwal · Sources checked 6 October 2026
Compare access, how interest or profit is calculated and paid, qualifying balances, charges and protection for the exact savings product. Prize eligibility is not a guaranteed return, and contribution plans can have early-exit conditions.
Jump to a section
Compare a savings account in Bahrain by how you can withdraw money, how interest or profit is calculated, and which balance conditions and charges apply. A familiar bank name or a large advertised prize does not answer those questions. An everyday savings account, a separate app savings pot and a contribution plan can have very different access rules.
Official sources checked: 6 October 2026. This guide uses selected products to explain those differences. It does not rank banks or quote an unverified current interest rate.
1. Decide how soon you may need the savings
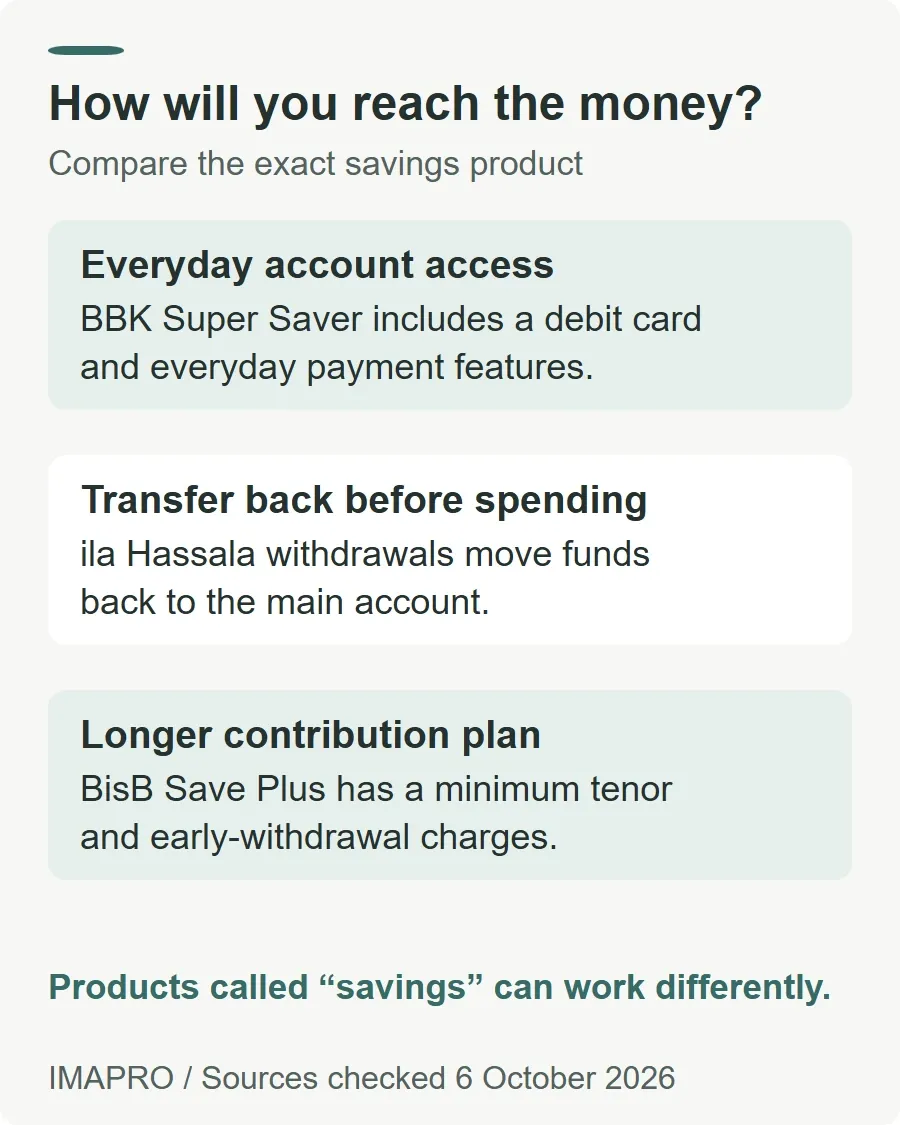
Start with the job for the money. Funds for an unexpected bill need a practical route back to your spending account. Money for a known later date may allow different conditions. Check whether withdrawals use a debit card, require an internal transfer, or depend on a branch request.
BBK's Super Saver account combines interest with a debit card, salary transfers and everyday payments. Its page specifies BHD 20 to open and maintain the account. This is different from a savings pot that first needs to transfer money into another account before spending.
For example, ila's Hassala FAQ says withdrawals move money back to the main account. Its separate Savings+ product allows transfers without withdrawal penalties but has no dedicated debit card. Those distinctions matter when you need to pay, even though both products let you access funds.
Do not treat a longer contribution plan as an interchangeable place for immediate-access money. Read its early-exit terms before relying on the word “savings”. If you instead intend to commit money until a maturity date, obtain a separate fixed-deposit quotation and compare its breakage terms.
2. Separate the rate, calculation method and payment date
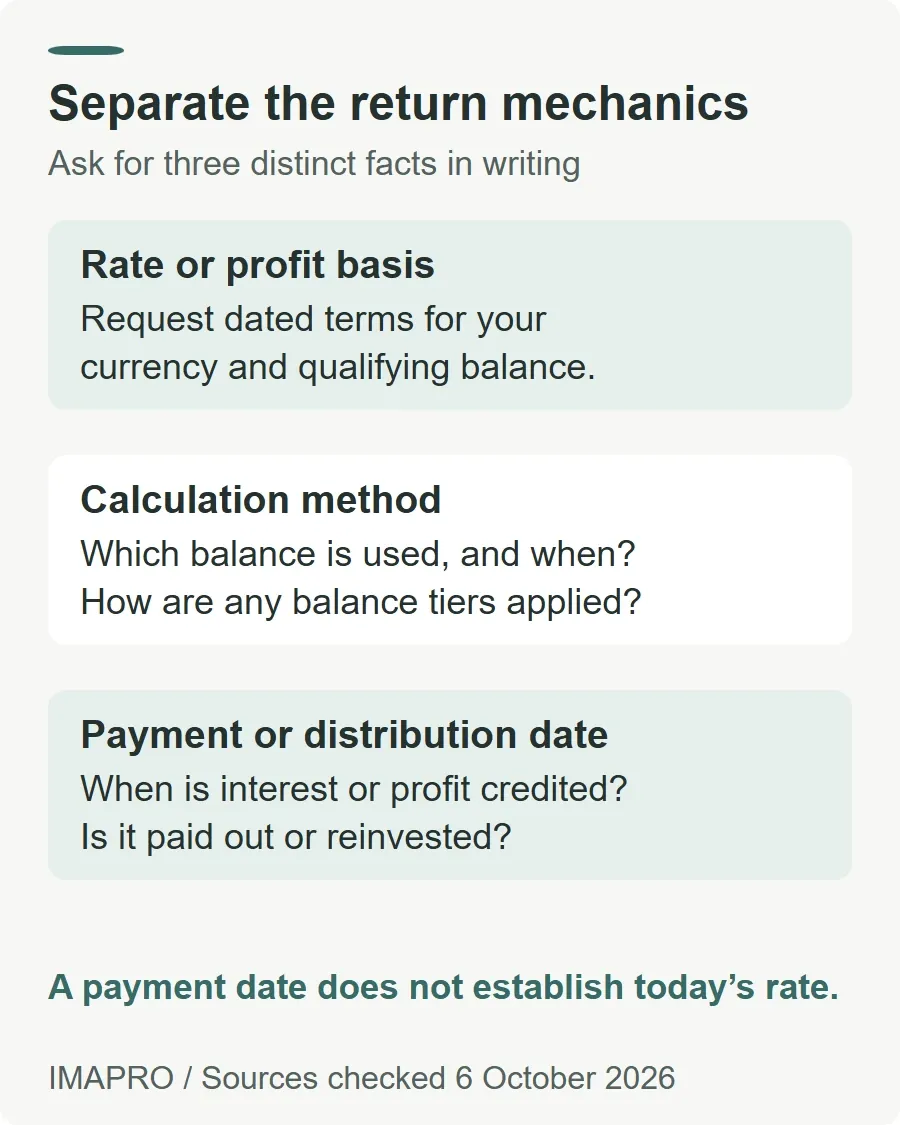
An annual percentage, the balance used to calculate it, and the date money reaches the account are three different facts. Ask for all three in writing. A product described as interest-bearing does not establish today's rate, and a rate shown for another currency or balance band may not apply to you.
| Example | What the official source confirms | What to request separately |
|---|---|---|
| NBK Bahrain Savings Account | Interest calculated monthly, credited on 31 May and 30 November. The account is in BHD. | Current rate and the balance calculation used within each month. |
| ila Hassala | Interest calculated daily and paid monthly. Customers can switch interest off. | Current rate for the chosen currency and account arrangement. |
| BisB Investment Saving Account | Funds invested under unrestricted Mudarabah, with earned profits reinvested under its terms. | Applicable profit-sharing terms, expected versus achieved return and distribution schedule. |
Sources: NBK Bahrain savings FAQ, ila savings FAQs and BisB general terms, Investment Saving Account. These examples describe mechanics, not a like-for-like yield ranking.
ila also states that Savings+ rates can change, with changes communicated through its channels. Do not carry a rate from an old screenshot into a calculation for a new deposit. Save the offer date and ask whether the return is variable, promotional or subject to a qualifying balance.
3. Check which balance qualifies for which benefit
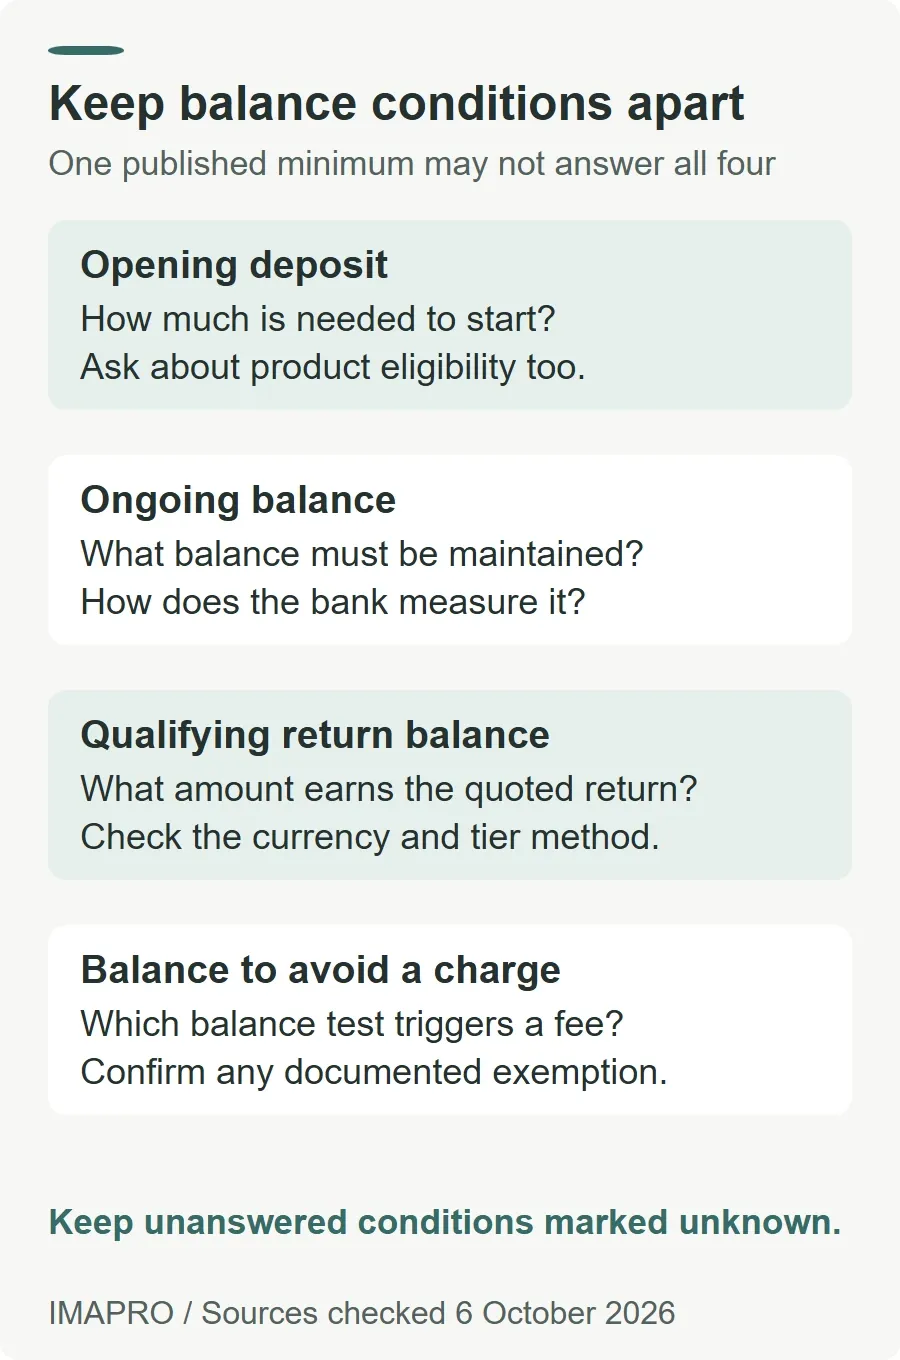
Keep four amounts separate: the deposit needed to open, the ongoing balance requirement, the balance needed to earn a particular return, and the amount needed to avoid a fee. They may coincide, but one published figure does not prove they do.
NBB's Al Mumayaz account page specifies a minimum deposit of BHD 2,000 or foreign-currency equivalent. It lists Bahraini citizens and non-Bahraini residents over 21, and allows up to three withdrawals a month free of charge. Ask how further withdrawals are charged and whether they affect the return. The page's “higher interest” description is not a dated numerical rate quotation.
For any tiered offer, ask whether the quoted rate applies to the whole qualifying balance or only the portion in each band. Also check whether new money, salary transfer, a paid package or a limited promotional period is required. Leave each field unconfirmed until the bank answers; these are comparison questions, not conditions asserted for every account.
Eligibility comes before yield comparisons. Savings+ is for existing ila conventional customers with completed KYC, according to its eligibility FAQ. A product page or application form does not establish that every visitor or non-resident can open it. The Bahrain bank-account opening guide covers the separate document and application task.
4. Compare fees and prize conditions separately
Request the tariff for the exact product, currency and package. Check below-balance charges, withdrawals beyond any allowance, branch transactions and inactivity charges. A fee not mentioned in a short product summary should stay marked “not confirmed”, rather than being entered as zero.
BBK's Super Saver page lists specified groups exempt from minimum-balance fees, including students, pensioners and people earning below BHD 250 monthly. It requires supporting documents to qualify. Confirm the exemption is applied to your account instead of assuming eligibility removes every other service charge.
Prize-linked accounts need another line in the comparison. BisB's Tejoori Al Islami terms describe an unrestricted Mudarabah account with raffle eligibility, BHD 50 to open, and no ATM card or chequebook. Amounts below BHD 50 do not qualify for a draw. A chance to win is not a promised return to each saver.
The same terms distinguish Save Plus, a monthly contribution product with a minimum three-year investment tenor and early-withdrawal charges. That is not the same contract as ordinary Tejoori or an accessible savings pot. Check the full product name rather than transferring features from one product in a bank's savings range to another.
For your comparison, record contractual interest or profit separately from a possible prize. Do not use the largest advertised prize as a forecast of what your account will earn. For everyday card and transfer costs beyond savings, use the Bahrain bank comparison for expats.
5. Confirm protection for the account and legal bank
The CBB consumer overview describes separate conventional and Islamic protection funds, covering eligible deposits and eligible unrestricted investment accounts. The product's marketing name alone does not establish whether your balance qualifies.
For conventional retail banks, CBB rules CP-2.1 and CP-2.2 apply eligibility conditions and a BHD 20,000 ceiling across an eligible individual's eligible accounts at the defaulting bank. Multiple account names, currencies or savings pots do not multiply that ceiling. The rules also address exclusions, joint accounts and set-off of debts.
Ask which legal institution holds the funds, whether the exact account is eligible, and how your other balances at that institution are treated. For an Islamic product, request the applicable Islamic protection rules and account classification. A bank's investment offering should not be assumed to have the same protection as an eligible deposit.
6. Compare the same amount over the same period
Send each shortlisted bank the same amount, currency, expected deposit pattern and likely withdrawals. Ask it to show the resulting interest or expected profit and charges under those assumptions. This makes a comparison more useful than collecting unrelated headline percentages.
- Product and access: exact account name, withdrawal route, notice requirement and any free-withdrawal allowance.
- Return: dated rate or profit basis, qualifying balance, tier method, payment dates and change conditions.
- Cost: recurring fees, below-balance calculation, package charges and relevant withdrawal charges.
- Eligibility: residence, age, relationship conditions and documents that remain outstanding.
- Protection: legal bank, account classification and aggregation with existing balances.
Compare the amount you expect to retain after the charges relevant to your use. Keep possible prize winnings outside that base calculation. Save the dated quotation, tariff and accepted terms so the first statement can be checked against what you agreed.
General information only. This article is not personal financial, investment, tax or legal advice and does not recommend a bank. Confirm current eligibility, return terms, fees and protection with the provider before depositing funds.