Motor cover and purchase
Third-Party vs Comprehensive Car Insurance in Bahrain
By Gaurav Agarwal · Checked 5 October 2026
Third-party insurance is the minimum liability cover for a registered vehicle in Bahrain; it does not pay for damage to your own car when you are at fault. Comprehensive insurance includes the required third-party liability and adds cover for your own vehicle against stated events, subject to insured value, excesses, exclusions and repair terms.
01The core difference
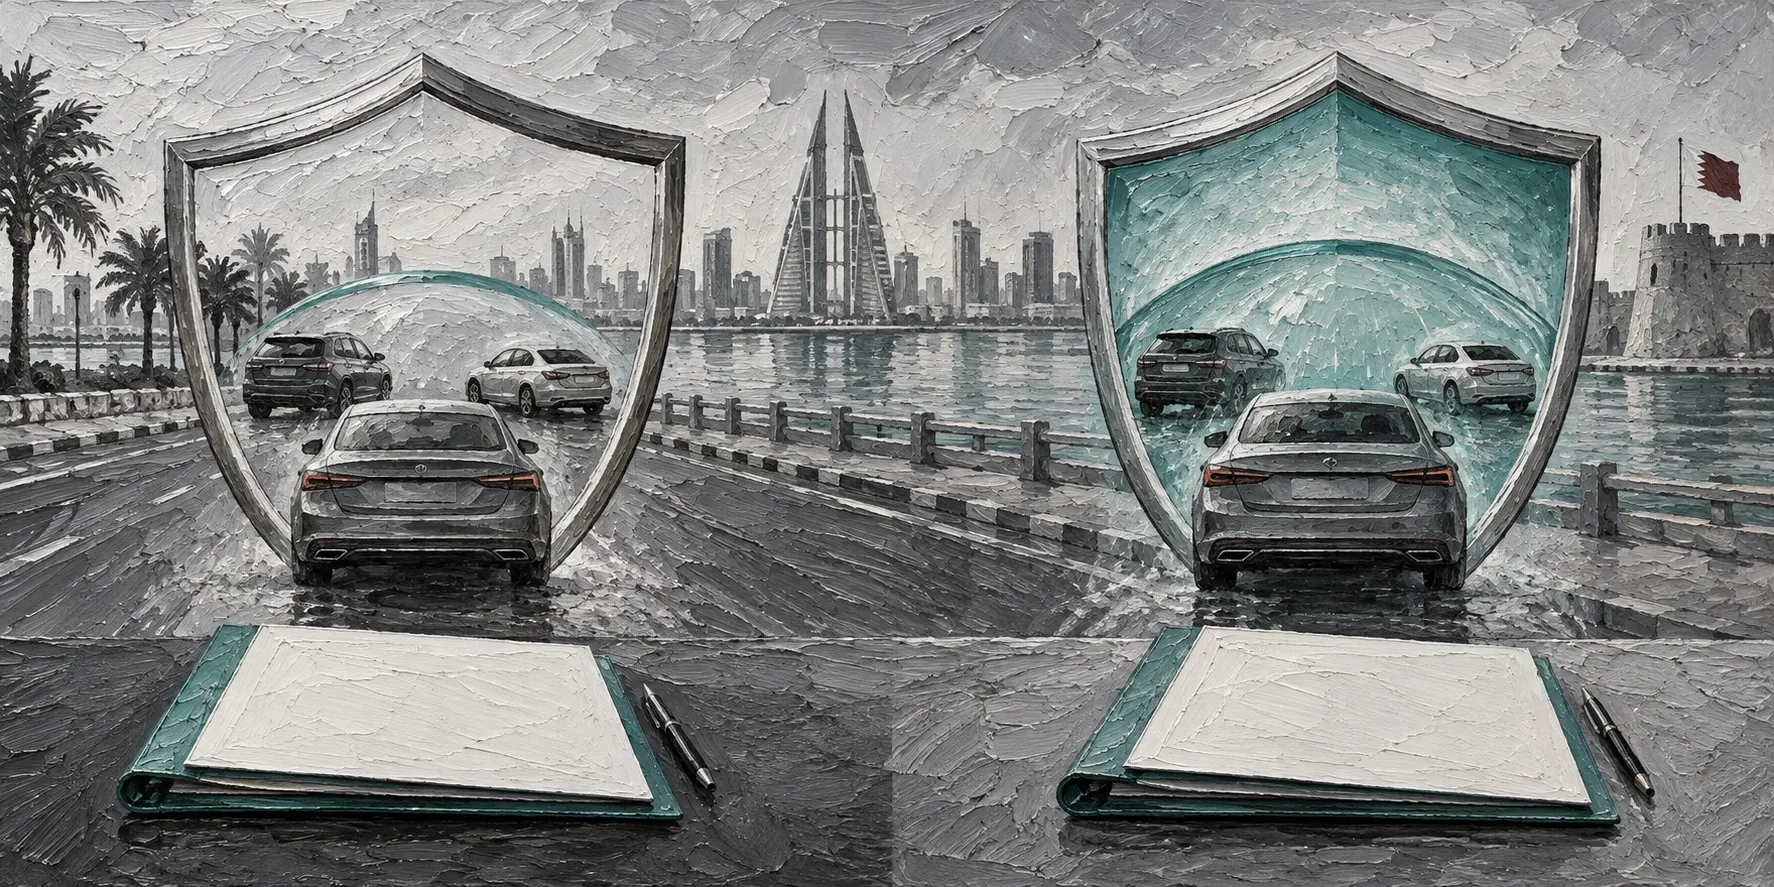
Third-party cover protects against defined legal liability to other people and their property. Comprehensive cover includes that liability and adds protection for loss or damage to the insured vehicle from covered causes. Neither label tells you every limit, excess or exclusion.
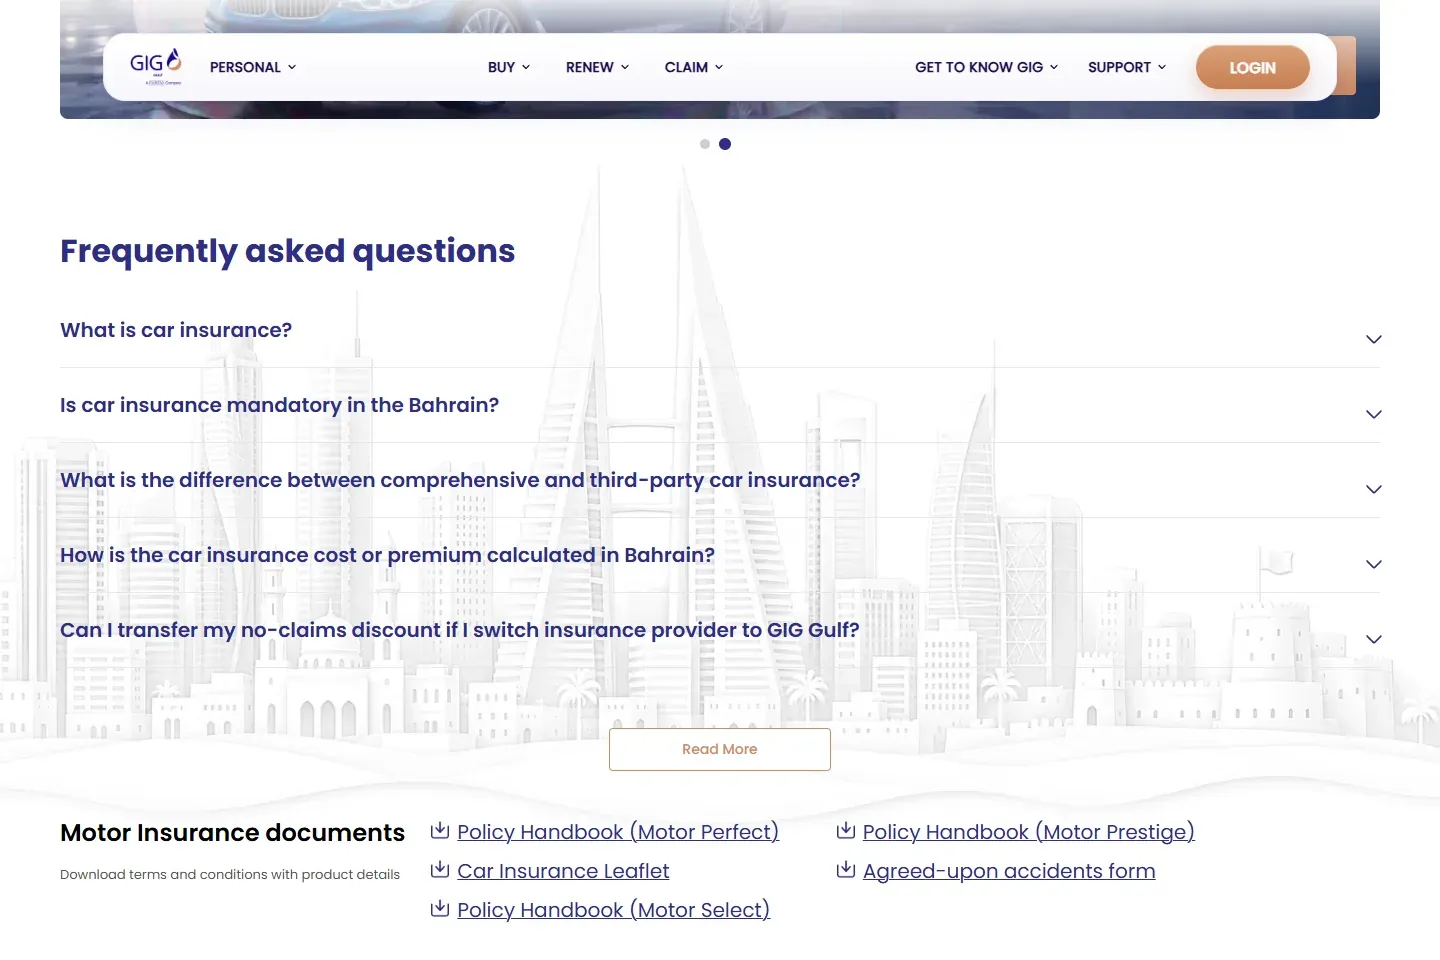
GIG Gulf's Bahrain page describes third-party as the minimum legal cover and comprehensive as adding own-vehicle protection. Its comparison also shows that optional benefits vary by plan. Use this as a clear provider example, then read the wording for the policy you are offered.
02What third-party insurance covers
Third-party motor insurance responds to insured liability for injury or damage caused to others, within the contract and applicable law. It is not a repair policy for your own car when you cause the accident. You would normally bear your own vehicle loss unless another responsible party's insurer pays it.
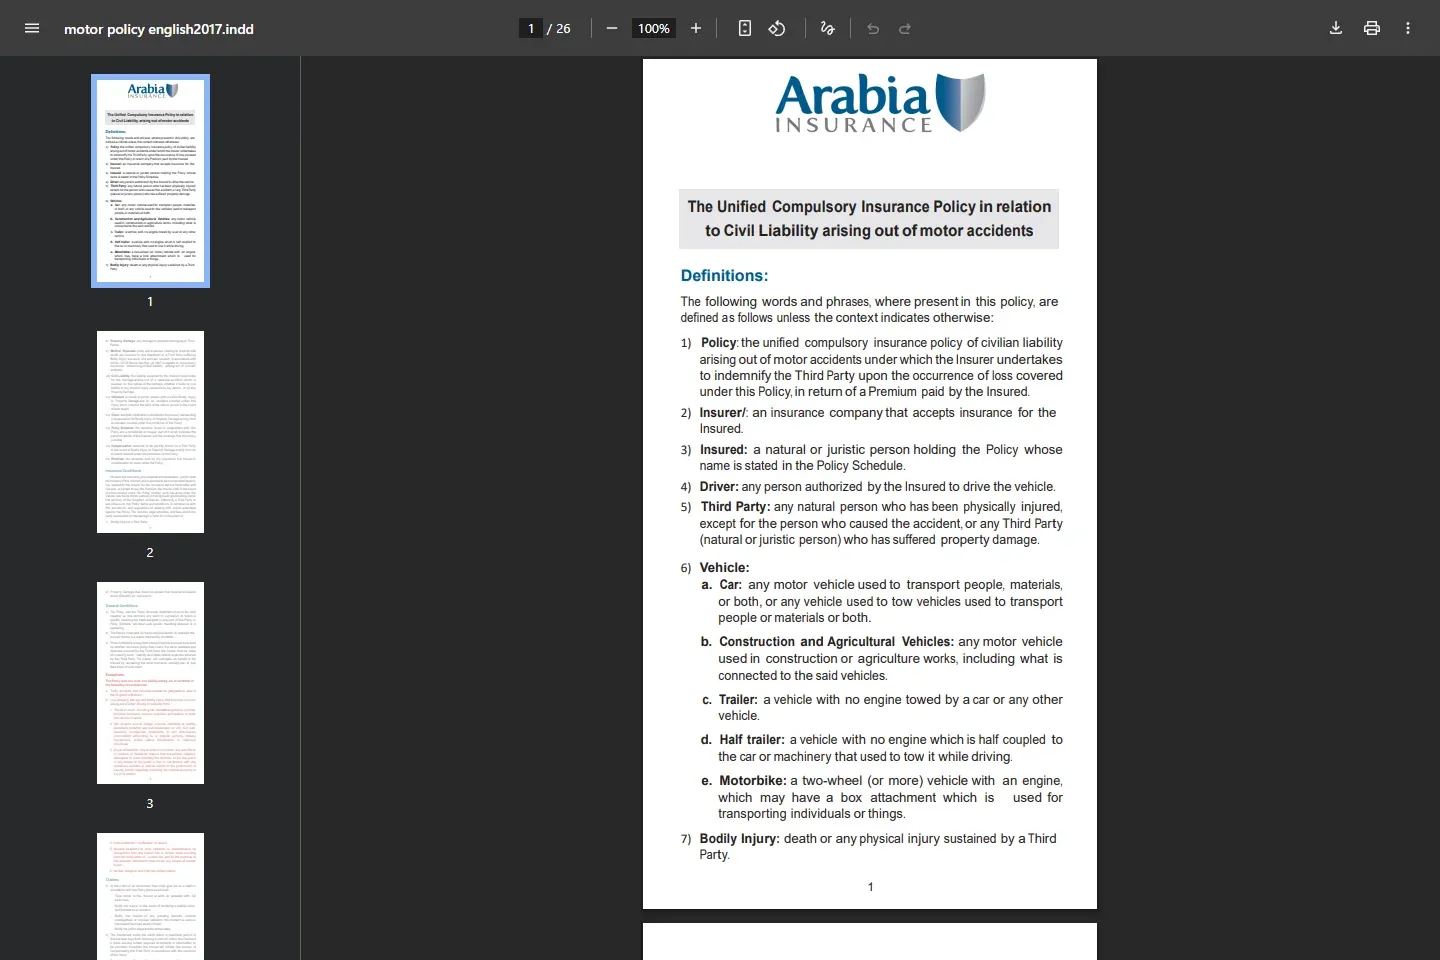
Read the compulsory wording, definitions, exclusions, claim duties and territorial terms. Arabia Insurance's public Bahrain third-party wording illustrates how a liability contract defines the insured, vehicle, third party and use. It is an example from one insurer, not wording for every Bahrain policy.
03What comprehensive insurance adds
Comprehensive cover can add accidental damage to your vehicle and may include or offer theft, fire, natural perils, windscreen, roadside assistance, replacement car, agency repair or GCC territory. The actual causes, limits and options must appear in the schedule and wording.
Comprehensive does not mean every possible loss. Wear and tear, mechanical breakdown, undeclared use, excluded drivers, territorial limits and other conditions can still apply. Finance providers may also require a particular level of cover or interest to be recorded.
04Excess, repair and claims change the value
Ask for the compulsory excess and every additional excess. Check whether repair is at an agency, approved garage or another stated arrangement, and whether depreciation applies to parts. These terms affect what you receive after a covered loss.
With third-party cover, your own at-fault damage remains your cost. With comprehensive cover, a covered own-damage claim may still require an excess and follow repair rules. Use the accident report and claim guide for the reporting sequence.
05Which cover fits the car and your finances
Consider the vehicle's market value, finance terms, repair cost, daily need for the car and your ability to absorb a total loss or major repair. A lower-value older car can make third-party cover a rational choice when the owner accepts the own-damage risk. A newer, financed or essential vehicle can make broader cover more important.
Do not use age alone. A modest-looking car can still be expensive to repair, and a replacement-car benefit can matter if work depends on daily transport. Compare quotes with the same insured value and driver details.
06Compare the official schedule and policy wording
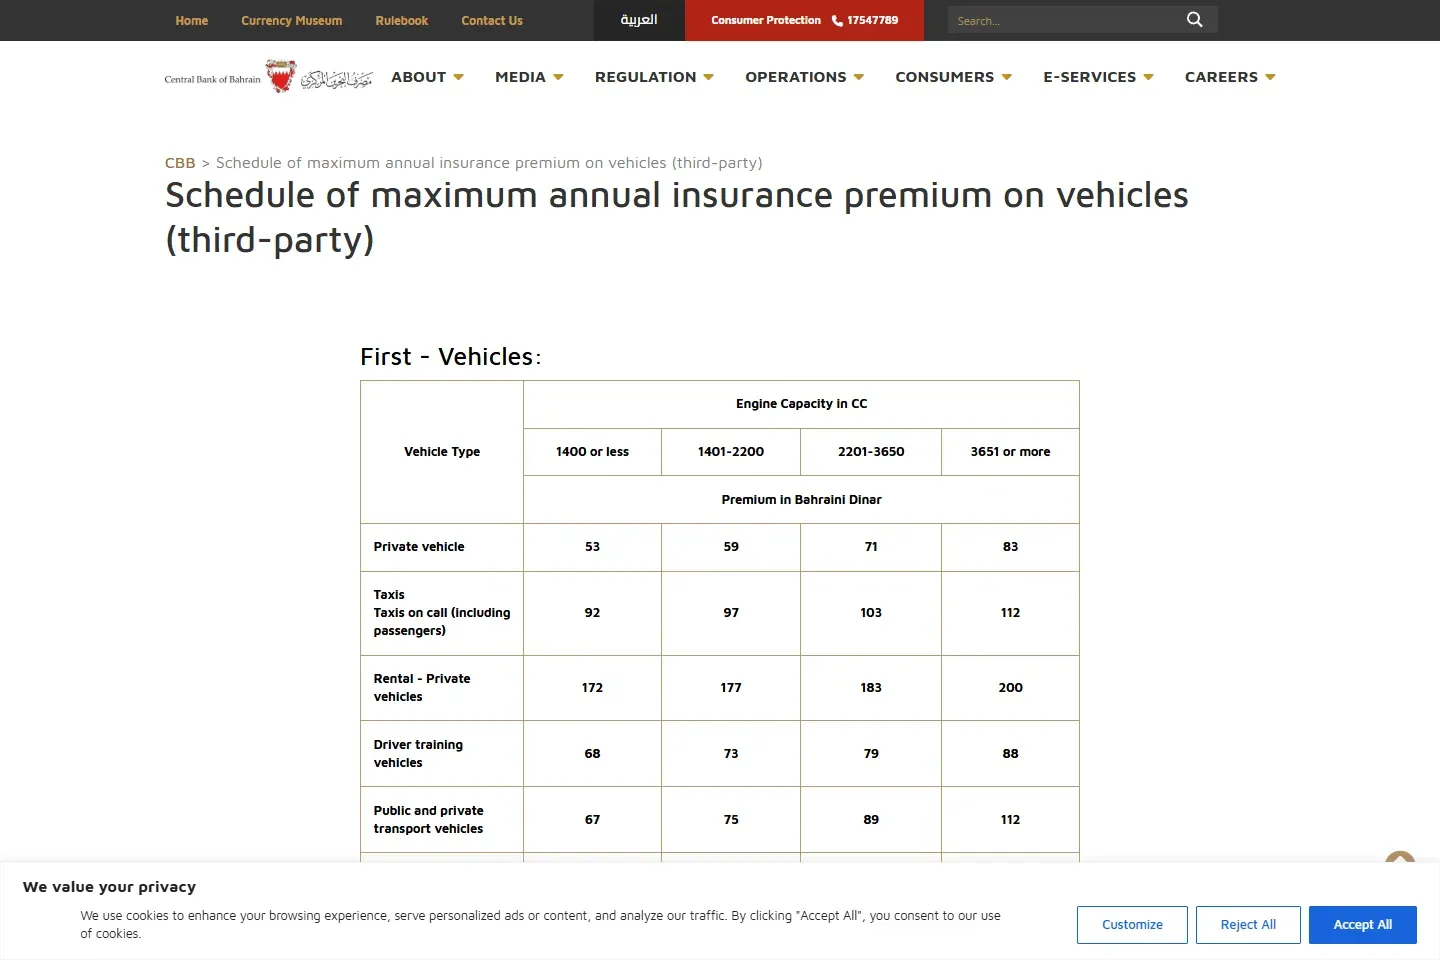
CBB publishes a schedule of maximum annual premiums for vehicle third-party insurance, with categories such as vehicle type and engine capacity. Use the current schedule and calculator as official references for the compulsory cover.
For comprehensive cover, compare the insurer's quote, insured value and contract benefits. Do not treat the third-party schedule as a comprehensive price list. The full-cost guide explains how to compare price without dropping material cover.
07Buy the selected cover and verify it
- Check the legal insurer in the CBB Licensing Directory.
- Confirm the vehicle, policyholder, drivers, use and insured value.
- Read the excesses, repair basis, territory and exclusions.
- Pay through the official insurer or authorised route.
- Save the certificate, schedule, wording and endorsements.
GDT requires vehicle insurance for a full year from the registration date. After issuance, use the vehicle-registration guide for the separate government step.
For prices, the CBB-verified provider list, quote comparison, repairs, claims and every motor guide, return to the Bahrain car-insurance pillar.
After payment, verify the issued policy before relying on the certificate.
08Decision table: what each type leaves with you
Bahrain's compulsory motor framework makes third-party liability the legal baseline. Check the current law in the Legislation and Legal Opinion Commission record, then use the CBB third-party premium schedule and CBB insurance calculator for official pricing references. The issued policy remains the contract.
| Question | Third-party cover | Comprehensive cover |
|---|---|---|
| Damage you cause to another insured party | Core purpose, subject to the policy and legal framework | Included through the liability part of the policy, subject to terms |
| Your own at-fault vehicle damage | Not the purpose of the cover | May be covered under own-damage terms, less applicable excesses |
| Theft, fire or natural perils | Not normally part of liability-only cover | Check the named benefits, exclusions and endorsements |
| Agency repair | Not applicable to your own damage under liability-only cover | Only when the schedule or endorsement grants it |
| Total-loss settlement | Your own vehicle is outside liability-only cover | Check insured value, valuation method, deductions and policy conditions |
The CBB's unified own-damage policy resolution describes minimum comprehensive benefits. Read it with the insurer's full wording. The New India unified comprehensive wording is one public policy document that shows how definitions, exclusions, excesses and claims conditions are presented.
Worked choice for an older paid-off car
Assume a paid-off car has a market value of BHD 2,000. The owner can fund a major repair or replacement without debt and uses a second vehicle for work. Third-party cover may fit that risk tolerance. If the same car is essential for daily work and the owner cannot absorb a BHD 2,000 loss, comprehensive cover can still be rational even though the vehicle is older. The decision depends on the loss you can carry, not age alone.
Worked choice for a financed car
A finance agreement may require comprehensive cover and may specify how the lender's interest is recorded. Confirm the requirement with the lender and make sure the insurer's schedule reflects it. Do not assume a policy meets finance terms because the premium was accepted.
Whichever cover you choose, the GDT registration renewal service states the government renewal route. Verify the insurer in the CBB Licensing Directory before paying.
09Third-party and comprehensive insurance questions
Is third-party insurance compulsory in Bahrain?
Third-party liability is the legal baseline for registering and using a vehicle. Check the current official legal record and GDT renewal conditions, then confirm that the issued certificate matches the vehicle and policyholder.
Does comprehensive insurance include third-party liability?
A comprehensive motor policy normally combines liability protection with own-damage cover, subject to the issued terms. Read the schedule and wording rather than relying on the product name.
Will comprehensive insurance always pay for my own repairs?
No. Coverage depends on the event, exclusions, driver and use conditions, reporting, excesses and the repair basis. Ask the insurer to identify the applicable clause in writing.
Is agency repair automatically included?
No. Agency repair must appear in the quote, schedule or endorsement. Also ask how long the entitlement lasts and whether depreciation or a special excess applies.
Can I change from comprehensive to third-party at renewal?
You can request a different cover type, but first check finance requirements, the vehicle's value and the loss you could absorb. Compare the new schedule and wording before payment.
Recheck the choice every year
A sensible decision can change as the car's value, finance status, daily use and household savings change. At renewal, ask for both cover options where available and compare the same insured value, driver facts and use. Do not let an automatic or one-click renewal hide a changed excess, repair term or benefit limit. Save the new wording and schedule because the prior year's contract does not prove the current year's cover. Keep the comparison with your policy records.
See quotes, claims, renewal and every related guide in the Bahrain motor insurance hub.