Bahrain finance guides
Used-Car Finance in Bahrain: Age, Valuation and Transfer
By Gaurav Agarwal · Sources checked 6 October 2026
Before financing a used car in Bahrain, get the lender to accept the exact vehicle and seller, confirm its value and finance amount, and check how existing finance will be cleared. NFH’s published age limit applies at loan maturity. Traffic requires lender clearance for a vehicle under instalments.
Jump to a section
- 1. Clear the exact vehicle and seller first
- 2. Separate the asking price from the approved finance amount
- 3. Check the records and mechanical condition separately
- 4. Resolve the seller's existing finance before transfer
- 5. Prepare finance and transfer documents as separate packs
- 6. Arrange insurance and complete the ownership change
- 7. Get the final answers before paying a reservation deposit
Official sources checked: 6 October 2026. This guide follows a used car from the seller's quotation to lender approval and ownership transfer. For APR, repayment comparisons and finance structures, use the separate Bahrain car-finance guide.
1. Clear the exact vehicle and seller first
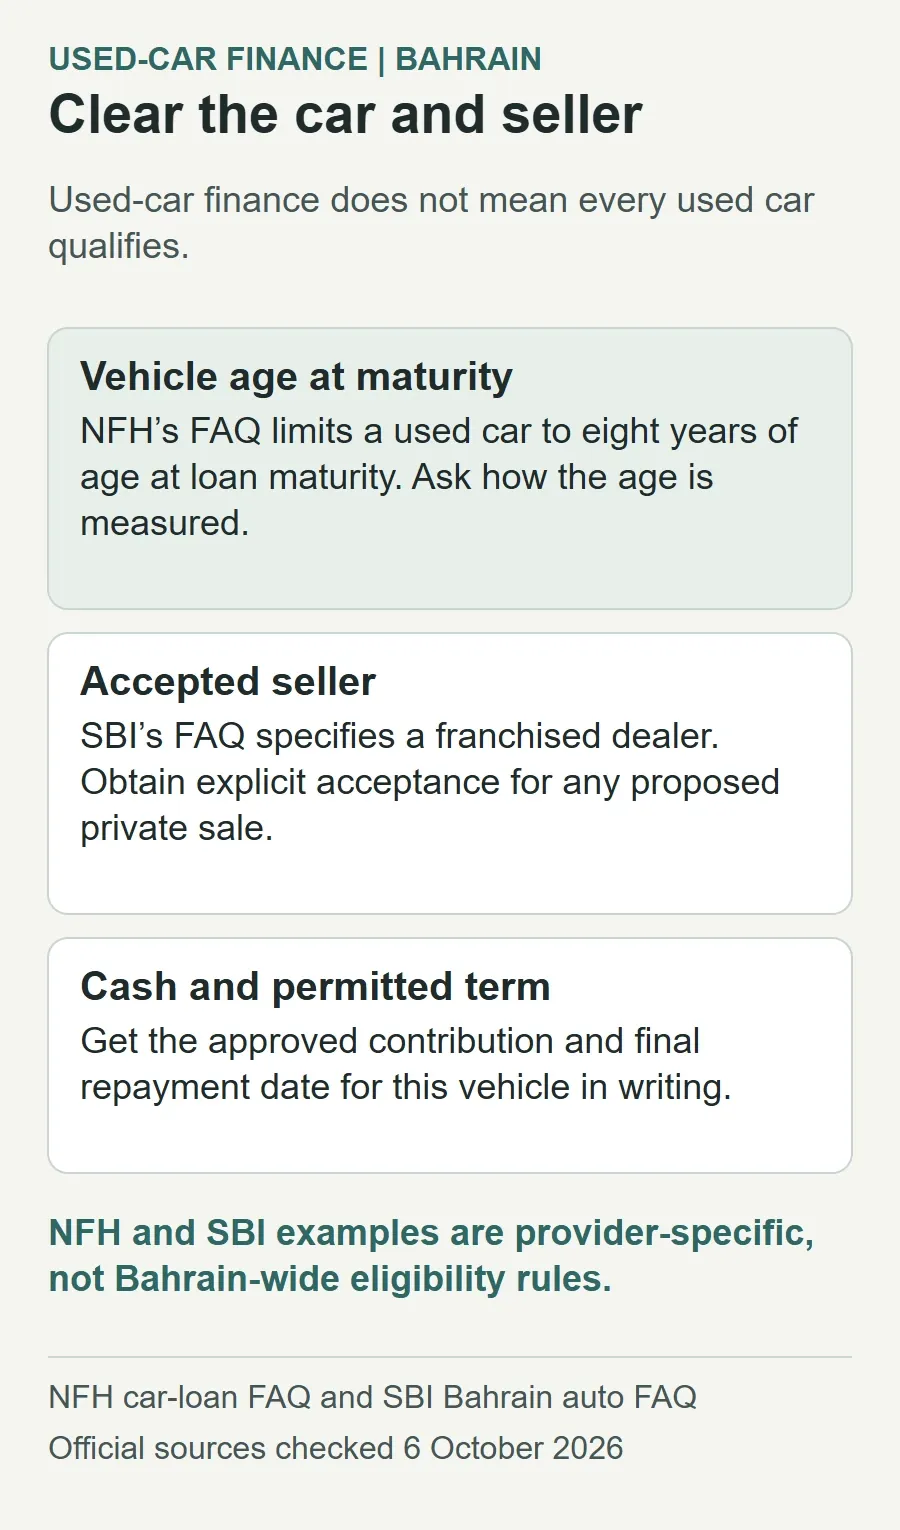
Give the lender the car's make, model, chassis number, registration details, asking price and seller identity before treating an approval estimate as usable finance. Ask it to confirm the vehicle and seller together. A product advertised for used cars does not establish that a private seller, every dealer or every model year is accepted.
| Provider | Official published condition | What it means for your next step |
|---|---|---|
| National Finance House (NFH) | Its FAQ says a used car must not exceed eight years of age at loan maturity. | Ask for the permitted final repayment date for this car. Today's age alone does not answer the question. |
| SBI Bahrain | Its live FAQ restricts auto finance to new or used cars from a franchised dealer and states at least 20% down payment for a used car. | Clear the selling dealer and obtain the actual cash contribution before reserving the vehicle. |
Sources: NFH car-loan FAQ and SBI Bahrain auto-loan FAQ. These are provider-specific disclosures, not Bahrain-wide age or deposit rules. They do not guarantee your approval.
For a private sale, obtain explicit written acceptance of that seller and ask who receives the lender's payment. Do not infer private-sale eligibility from a dealer-finance advertisement. Also confirm whether the bank calculates vehicle age from manufacture, model year or original registration; the NFH FAQ does not spell out that calculation.
2. Separate the asking price from the approved finance amount
The seller's price is one figure. The lender's accepted vehicle value and approved contribution are separate figures to obtain in writing. Ask whether a valuation is required, who may provide it, how long it remains valid and whether any fee is payable if the application fails.
Use this worksheet for the actual quotation:
| Field | Written confirmation to obtain |
|---|---|
| Agreed vehicle price | The precise car and everything included in the sale. |
| Accepted vehicle value | The lender's value, supporting report and any conditions. |
| Payment towards the purchase | The amount the lender will actually pay towards the vehicle. |
| Your contribution | The remaining purchase price after lender payment, with any deposit already paid credited once. |
| Separate costs | Valuation, inspection, insurance, transfer and finance charges, identifying which are financed and which are paid in cash. |
If the approved lender payment is below the balance due to the seller, that gap still needs resolving. A quoted deposit percentage alone is not enough to calculate it. This guide does not assume a universal valuation ratio or invent a valuation fee.
3. Check the records and mechanical condition separately
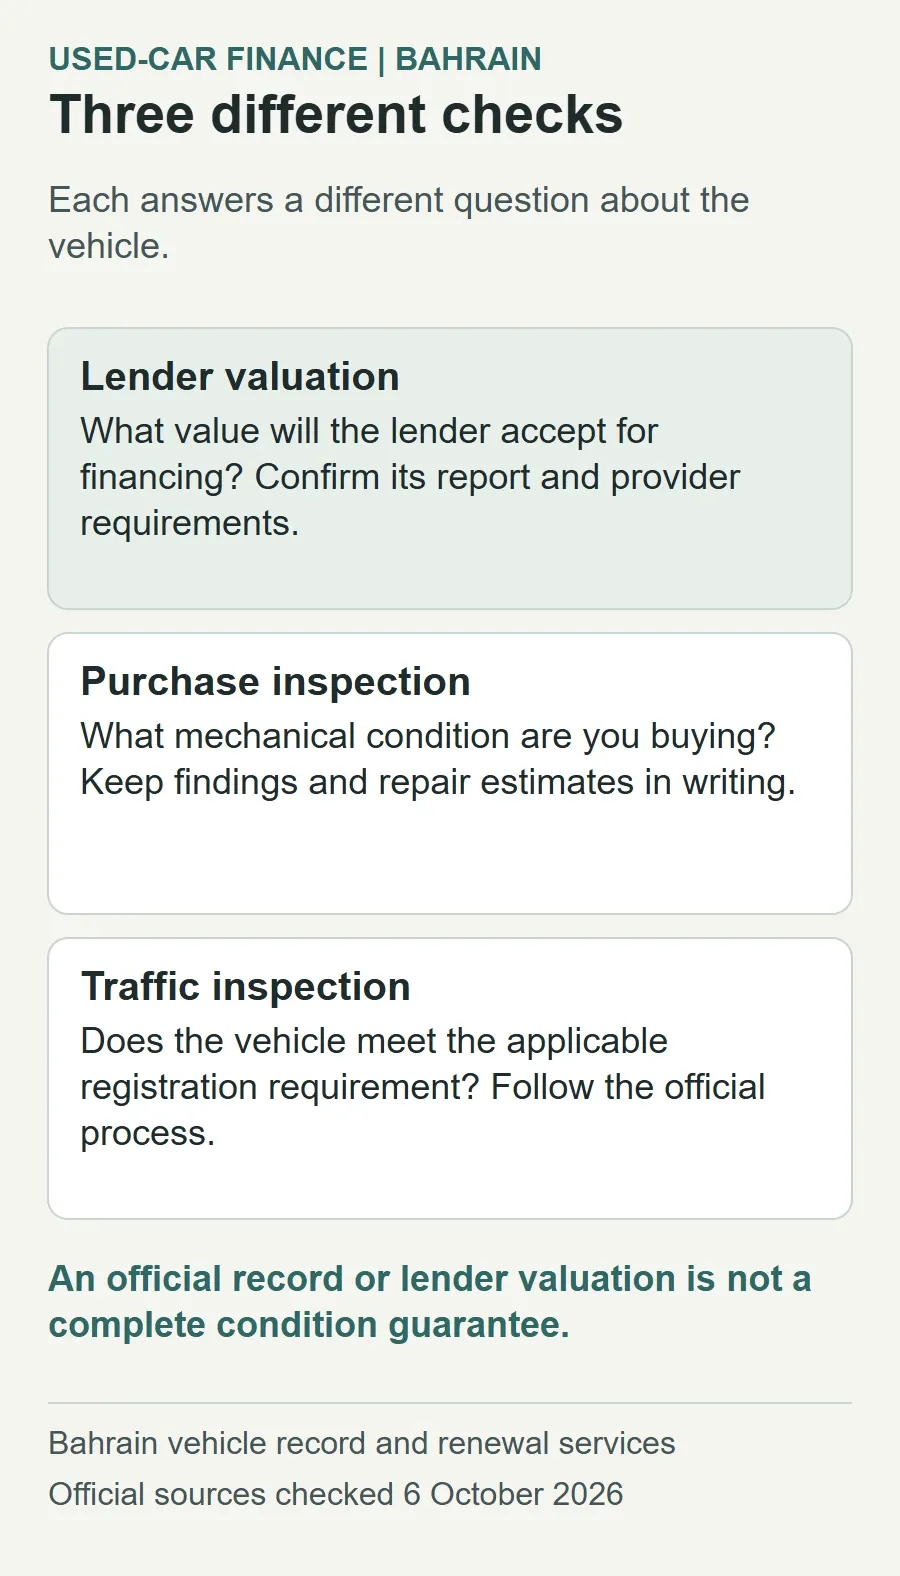
The General Directorate of Traffic provides an official Enquire About Used Vehicles service. Open that service with the seller and review the available record for the actual car. The public service description does not promise a complete maintenance, mileage or overseas accident history, so do not treat a limited record as a guarantee.
Arrange a mechanical inspection before committing to the purchase. Ask the inspector to identify the vehicle, record observed faults and distinguish immediate repairs from routine servicing. Keep the written findings and any repair estimate with the quotation. This is a buyer's check, not a claim that every lender requires the same inspection.
Keep the purposes clear:
- Valuation: the value accepted for the financing decision.
- Purchase inspection: the condition you are agreeing to buy.
- Traffic inspection: a registration requirement when applicable.
The official registration-renewal service requires a technical inspection where applicable. It does not turn a lender valuation into a mechanical guarantee. If registration needs renewal, follow the separate Bahrain vehicle-renewal guide.
4. Resolve the seller's existing finance before transfer
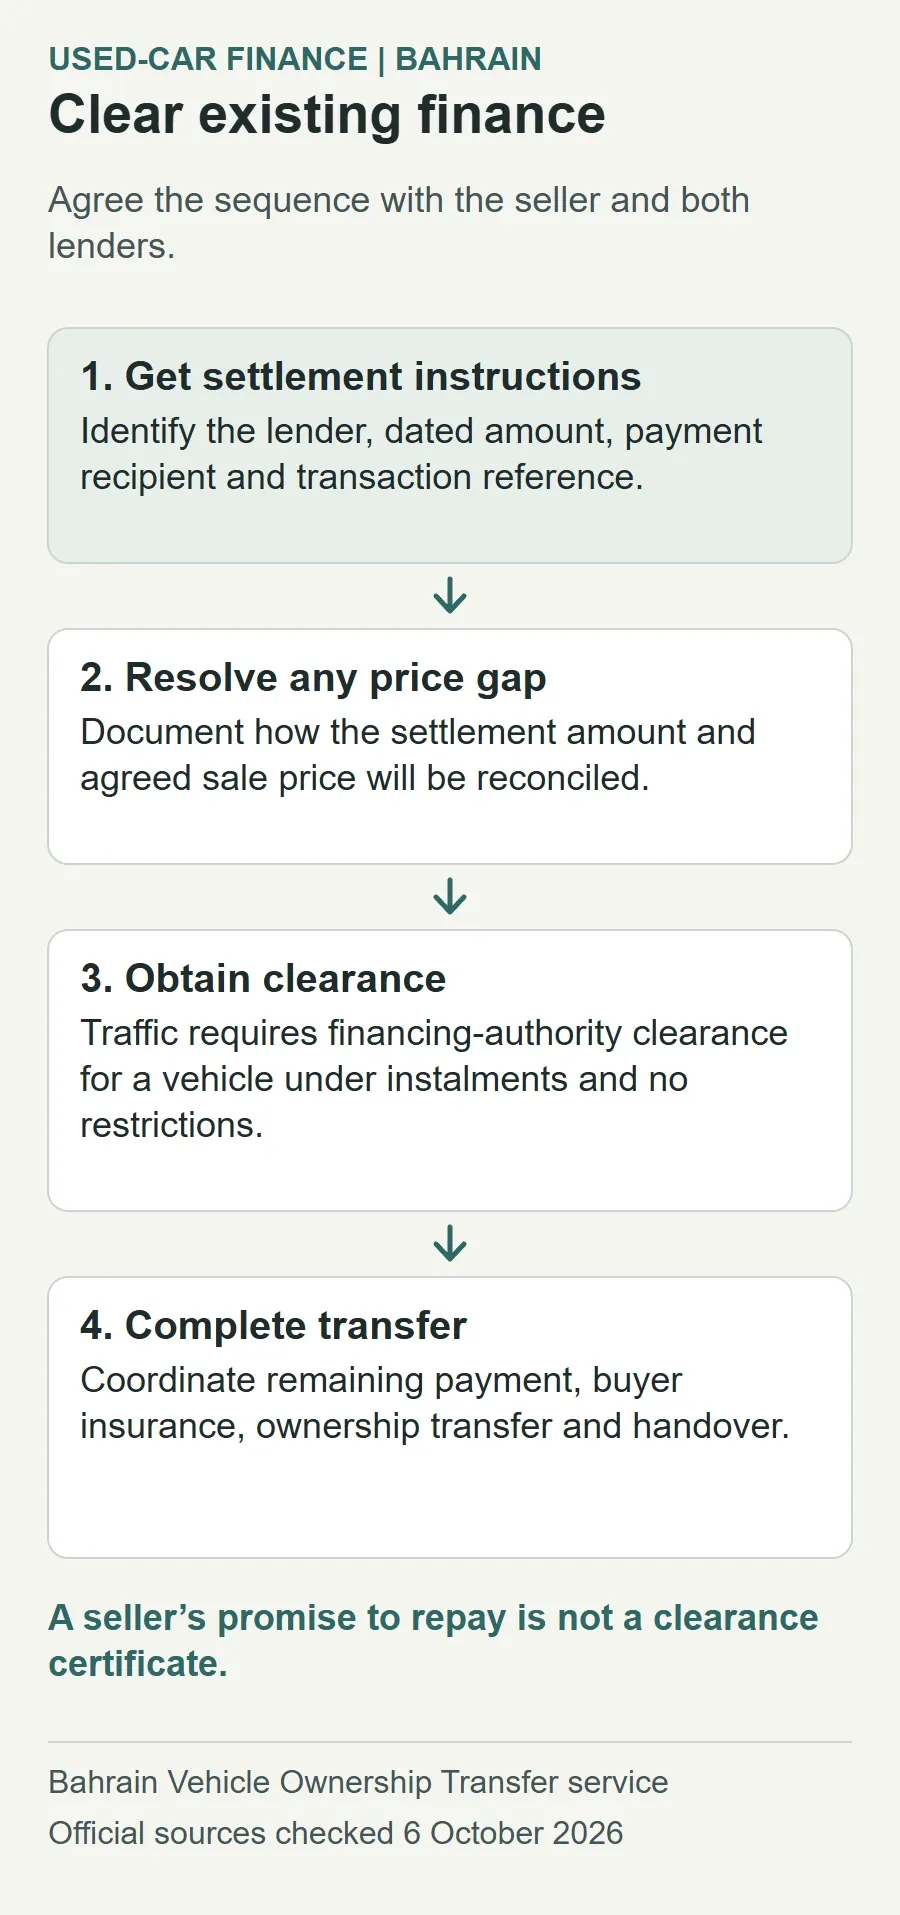
Ask whether the vehicle is still financed and which institution holds the security. The official Vehicle Ownership Transfer service requires the car to be free of restrictions and requires a financing-authority clearance certificate when it is under instalments.
Before paying money intended to clear the seller's debt, obtain the lender's dated settlement instructions and agree a documented sequence with the seller and your own lender. Confirm:
- Who pays the existing lender and how the payment is identified.
- How any difference between the settlement amount and sale price is handled.
- Who obtains the clearance and verifies that the restriction has been dealt with.
- When the remaining seller payment, ownership transfer and vehicle handover occur.
A seller's promise to clear the loan is not the clearance document. Do not describe taking over the seller's monthly payments as an approved transfer of their finance contract; that needs the lender's agreement.
5. Prepare finance and transfer documents as separate packs
For its car-loan application, NFH publishes an original salary certificate or latest payslip, three months of bank statements, and original CPR and passport. Obtain its complete checklist for your case. NFH application documents.
Keep that applicant pack alongside the vehicle quotation, accepted valuation if required, inspection findings, seller details and any existing-finance clearance. Ask the lender which vehicle documents it requires before approval and which are needed before payment. Submit identity and financial records through its verified channel.
For Traffic ownership transfer, the published attachments include valid buyer and seller IDs, the ownership certificate and the completed licensing form. Company-owned vehicles need the specified CR, stamped form and authorised-signatory letter. The service also sets out buyer and seller signature requirements. Read the current transfer checklist before booking.
6. Arrange insurance and complete the ownership change
Traffic requires valid registration, civil-liability cover in the buyer's name for the registration period, and settlement of relevant fines, contraventions and accident claims. The transfer service lists a total fee of BHD 16. These are the published requirements and fee checked on 6 October 2026; additional finance or insurance charges are separate. Official ownership-transfer service.
Ask the lender and insurer to confirm the cover, insured vehicle value, beneficiary and start date required for your financed purchase. Align that date with the agreed transfer and handover. A seller's existing policy is not proof that the buyer's required cover is in place.
The official transfer page directs applicants to book through Mawaeid, attend a Traffic service centre with the documents, complete verification and pay. Follow the current service instructions for attendance and signatures. Keep the updated ownership document, insurance policy, clearance and payment receipts together.
7. Get the final answers before paying a reservation deposit
Have the lender confirm the car, seller, accepted value, approved payment and permitted term. Have the seller confirm the vehicle description, condition, existing-finance status, final price and reservation-refund terms. Agree what happens if finance is declined, the valuation changes or an inspection identifies a problem.
Then compare the dated offer using the APR and total-payment checklist. Approval for your income, acceptance of this used car and readiness to transfer ownership are separate decisions. Get all of them resolved before treating the purchase as complete.
General information: This is a purchase checklist, not individual financial or legal advice. Public lender pages do not establish every vehicle-age method, private-seller rule or valuation condition. Confirm the current written offer for the exact transaction.