Bahrain finance guides
Car Loans in Bahrain: Deposit, Costs, Insurance and Sale
By Gaurav Agarwal · Sources checked 6 October 2026
Compare the cash required, complete repayment schedule, insurance and release conditions before signing for the exact car.
Jump to a section
- 1. How much cash is needed before delivery?
- 2. Check your eligibility and the exact car
- 3. Compare APR, repayments and fees together
- 4. Identify the finance structure before signing
- 5. Separate motor insurance from finance protection
- 6. Selling the car or settling early
- 7. Take one complete document pack to the comparison
- Questions about car finance in Bahrain
For a car loan in Bahrain, compare the cash needed before delivery, the complete repayment schedule and the conditions for insurance and selling the vehicle. Get the offer for the exact car and applicant before paying a deposit. Public bank pages show different deposit options, so one provider’s minimum should not be treated as a Bahrain-wide rule.
Sources checked: 6 October 2026. The bank examples below describe published terms, not approval offers or a ranking of the cheapest lenders.
1. How much cash is needed before delivery?
Ask the lender to separate the vehicle down payment from charges paid before delivery and amounts added to the finance balance. A zero-deposit offer does not, by itself, answer all three questions.
| Provider | Published deposit or vehicle condition | What to confirm in your offer |
|---|---|---|
| BBK | Advertises a 0% down-payment option, financing up to 100% of vehicle value, and new or used cars. | Whether your applicant profile and selected vehicle qualify, plus costs outside the financed value. |
| SBI Bahrain | Its auto-loan FAQ lists at least 10% down for new cars and 20% for used cars, with purchase through a franchised dealer. | The current deposit, accepted dealer and eligibility of the particular used vehicle. |
These are different published offers, not a universal deposit schedule. Check the BBK car-loan page and SBI Bahrain auto-loan FAQ against the dated quotation you receive.
Before paying a dealer reservation amount, ask in writing whether it is refundable if finance is declined, whether it counts towards the vehicle price, and who holds it. Keep the reservation terms and receipt with the bank offer.
2. Check your eligibility and the exact car
NBB’s published car-finance criteria list applicants over 21, with a minimum monthly salary of BHD 300 for Bahrainis or BHD 400 for non-Bahraini residents. These are NBB’s criteria, not a guarantee of approval or another bank’s threshold. Its page also identifies different document requirements for each group. Check NBB’s eligibility and documents.
Get separate answers for the borrower and the vehicle. Ask the lender to confirm:
- Which employment, income, residency and existing-obligation checks apply to you.
- Whether it accepts the seller, vehicle age and condition, and whether a valuation is needed.
- Whether the finance amount is based on the invoice, a valuation or another accepted amount.
- Whether salary transfer, a guarantor or additional security is required.
- How long the approval and dealer quotation remain valid.
Do not assume a private used-car sale qualifies because a bank advertises used-car finance. SBI’s published dealer restriction is one reason to clear the actual seller before committing. Vehicle eligibility, inspection and insurance are also separate checks.
3. Compare APR, repayments and fees together
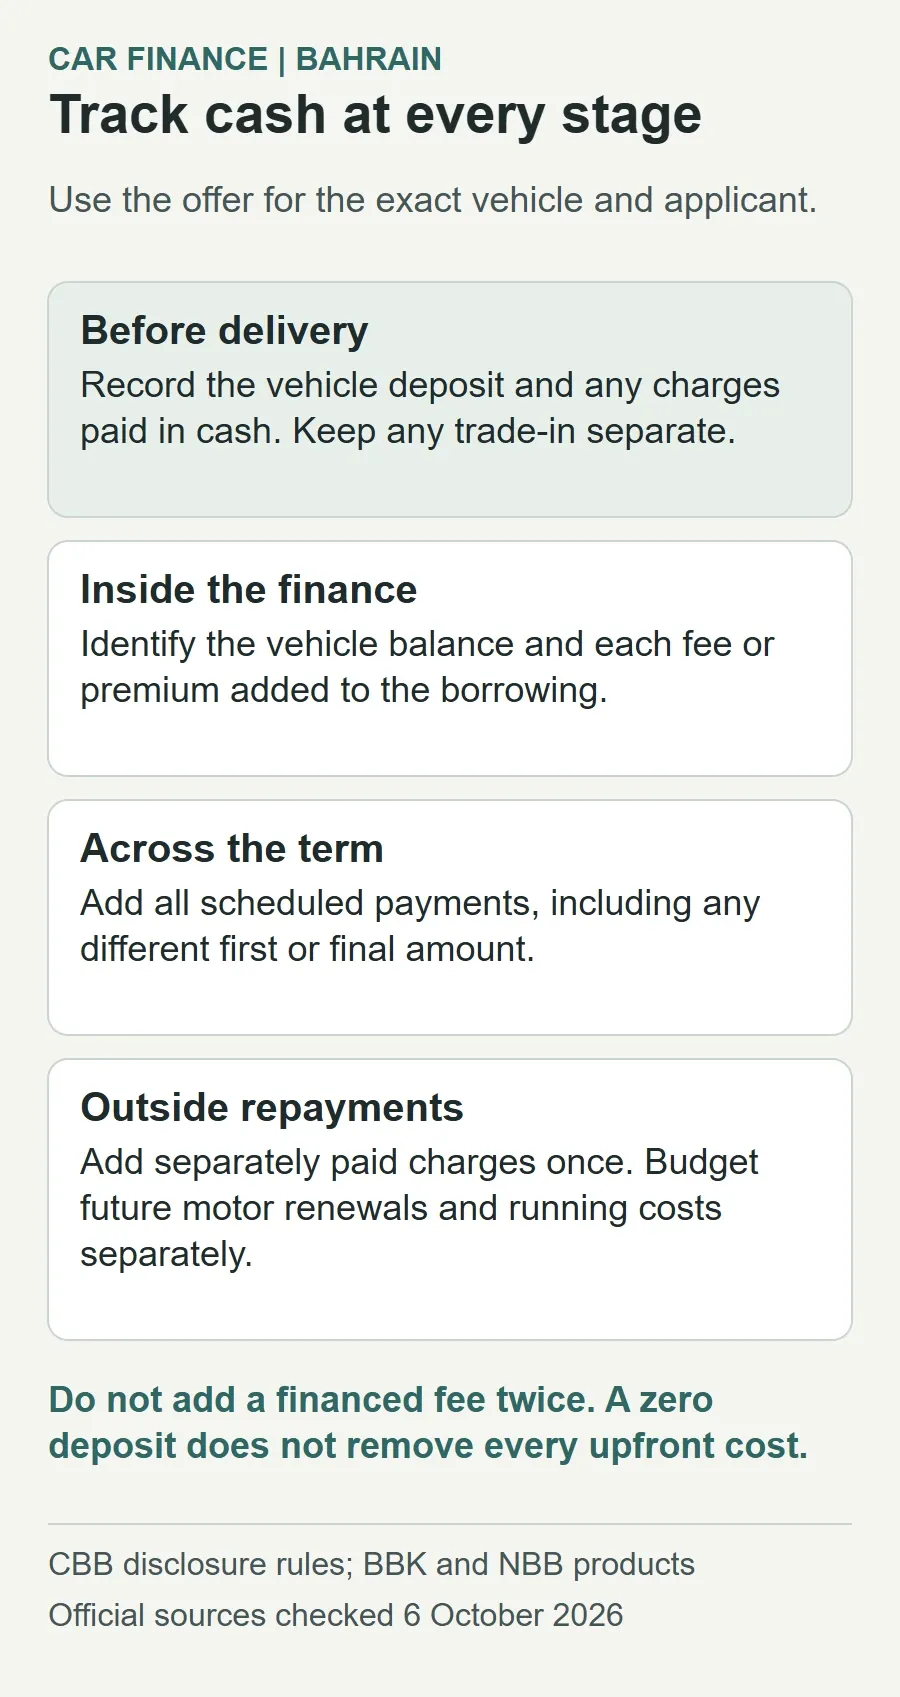
For conventional retail-bank instalment finance, the CBB’s disclosure rules explain APR as a way to compare total credit charges, including relevant fees and mandatory linked costs. They also require disclosure of the repayment breakdown, whether the rate can change and early-payment costs. Ask for the key-terms document and full payment schedule. CBB Rulebook, BC-4.3, particularly 11, 22, 24 and 30.
BBK’s page displays an indicative APR of 4.18% for BHD 10,000 over seven years. That stated amount and term are part of the example: the figure is not a quote for every car or borrower. A marketing rate without its assumptions is an incomplete comparison. BBK’s published APR example.
| Field | What to write down |
|---|---|
| Vehicle and cash payment | Exact car, cash price, deposit and any trade-in amount, recorded separately. |
| Amount financed | Vehicle balance plus each fee or insurance premium added to the borrowing. |
| Rate and term | APR, interest or profit calculation, fixed or variable terms, and repayment dates. |
| Total payable | All scheduled payments, including any different first or final payment. |
| Cash charges | Administration, valuation, insurance, registration or other charges paid outside the repayments. |
| Changes and exit | Late-payment terms, partial repayment, full settlement and release requirements. |
For your cash-flow comparison, add the deposit, all scheduled repayments and charges paid separately. Do not add a financed fee again if it is already included in those repayments. Keep future motor-policy renewals and running costs on a separate budget line rather than presenting them as a fixed borrowing charge.
Compare like-for-like offers before focusing on the monthly instalment. If a grace period is offered, request the dated schedule showing when charges start and how the first payment changes. Do not infer that a delayed first payment is free finance.
4. Identify the finance structure before signing
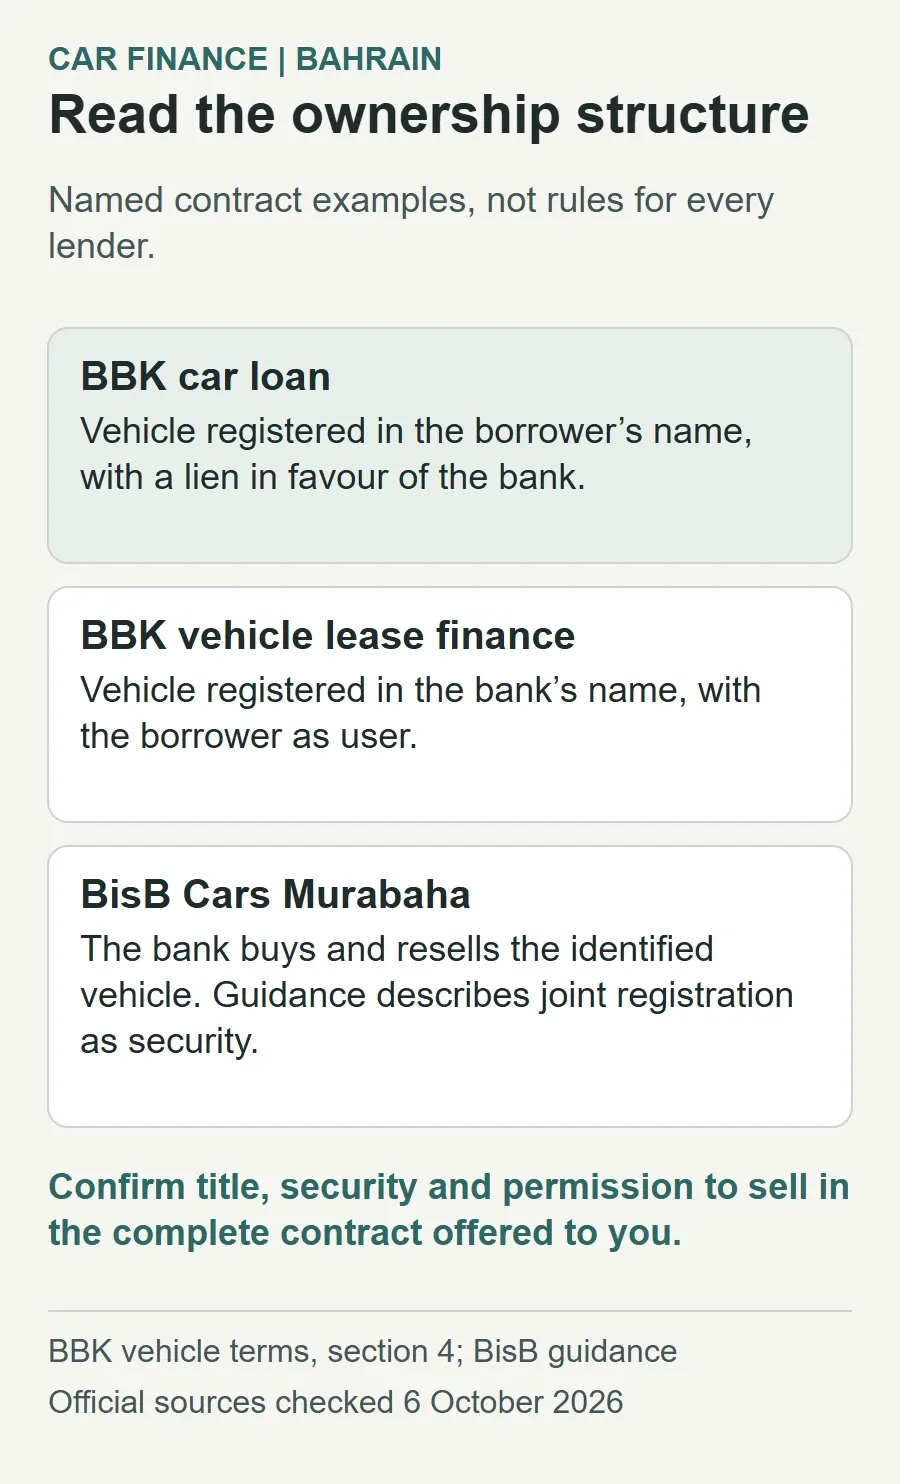
Ask whether the document is a car loan, vehicle lease finance or a purchase-and-resale arrangement. The label affects which ownership and security provisions you need to read.
BBK’s terms distinguish a car loan registered in the borrower’s name under a bank lien from vehicle lease finance registered in the bank’s name, with the borrower as user. That distinction is specific to the arrangements described in those terms. BBK vehicle-financing terms, section 4.
BisB’s Cars Murabaha guidance describes the bank buying an identified vehicle and then selling it to the customer with disclosed profit and costs. It says the car is registered jointly as security and cannot be sold to another party without bank approval. Its guidance also addresses an earlier dealer reservation contract, so ask the bank about the required sequence before reserving the car. BisB Cars Murabaha guidance, transaction steps.
Read the complete contract you are offered. A general product page cannot settle who holds title, what security exists or which disposal restrictions apply to your transaction.
5. Separate motor insurance from finance protection
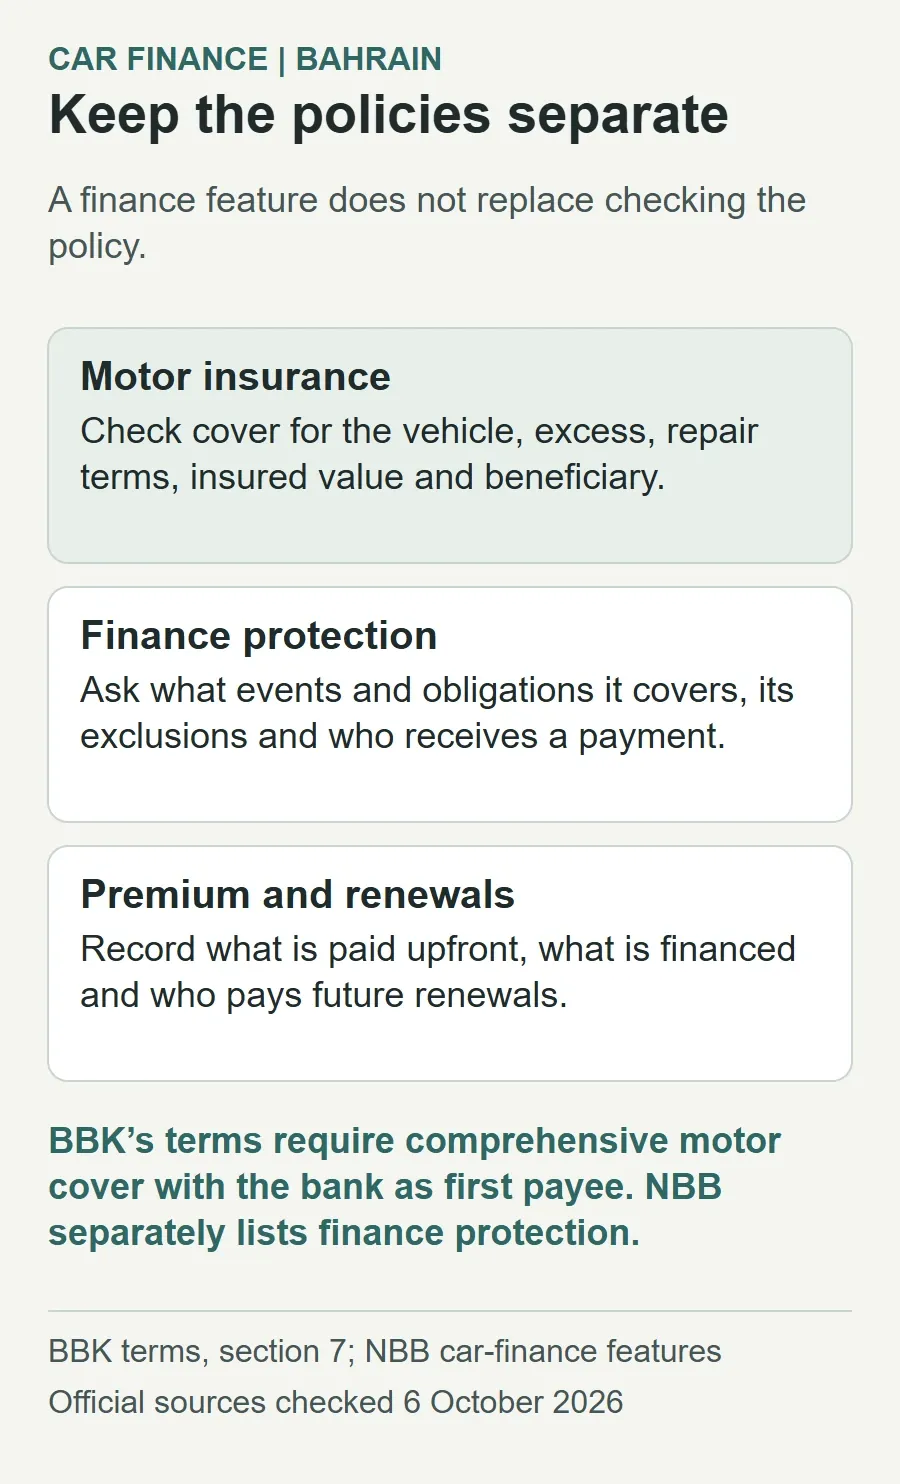
BBK’s vehicle-financing terms require comprehensive motor cover with the bank as first payee, and place subsequent renewals at the borrower’s cost. Confirm how the premium is paid and what happens to an insurance payout. These are BBK contract terms, not a statement that every finance product uses identical wording. BBK terms, section 7.
NBB separately lists finance protection insurance among its car-finance features. Ask what the quoted policy protects, its exclusions, who receives a payment and whether its premium is financed. Do not assume finance protection replaces the vehicle’s motor policy. NBB car-finance features.
Use the Bahrain car-insurance guide to compare motor cover, excess and repair terms. This finance guide deals with the lender’s requirements and how the premium enters the cost, rather than ranking insurers.
6. Selling the car or settling early
Request a settlement statement for the intended payment date before agreeing a sale. For conventional retail banks, CBB rule BC-4.3.30 addresses requested disclosure of the full prepayment amount, calculation and relevant charges. CBB prepayment disclosure requirements.
BBK’s terms require written bank approval before disposal and say its lien is removed after the outstanding financed balance and other amounts due are paid. Ask for the release process and confirmation of completion; a payment receipt alone does not describe the remaining registration work. BBK terms, sections 21 and 22.
- Obtain the dated settlement amount and an itemised explanation of charges or adjustments.
- Confirm the bank’s consent, payment recipient and release documents before arranging the sale.
- Keep evidence that the finance account and vehicle security have been dealt with.
- Complete the separate Traffic ownership-transfer and insurance steps using the current official requirements.
Bahrain’s Traffic implementing regulation addresses ownership-transfer evidence and insurance in the new owner’s name. Its 2022 amendment changes the ownership-certificate provision. Neither a sale agreement nor paying the bank should be treated as the entire Traffic process. Traffic regulation, article 125; 2022 amendment to article 126. No transfer-fee figure is quoted here without a current service tariff.
7. Take one complete document pack to the comparison
NBB’s list for non-Bahraini applicants includes a passport, valid residence permit, CPR, salary and employer documents, and three months of bank statements. Other banks may ask for a different set, so use the chosen lender’s checklist. NBB required documents.
Alongside the application papers, keep the vehicle quotation, written finance offer, repayment schedule, key terms, fee schedule, insurance wording and dealer reservation conditions. Ask the bank to reconcile any difference between the advertised feature and the offer before signing. Submit identity and financial records only through the provider’s verified channel.
Registration remains a separate task after the finance and insurance arrangements are ready. Our vehicle-registration renewal guide covers renewal checks; it should not be used as a substitute for an ownership-transfer procedure.
Questions about car finance in Bahrain
Is a zero-down-payment car loan available?
BBK advertises that option, subject to the actual finance offer. Confirm eligibility and every amount due before delivery. It does not mean every bank offers the same deposit or that all other costs disappear.
Can an expatriate apply?
NBB publishes a non-Bahraini resident category. Meeting a listed salary threshold is only part of the application; obtain the lender’s decision for your circumstances and vehicle.
Which bank has the cheapest car loan?
The reviewed pages do not establish a cheapest offer for every applicant. Compare dated quotations for the same car, deposit and term, using APR, total payments and separately paid costs.
Is there one early-settlement fee for every car loan?
Do not infer one from another provider’s advertisement. Request the settlement calculation for your contract and payment date, including any release charges and insurance adjustment.
General information: This is an independent comparison checklist, not personal financial or legal advice. Imapro does not approve finance or guarantee eligibility. Product terms can change; confirm the dated offer and contract before paying or signing.